

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: HFO Cooling Fluids for Data Centers Poised for Explosive Growth, Forecasting an 18.02% CAGR

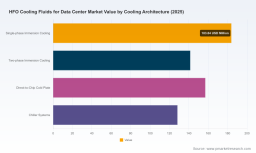
Hfo Cooling Fluids For Data Center Market — Strategic Briefing for 2026 Decision-Makers
The market for HFO cooling fluids in data centers has moved from niche pilot projects to an investment-grade industry in under a decade. Our latest market model shows global revenues expanding from USD 285.4 Million in 2020 to USD 610.5 Million in 2025, and accelerating through the forecast window to reach USD 1,947.03 Million by 2032. The forecast period (2026–2032) carries a projected compound annual growth rate (CAGR) of 18.02% (USD, revenue in Million). For corporate leaders planning capital allocation, procurement strategies, or R&D roadmaps in 2026, these dynamics are no longer hypothetical — they will materially affect supplier selection, partner strategies, and regulatory compliance pathways.
Hfo Cooling Fluids For Data Center Market
Why this report is strategically material for 2026
-
Regulatory inflection points are concentrated in the 2026–2028 window. The U.S. EPA Technology Transitions rule establishes binding GWP limits (effectively reshaping equipment eligibility from 2027), while regional frameworks such as the EU F‑Gas regime and the Kigali Amendment continue to accelerate substitution away from high‑GWP refrigerants. China’s quota and encouragement mechanisms further alter the timetable for global supply and deployment decisions. These rules change not only product eligibility but also procurement risk profiles and inventory strategies.
Hfo Cooling Fluids For Data Center Market -
Supply‑side realities — raw material concentration and price volatility — are already showing in the market. Manufacturers cite dependency on specialized fluorinated feedstocks and olefins; producers have taken price adjustments to pass through input cost inflation. These dynamics make multi‑supplier strategies and long‑term offtake agreements a practical necessity for large-scale data center deployments.
Hfo Cooling Fluids For Data Center Market -
Market concentration is significant: the top three suppliers control a dominant share of commercialized HFO cooling fluid supply, and the top five firms extend that dominance further. Concentration elevates counterparty risk and increases the strategic value of early qualification and partnership agreements.
What PW Consulting’s report delivers to executives
This report was written to convert technical complexity into decision‑grade outputs. It is not a catalogue of raw tables; it is a toolkit designed for Chief Technology Officers, Head of Procurement, Head of Data Center Operations, and Corporate Strategy teams who must make investment calls in 2026. Key deliverables include:
- Transparent market sizing and an auditable methodology for historic and forward estimates (2020–2032), presented in USD Millions and stress‑tested through scenario analysis.
- A regulatory impact map tying global and regional policy milestones to equipment eligibility, compliance cost impacts, and deployment timing windows.
- Supply chain mapping and supplier risk scoring, including feedstock exposure, manufacturing capacity posture, and ease of qualification for hyperscaler and colocation environments.
- Techno‑economic models (modular TCO) that capture energy, water, maintenance, compatibility testing, and end‑of‑life disposals; these models are designed to be instantiated on real deployment parameters.
- Operational playbooks: step‑by‑step qualification checklists, sample test protocols, vendor scorecards, and compatibility matrices required for safe field deployment.
- Investment and procurement decision frameworks for CAPEX and OPEX trade‑offs, including alternative scenarios for single‑phase and two‑phase immersion, direct‑to‑chip cold plates, and chiller integration strategies.
- Case studies and first‑mover learnings from commercial trials and full‑scale pilots, with practical recommendations for scaling from rack‑level trials to multi‑MW deployments.
To preserve the commercial value of the dataset and to drive responsible disclosure, this release intentionally highlights trends and strategic implications while withholding granular segment and regional tables. The full report contains the detailed splits and downloadable data tables that drive the models summarized here.
Competitive landscape — players, posture, and what it means for 2026
The HFO cooling fluid market today is defined by a small set of industrial chemical incumbents and specialised fluid innovators. We profile both types and assess commercial posture rather than simply cataloguing products.
-
The Chemours Company — With its Opteon™ 2P50 family and related dielectric heat transfer offerings, Chemours has positioned itself as a commercial anchor for two‑phase immersion applications. Recent milestones (strategic manufacturing agreements and third‑party qualifications) indicate a deliberate move to secure supply chain and co‑development pathways with equipment providers and hyperscalers. For buyers this means established qualification tracks exist, but counterparty negotiation leverage is tied to proven compatibility and volume commitments.
-
Solstice Advanced Materials (formerly Honeywell Advanced Materials) — Solstice‑branded HFOs are being positioned for high‑performance cooling with a strong emphasis on lifecycle environmental performance. The supplier community has faced raw material cost pressures and has implemented measured price adjustments to protect margin. For procurement teams, this underscores the need to model both nominal price and volatility over contract durations.
-
Arkema S.A. — Arkema’s HFO portfolio (including formulations positioned for chillers and immersion) and recent capacity ramp‑up activities suggest an intent to secure both commodity and speciality demand. Increased capacity reduces some upstream supply risk but also signals more aggressive competitive positioning over contract terms and local production advantages.
-
TMC Industries — As a specialised supplier of dielectric HFOs for immersion, TMC represents the category of smaller, agile actors that can move quickly on bespoke formulations and fast qualification cycles. Their presence is critical for operators seeking rapid pilot schedules or niche compatibility requirements.
-
Daikin Industries, Ltd. — Leveraging deep refrigerant experience, Daikin is notable for bridging HVAC/R manufacturing with data center cooling needs. For integrators, this kind of supplier offers end‑to‑end system design capabilities that can simplify vendor management.
Recent public milestones (product qualifications with major storage OEMs, strategic manufacturing agreements, and targeted capacity expansions) validate the pace of commercialization. These developments also change the timetable for decisive procurement: a year’s delay in qualification or contracting can translate into meaningful cost and availability asymmetries.
Strategic recommendations for 2026 — what to do next quarter
-
Prioritise supplier qualification now. Build test plans that include multi‑vendor compatibility tests with target server/storage OEMs and firmware revisions; start with rack‑level trials that replicate full heat density and cycling profiles.
-
Secure conditional supply commitments and consider staged offtake contracts tied to qualification milestones. Where feasible, negotiate price adjustment bands tied to raw material indices to hedge against sudden feedstock cost moves.
-
Embed regulatory scenarios into procurement specifications. Define acceptable GWP thresholds, labelling and documentation requirements, and transition clauses for equipment shipped before regulatory cut‑off dates.
-
Run TCO comparisons that incorporate non‑energy benefits such as water savings, data center PUE improvements, and reduced facility footprint. Use scenario outputs to quantify trade‑offs between single‑phase vs two‑phase immersion and hybrid cooling architectures.
-
Plan manufacturing and logistics footwork around regional regulatory windows. Early local production or secured regional inventory can be a competitive advantage in markets that transition on different timelines.
-
Explore strategic partnerships: co‑development deals with fluid suppliers, white‑label agreements with integrators, or minority investments in specialised chemistry firms can unlock preferential supply and co‑innovation benefits.
Decision‑grade tools included in the report
For teams ready to act, the report includes modular decision tools that translate the analysis into executable programs: a configurable TCO calculator, supplier scorecard templates, a regulatory compliance calendar linked to deployment milestones, manufacturing CAPEX and OPEX build‑out templates, and a risk heat map for supply‑chain shocks.
These instruments are built to be populated with your internal data and to generate board‑level decision memos within weeks, not months.
Next steps — where to get the full dataset
This briefing is intentionally selective: we show the market trajectory, the competitive topology, and the practical levers executives should use in 2026, while the full segment-level tables, regional splits, product-level forecasts, and downloadable model files are reserved for the comprehensive report. For procurement teams, engineering leaders, and strategy groups looking to operationalise these insights, the complete report contains the granular forecasts, vendor scorecards, and test‑protocol annexes necessary to implement the recommendations above.
To obtain the full Hfo Cooling Fluids For Data Center Market report and its decision‑grade toolset, visit the PW Consulting publications page or contact our industry practice. The window to secure advantageous supplier terms and to align deployment schedules with fast‑moving regulatory deadlines is narrow — the best time to start is now.
For detailed analysis of this topic, please visit the official page: Hfo Cooling Fluids For Data Center Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com