

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Mp System On A Chip Market to Surge from USD 195,500 Million in 2025 to USD 363,159 Million by 2032 (2026–2032 Forecast) at 9.25% CAGR — Asia Pacific Leads with USD 98,312 Million

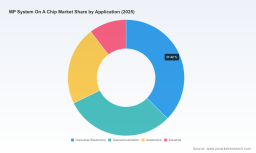
MP System-on-a-Chip (SoC) Market — Strategic Outlook 2026: A PW Consulting Preview
As global systems architects and corporate strategists prepare capital allocations and product roadmaps for 2026, our new Mp System On A Chip Market study provides a focused, decision-grade synthesis of where the industry is headed and how executives should act. The total market for Mp SoCs has expanded materially in the first half of the decade, rising from a mid-four-figure base (USD Million) in 2020 to an estimated USD 195,500 Million in 2025. Under our baseline forecast the market continues to scale, tracking toward roughly USD 215,088 Million in 2026 and reaching the high hundreds of billions by 2032 at a compound annual growth rate (CAGR) of about 9.25% through the forecast window (2026–2032). This growth, combined with a measured market concentration (CR3 ≈ 48.7%; CR5 ≈ 62.1%), frames a landscape of expanding opportunity where a handful of platform leaders coexist with specialized challengers.
Mp System On A Chip Market
Why this preview matters for 2026 decision-making
Two dynamics make 2026 a strategic inflection point: first, the convergence of next-generation process nodes and advanced packaging that materially reshapes performance-per-watt and system integration economics; second, an intensifying policy and supply-chain backdrop that alters geographies of risk and partnership strategies. For boards and product leaders, the immediate questions are whether to accelerate in-house SoC development, pursue chiplet strategies and packaging partnerships, or lean on contract design and foundry ecosystems. Our report is structured to answer those questions with scenario-tested pathways and investment trigger points rather than bright-line prescriptions.
Mp System On A Chip Market
Key technology and market inflection points
- Advanced process adoption and product timing: Leading SoC designers are moving to sub-3nm nodes in 2026 for flagship devices. The performance and efficiency gains are real, but the capital and supply constraints require precise go-to-fab timing to capture value without over-investing.
- Packaging and heterogeneous integration: CoWoS-class solutions and multi-die interposers enable integration of HBM and multiple chiplets with yields that make high-bandwidth, high-performance SoCs commercially viable at scale. This changes the calculus for firms that previously depended solely on monolithic scaling.
- Chiplet standardization: Industry efforts to standardize interconnects are reducing technical friction for heterogeneous integration, creating a market for modular SoC building blocks and enabling new supplier roles across compute, I/O, and accelerator domains.
- Regulatory and incentive landscape: Export controls, national incentives, and procurement policies shape long-term supplier selection and capital deployment. Public funding for domestic fabrication and research increases local capability but also fragments supplier footprints.
What the PW Consulting report delivers (actionable contents)
- Market sizing and multi-scenario forecasts through 2032, with transparent assumptions and sensitivity analyses tied to node adoption, packaging uptake, and macro demand cycles.
- Supply-chain mapping and a layered vendor ecosystem model that identifies single points of failure and strategic suppliers across IP, foundry, packaging, test, and assembly.
- Technology roadmaps and cost-curve modelling for advanced nodes, packaging options, and chiplet vs monolithic approaches—showing breakeven horizons for alternate strategies.
- Competitive playbooks and capability matrices for platform owners, fab-lite firms, foundries, and systems integrators—actionable for M&A prioritization, partnerships, and licensing decisions.
- Commercial go-to-market templates for consumer, telecom, automotive and industrial system OEMs that align product features with procurement cycles and regulatory constraints.
- Risk register and mitigation checklist covering export-control exposure, IP leakage, talent scarcity, and capital intensity—scored by impact and probability.
- Executive dashboards and downloadable datasets suitable for board briefings and investment committees, plus procurement negotiation playbooks for securing advanced-node capacity.
Competitive landscape: what leaders are doing now
The market exhibits a dual structure: a concentrated set of platform leaders and a diverse set of specialized players. Strategic positioning differs markedly by firm focus—mobile & consumer, compute & data center, automotive & industrial, and imaging/embedded SoCs.
Mp System On A Chip Market
- Qualcomm Technologies: Continues to anchor itself in mobile and automotive with integrated modem-to-application platforms. Its value proposition centers on modem-IP integration, connectivity stacks and ecosystem partnerships.
- Apple: Pursues vertical integration with tightly-coupled silicon-software optimization in consumer and computing products—setting performance benchmarks and raising the bar for system-level integration.
- MediaTek: Aggressively pursuing advanced-node leadership while balancing cost-sensitive product tiers. Recent tape-out activity on next-gen nodes signals intent to close the gap with incumbents on flagship performance.
- Samsung: Combines SoC design with foundry and packaging capabilities, enabling strategic product-fabric ecosystem plays particularly attractive to vertically integrated OEMs.
- AMD, Intel, NVIDIA: Each is reshaping SoC boundaries through processor-accelerator convergence for client, data-center and edge applications—competing on heterogeneous architectures and software stacks.
- Broadcom, NXP, STMicro, TI: Strengthen niches in networking, automotive, industrial control and mixed-signal integration—areas where reliability, real-time characteristics and certification matter more than peak FLOPS/W.
- OMNIVISION, Socionext: Maintain strategic footholds in imaging and custom solution SoCs for automotive and embedded markets where application-specific integration yields differentiated system outcomes.
Recent developments shaping 2026 strategies
- Major design houses preparing to adopt 2nm-class process nodes in 2026, accelerating the frontier of energy-efficient compute for flagship and premium segments.
- Awards and product demonstrations for real-time automotive microcontrollers and I/O interfaces point to near-term commercialization pathways for L3–L4 autonomous stacks.
- Standardization initiatives for chiplet interconnects and advanced packaging technologies (including high-yield interposers) are lowering integration costs and enabling new supplier roles.
- Policy moves—both incentives and export controls—continue to bifurcate global supply chains, making partner selection and intellectual-property strategy a core executive concern.
Practical strategic recommendations for 2026
- Adopt a portfolio timing approach: Stagger investments across monolithic advanced-node projects and packaged chiplet systems to capture near-term gains while retaining upgrade paths for next-node performance.
- Secure foundry commitments early: Locking capacity through strategic supply agreements or joint ventures reduces lead-time risk and provides leverage as node supply tightens.
- Prioritize packaging partnerships: Invest in advanced packaging capability either via partners or strategic minority stakes to obtain early access to CoWoS-like solutions and HBM integration.
- Design for modularity and standards: Embrace chiplet-friendly architectures and industry interconnect standards to shorten time-to-market and lower integration risk across product lines.
- Stress-test regulatory exposure: Map product roadmaps against export control regimes and subsidy conditions; create alternative sourcing and dual-supply routes for constrained inputs.
- Use value-based M&A: Target acquisitions that fill capability gaps (IP blocks, packaging expertise, or automotive-grade validation labs) and provide immediate go-to-market acceleration.
Risk outlook and mitigation
Primary risks for 2026 center on access to advanced process capacity, packaging lead times, and geopolitical/legal constraints on certain high-end manufacturing technologies. Secondary risks include software-hardware co-design talent shortages and fluctuating demand cycles across consumer and enterprise segments. Mitigation steps include multi-sourcing, strategic inventory policies for critical fab inputs, localized R&D investments supported by government incentives, and aggressive cross-training programs to build systems-level design teams.
Conclusion — how to use this preview
This preview synthesizes the directional insights and executive implications from our full Mp System On A Chip Market study. It is designed to orient boardrooms, product leaders, corporate development teams and procurement heads as they set 2026 priorities. For decision-makers who require the underlying region- and application-level breakouts, proprietary model tables, vendor scorecards, and the detailed scenario assumptions that drive our forecasts, the full report provides downloadable datasets and executable playbooks. Contact PW Consulting or visit our report page to access the complete datasets, vendor matrices and an executive briefing tailored to your organization’s strategy.
For detailed analysis of this topic, please visit the official page: Mp System On A Chip Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com