

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Automotive Ethernet Market Poised for a 19.5% CAGR Through 2032

Automotive Ethernet Market: Strategic Imperatives for 2026 — PW Consulting Intelligence Brief
As automotive OEMs and Tier‑1 suppliers transition toward software‑defined vehicles, Automotive Ethernet is no longer an optional enabler — it is the architecture. PW Consulting’s latest Automotive Ethernet Market study (base year 2025; historical coverage 2020–2025; forecast 2026–2032) synthesizes the macro trajectory, competitive dynamics, regulatory drivers and technology bottlenecks that will determine winners and losers through the next planning cycle. All figures are expressed in USD Million.
Automotive Ethernet Market
Market Snapshot: growth, scale and concentration
Our analysis shows the market accelerating from a modest base in the early 2020s to a pronounced expansion by 2025, reflecting increasing in‑vehicle bandwidth demands and zonal or centralized electrical/electronic architectures. The report quantifies a compound annual growth rate of 19.52% over the forecast horizon, underscoring a rapid scale‑up that reshapes supplier economics, supply chain risk profiles and platform strategies.
Automotive Ethernet Market
This growth is accompanied by moderate market concentration: the top three suppliers control a material share of market revenues, and the top five approach a dominant position. These concentration metrics indicate that while innovation remains distributed across a broad vendor ecosystem, strategic partnerships and qualification cycles are increasingly decisive — a dynamic that procurement and product planning teams must internalize for 2026 program decisions.
Automotive Ethernet Market
Why this matters for 2026 decision cycles
- Program sourcing windows are narrowing. With vehicle programs now specifying higher Ethernet port counts and multi‑gigabit links, qualification lead times for PHYs, switches and certified test tooling need to be locked in earlier in the development cycle. Delays in component qualification cascade into software validation and vehicle cybersecurity approval.
- Bandwidth economics change platform choices. Higher link speeds and centralized compute options create a tradeoff between copper PHY investments and optical or multi‑domain consolidation strategies. Total cost of ownership modeling must include not only BOM cost but qualification, serviceability and cybersecurity lifecycle costs.
- Standards and regulation are shifting the risk profile. New ISO and OPEN Alliance standards for high‑speed PHYs and multi‑drop topologies, together with regulatory mandates on in‑vehicle cybersecurity, are reshaping architecture requirements and supplier selection criteria for 2026 vehicle launches.
Actionable insights for executives (how to use this report)
- Procurement: prioritize multi‑supplier qualification pathways for critical PHYs and switches to mitigate single‑supplier risk while negotiating volume‑based terms for emerging high‑bandwidth products.
- Product Strategy: adopt a hybrid zonal/centralized architecture assessment framework that compares latency, wiring harness complexity and software update surfaces across candidate topologies.
- R&D Investment: accelerate signal‑processing capabilities for 10G and 1G PHYs and invest in deterministic switching and time‑sensitive networking stacks where ADAS and domain convergence are priorities.
- Safety & Cybersecurity: embed UN ECE R155 compliance and ISO 26262 considerations into early architecture tradeoffs; Ethernet design choices affect attack surfaces and safety partitioning.
- M&A & Partnerships: identify targets that complement platform roadmaps — for example, software stacks, diagnostic tooling or deterministic switch IP — rather than standalone PHY suppliers whose value can be squeezed by major semiconductor players.
Report contents — what PW Consulting delivers to your strategy team
The study blends quantitative forecasting with practical, executable deliverables designed for 2026 planning cycles:
- Proprietary demand model (2026–2032) calibrated to vehicle program timelines, port counts and migration curves for multi‑gigabit links.
- Scenario analysis that quantifies upside/downside across three adoption pathways (baseline, accelerated, conservative), enabling risk‑adjusted capital planning.
- Supplier scorecards and qualification matrices covering performance, cost, compliance footprint and ecosystem support (software, test tooling, reference designs).
- Architecture playbooks that translate standardization and regulatory drivers into actionable design patterns for OEMs and Tier‑1s (including harness topologies, zonal partitioning and gateway strategies).
- Procurement templates and negotiation levers tailored to the semiconductor and module lifecycle specificities of Automotive Ethernet components.
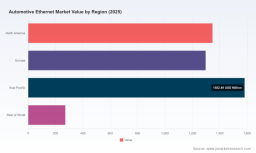
To preserve the competitive integrity of our clients and to encourage direct engagement with the full dataset, the report intentionally withholds granular regional and application‑level revenue splits in this release. The comprehensive tables, regional breakouts and application matrices are available in the full report.
Competitive landscape — who matters and why
Automotive Ethernet is now a multi‑layered ecosystem spanning PHY suppliers, switch vendors, SoC integrators, software and test tool providers. Our competitive assessment highlights different classes of players and practical implications for selection and alliance strategies:
- Tier‑A semiconductor platforms. Companies providing integrated MAC‑PHY solutions and SoCs play a critical role in enabling centralized compute architectures. Their roadmaps determine how quickly OEMs can consolidate domains and increase internal bandwidth demands.
- PHY and switch specialists. Established PHY providers continue to push the performance envelope (100BASE‑T1 through 10GBASE‑T1), and their compliance with OPEN Alliance and ISO standards materially reduces integration risk for OEMs.
- Deterministic networking innovators. Vendors focusing on time‑sensitive networking, hardware offload and deterministic switches are differentiators for ADAS and software‑defined vehicle use cases.
- Testing and diagnostics ecosystem. As link speeds increase, so do the demands on validation tooling and diagnostics. Providers of purpose‑built test hardware and software play an outsized role in reducing time‑to‑market.
Representative vendor profiles featured in the study include global semiconductor leaders delivering PHYs and integrated switches, specialist deterministic‑networking firms, and a cohort of tooling and validation vendors. Recent industry developments — such as major product launches, OPEN Alliance certifications and vehicle integrations announced in 2025 — are discussed in context to illustrate near‑term shifts in supplier viability and strategic fit.
Selected recent developments — implications for 2026
- OPEN Alliance compliance and certifications for higher‑speed PHY families materially shorten validation timelines for OEMs planning 2026 launches; certification news in late 2025 signals production readiness for certain 10G components.
- Vehicle integrations of 10G PHYs in high‑bandwidth platforms demonstrate the immediate ADAS use cases for multi‑gigabit links, and create pressure on suppliers to deliver scaled production and consistent test results.
- Joint development agreements between semiconductor vendors and automotive tier suppliers illustrate the strategic push toward combined silicon‑software solutions; such collaborations should be considered potential risks or opportunities depending on your supplier positioning.
Standards, regulation and technology bottlenecks
Regulatory and standards developments are not background noise — they are active drivers of architecture and procurement choices:
- ISO standards outlining high‑speed PHY requirements and OPEN Alliance specifications for multi‑drop and multi‑gigabit topologies directly influence supplier roadmaps and interoperability requirements.
- UN ECE R155 cybersecurity requirements have elevated the importance of secure boot, segmented communications and in‑vehicle intrusion detection — all of which are impacted by Ethernet topology choices.
- Technical bottlenecks remain, notably in mitigating electromagnetic interference for high‑density unshielded twisted pair deployments and in deploying reliable 1000BASE‑T1 implementations; overcoming these requires investments in signal processing, cable engineering and system‑level testing.
Practical recommendations for 2026 planning
- Start supplier qualification today for any program with expected MY2026 production start — assume multi‑vendor pathways for critical PHY and switch components.
- Embed standards and regulatory compliance checkpoints into architecture gates; certification status should be a weighted criterion in supplier selection.
- Invest in test tooling and signal integrity expertise to accelerate debug cycles for high‑speed links; validated diagnostics reduce program risk and warranty exposure.
- Design procurement contracts that reflect technology lifecycle acceleration — include clauses for roadmap access, compliance milestones and volume flexibility to accommodate shifting port counts.
How to access the full intelligence
This brief is a strategic preview. PW Consulting’s full Automotive Ethernet Market report includes the complete dataset, regional and application breakouts, supplier scorecards and the proprietary demand model used to generate the forecasts. Because granular segmentation and supplier revenue matrices are commercially sensitive and critical to program execution, they are intentionally excluded from this preview. For enterprise access, bespoke advisory sessions or licensing of our forecast model for internal scenario planning, please visit our report page or contact a PW Consulting industry analyst.
PW Consulting’s Automotive Ethernet Market study is designed to convert macro trends into operational decisions for 2026 program cycles. Whether you are an OEM architecting zonal ECUs, a Tier‑1 sizing harnesses, a semiconductor supplier plotting a roadmap, or an investor assessing consolidation targets, this analysis provides the framework to prioritize investments and to reduce execution risk in an era of rapid bandwidth adoption.
For detailed analysis of this topic, please visit the official page: Automotive Ethernet Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com