

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting: AC Power Source Market poised from USD 125.15M (2025) to USD 168.34M by 2032
By pmarketresearch, 2026-07-08
AC Power Source Market — 2026 Strategic Preview
As organizations recalibrate test laboratories, manufacturing floors, and product qualification roadmaps for the next wave of electrification and sustainability regulation, the AC power source market has quietly evolved into a strategic bellwether. PW Consulting’s latest market study (base year 2025; forecast period 2026–2032) synthesizes five years of historical performance and forward-looking scenarios to help executive teams convert uncertainty into decisive capital and R&D choices. The sector’s headline metrics set the frame: the total addressable market expanded from approximately USD 103.85 Million in 2020 to USD 125.15 Million in 2025, and our modeled trajectory reaches roughly USD 168.34 Million by 2032 guided by a 4.3% CAGR over the 2026–2032 forecast window.
AC Power Source Market
Why this report should shape your 2026 decisions
- Market maturity with differentiated pockets of growth. The market is past the startup scramble and now demonstrates sustainable, mid-single-digit growth. That dynamic favors incumbents with product breadth and newcomers that can capture niche technical requirements.
- Regulatory inflection points are immediate and material. Changes such as the California Energy Code update effective January 1, 2026, and the publication of ISO 14001:2026 in April 2026 introduce compliance and procurement pressures that will influence purchasing cycles, product design, and supplier qualification standards.
- Technology is shifting from pure supply to systems-level simulation. Buyers increasingly demand programmable, regenerative, and software-integrated sources capable of reproducing grid anomalies, enabling complex R&D workflows, and supporting energy recovery — transforming unit economics and total cost of test.
- Fragmentation persists; scale matters in services. Competitive concentration remains modest: top-three players account for roughly 18.5% of the market and top-five around 23.7%. This fragmentation creates opportunities for focused differentiation (e.g., verticalized solutions, software-as-a-service, extended warranties) rather than pure price plays.
- Procurement priorities are shifting to lifecycle and sustainability. New standards and corporate ESG commitments force buyers to weigh energy efficiency, recyclability, and scope-3 impacts alongside traditional performance metrics when selecting AC power sources.
What PW Consulting’s AC Power Source Market study delivers
- Executive synthesis that translates raw market movement into board-level options: build, buy, partner, or defer.
- Rigorous market sizing & forecast built from a 2020–2025 historical base and extended into 2026–2032 with scenario variance around a 4.3% CAGR for the forecast window.
- Demand-driver decomposition that connects macro trends (electrification, regulatory shifts, semiconductor cycles) to unit demand and pricing pressure.
- Technology and product landscape comparing linear, PWM, regenerative, and software-enabled platforms, with an assessment of lifecycle cost and test fidelity trade-offs.
- Commercial playbooks for OEMs, test labs, and distributors — including channel strategies, aftermarket services, and warranty models proven to protect margin in a fragmented market.
- Supplier scorecards and capability matrices synthesizing product breadth, geographic reach, service footprint, and R&D posture into actionable shortlists for procurement and M&A due diligence.
- Scenario planning and stress testing — three discrete market paths tied to regulation, technology adoption, and macroeconomic shocks, each with financial impact models for product and service lines.
- Primary research validation derived from interviews with manufacturers, test labs, distributors, and regulatory bodies, supplemented by proprietary shipment and pricing runs.
- Appendices and tools — data annex, assumptions log, and model files for clients to run bespoke sensitivity analyses.
Competitive landscape — strategic reading of the vendor field
The supplier ecosystem is populated by a mix of long-established test-and-measurement firms, specialized power-electronics vendors, and lean regional players. PW Consulting’s competitive mapping highlights both capability overlap and areas of genuine differentiation that buyers and investors must prioritize.
AC Power Source Market
- Keysight Technologies Inc. (Santa Rosa, CA). A mainstream supplier to test-and-measurement customers with programmable AC platforms (e.g., AC6800 family). Keysight’s strength is in instrumentation integration, software robustness, and a customer base that values traceability — a strategic advantage for customers with complex validation requirements.
- Chroma ATE Inc. (Taoyuan City, Taiwan). Known for simulating mains and line-fault conditions across a broad power envelope. Chroma’s portfolio and global channel relationships make it a strong contender for manufacturers seeking high-fidelity grid emulation at scale.
- AMETEK Programmable Power, Inc. (Berwyn, PA). Focused on regenerative grid simulators and high-reliability industrial offerings. AMETEK is positioned where durability and energy recovery economics matter most — industrial test labs, automotive powertrain validation, and compliance testing environments.
- B&K Precision Corporation (Irvine, CA). Addresses educational, service, and light-manufacturing uses with practical, cost-optimized platforms. Their commercial strategy emphasizes price-performance for customers with less complex simulation needs.
- Kikusui Electronics Corporation (Tokyo, Japan). Offers laboratory- and industrial-grade programmable AC supplies. Kikusui’s strengths are product reliability and service networks in markets where long-term instrument lifespan is a procurement priority.
- Regatron AG (Werdenberg, Switzerland). A specialist in programmable DC and AC power supplies with a reputation for high-performance systems used in research and industrial applications; strong on custom engineering and system integration.
- NF Corporation (Shinagawa, Japan). A provider of precise AC sources for specialized testing and simulation; often chosen for high-accuracy measurement and mission-critical applications.
Recent vendor activity also signals momentum from smaller innovators: for example, Preen Power’s 2025 AFV-P series launch and international trade show participation highlight how niche entrants are advancing power density and feature sets. Taken together, the competitive picture suggests buyers will need multi-criteria procurement frameworks — balancing cost, test fidelity, energy efficiency, and supplier support — rather than single-metric selection.
AC Power Source Market
Regulatory and operational dynamics to watch
- California Energy Code (2025 update, effective Jan 1, 2026) will reframe building-level energy performance requirements and, by extension, change specification and procurement cycles for lab and facility-grade test equipment.
- ISO 14001:2026 (published April 2026) tightens expectations for environmental management systems; manufacturers and large buyers will need documented roadmaps to transition by the new deadlines, impacting supplier selection and qualification timelines.
- ISO 9001:2026 was in draft development as of March 2026 — watch for quality-management updates that could alter supplier audit protocols and contract terms.
Strategic playbook for 2026 — five practical moves
- Adopt a two-speed procurement approach. Fast-track purchases where test needs are tactical and standardized; reserve extended RFPs for investments where regenerative capabilities, software integration, and lifecycle costs will be determinative.
- Invest in modularity over monoliths. Modular hardware and software architectures preserve upgrade paths (e.g., adding regenerative modules or enhanced measurement stacks) and reduce future capital write-offs.
- Prioritize suppliers with services and software roadmaps. Warranties, calibration networks, remote diagnostics, and firmware ecosystems materially affect total cost of ownership and uptime for high-utilization labs.
- Embed regulatory compliance into specifications. Make energy and lifecycle metrics mandatory line items in RFPs to avoid late-stage non-compliance and to capture long-term operational savings.
- Use scenario-finance for capex approvals. Require finance committees to review at least three demand scenarios with sensitivity to regulatory timing and technology adoption before greenlighting significant acquisitions.
What you’ll only get in the full PW Consulting study
- Granular segment forecasts by region, product type, and end-application with supply/demand balances and pricing curve models (note: this granular breakdown is intentionally withheld here to preserve the report’s proprietary value).
- Supplier scorecards with quantified capability scores, service footprints, and a shortlist for rapid RFP issuance.
- Interactive model files enabling clients to re-run forecasts using alternative macro paths and internal assumptions.
- Detailed annexes documenting primary interview transcripts, data sources, and the assumptions log that underpins our 4.3% CFR growth forecast for 2026–2032.
For leadership teams planning capital allocation, product roadmaps, or M&A strategies in 2026, the choices you make now will determine not just next year’s test capacity but your organization’s ability to meet evolving compliance and sustainability requirements. PW Consulting’s AC Power Source Market study is designed to convert that strategic ambiguity into a prioritized set of investment hypotheses backed by quantitative modeling and supplier intelligence.
To review the full dataset, supplier matrices, and scenario models — and to obtain an executive briefing tailored to your organization’s specific exposure and opportunity — download the complete report or contact our market specialists at PW Consulting. The report’s depth is structured to support immediate decision-making and to be a living asset for continuous planning through 2032.
For detailed analysis of this topic, please visit the official page: AC Power Source Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Horticultural LED Lighting Market to Reach USD 435.5M by 2032 (16.5% CAGR)
By pmarketresearch, 2026-07-08
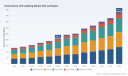
Horticultural LED Lighting Market: Strategic Preview for 2026 Decision-Makers
Executive snapshot
The global horticultural LED lighting market is on a sustained growth arc that will materially reshape capital allocation, product roadmaps, and channel strategies across the controlled-environment agriculture ecosystem. PW Consulting’s new study, built on a 2025 base year with historical coverage from 2020–2025 and forward-looking forecasts through 2032, quantifies that progression: the market expanded from USD 133.5 million in 2020 to USD 212.5 million in 2025 and is forecast to approach USD 435.5 million by 2032—an implied compound annual growth rate of 16.5% from the base year. This preview explains why that trajectory matters for management teams preparing budgets, product launches, and strategic partnerships in 2026.
Horticultural LED Lighting Market
Why 2026 is a critical inflection point
Three converging forces make 2026 a decision-rich year for horticultural-lighting stakeholders. First, the maturity of LED component technology and control electronics has compressed the performance delta between premium and mainstream offerings, shifting competition from LED efficacy alone to systems-level differentiation (controls, integration, thermal management, and lifecycle services). Second, tightening technical requirements from standards bodies and qualification programs are accelerating product refresh cycles and creating near-term compliance costs for vendors and specifiers. Third, farm-level economics—driven by energy prices, labor dynamics, and the economics of vertical/indoor models—are pushing buyers to demand verifiable total-cost-of-ownership (TCO) outcomes rather than headline efficacy numbers.
Horticultural LED Lighting Market
Key strategic implications for executives
-
Prioritize compliance-driven product roadmaps. Regulatory and qualification shifts are not theoretical: the DesignLights Consortium (DLC) implemented Hort Version 4.0 technical requirements in April 2025 and opened an application window for product updates. Vendors that front-load testing and certification updates will avoid disruptive delisting risk and gain procurement advantage where DLC/QPL listings are procurement preconditions.
Horticultural LED Lighting Market -
Reframe value propositions around system-level returns. As efficacy improvements level off, buyers care more about integration (spectrum control, zoning, sensors), operations (heat recovery and energy optimization), and service (predictive maintenance and warranties). Product teams should shift investment toward software-enabled features, heat-management innovations, and financing-backed TCO offers.
-
Lock in channel and service partnerships early. Installers, integrators, and lighting-as-a-service (LaaS) partners will be decisive in 2026 as commercial growers scale trials to production. Companies that secure preferred channel relationships and align incentives across installation, monitoring, and retrofit services will capture outsized share during the next growth phase.
-
Embed testable ROI into every commercial offer. Sales organizations must present scenario-based ROI analytics that account for crop mix, hours of operation, energy tariffs, and maintenance schedules. Procurement teams will start demanding vendor-provided payback guarantees or performance-linked contracts.
Market structure and concentration — what the numbers mean
The horticultural LED lighting market remains structurally fragmented: the combined share of the three largest firms sits in the mid-twenties percentile range, with the top five not much higher. That dispersion means winners will be determined by execution agility—speed of certification, channel reach, and demonstrable ROI—rather than by sheer scale alone. For corporate strategists, fragmentation implies abundant M&A runway and the possibility of bolt-on acquisitions to accelerate capability stacks (controls, sensors, water-cooling, or service platforms).
Regulatory and standards dynamics
Standards activity in 2024–2025 materially raises the bar for horticultural lighting. The DLC’s Hort QPL (as of early 2025) listed more than 1,200 products from over 130 manufacturers, and the average efficacy of listed products has risen nearly 25% since the program started in 2018. Hort V4.0, which took effect in April 2025, increases minimum photosynthetic photon efficacy thresholds—creating near-term technical refresh and testing costs but longer-term benefits for growers through improved energy efficiency. These dynamics reshape procurement checklists and create a first-mover advantage for vendors that can convert compliance into commercial differentiation.
Competitive landscape — positioning and playbook
Our assessment of core incumbents and scale challengers reveals a spectrum of winning plays. Below are strategic characterizations—useful for benchmarking and framing partnership or acquisition targets:
-
Acuity Brands (Atlanta) — leverages strong channel relationships and a breadth of professional-grade fixtures under recognized brand architecture. Strength: channel reach and specification-level trust. Recommendation: emphasize system integration and retrofit services to extend enterprise contracts.
-
Philips (Amsterdam) — combines global distribution with integrated control systems (GrowWise). Strength: end-to-end solutions for greenhouse operators. Recommendation: accelerate software monetization and demonstrate differentiation through crop-specific case studies.
-
Horticulture Lighting Group (Canada) — targets premium indoor and hobbyist segments with a strong product focus. Strength: reputation in high-performance fixed fixtures. Recommendation: broaden service offerings for commercial customers to move upmarket.
-
Lumileds and ams OSRAM — component-level specialists providing LED dies, optics, and sensors. Strength: control over core semi components. Recommendation: monetize spectrum IP through co-development agreements and tiered supply contracts.
-
P.L. Light Systems and Fluence — focus on commercial lighting systems with integrated controls. Strength: systems expertise and channel credibility. Recommendation: pursue financing partnerships to underwrite customer conversions at scale.
-
Valoya , Heliospectra , and Agnetix — niche innovators in spectrum tuning, software control, and thermally managed fixtures. Strength: IP-rich product platforms. Recommendation: seek defense partnerships or bolt-on sales channels to scale customer acquisition.
-
Samsung LED and Cree — leverage brand and manufacturing scale to offer full-spectrum plant-centric LEDs. Strength: manufacturing cost advantage and component breadth. Recommendation: differentiate through service-level guarantees and integrated crop-optimization solutions.
-
TCP — science-backed fixtures targeting taller plant profiles. Strength: product engineering tuned to specific crop architectures. Recommendation: codify vertical-market plays to accelerate specification in target crop categories.
Practical contents of the PW Consulting report (what you will get)
The full PW Consulting study is intentionally operational. It is designed for strategy teams, product leaders, and corporate development officers who need to translate market momentum into executable plans for 2026 and beyond. Key deliverables include:
- Granular market sizing and validated growth drivers by segment and application (methodology and data tables provided in downloadable format).
- Scenario-based forecasts (baseline, upside, and downside) through 2032 with sensitivity to energy pricing, adoption curves, and standards timelines.
- Technology matrix mapping fixture types, control architectures, thermal management approaches, and spectrum strategies—scored by maturity and commercial readiness.
- Certification and compliance playbook aligned to DLC Hort V4.0 and major regional standards, including test-plan templates and an estimated update timeline.
- Buyer persona and procurement decision-tree models for commercial growers, vertical farms, and retrofit projects—complete with negotiation levers and TCO calculators.
- Competitive benchmarking with vendor scorecards, go-to-market moves, and M&A heatmaps highlighting likely consolidation targets and candidate capabilities for bolt-ons.
- Commercial templates: ROI decks, pilot-to-scale playbooks, channel incentive structures, and sample service-level agreements for lighting-as-a-service pilots.
- Executive roadmaps for product, sales, and corporate development through 2028—prioritized by expected ROI and risk exposure.
Actionable go-to-market recommendations for 2026
- Deploy a compliance-first product refresh schedule tied to DLC application windows; treat certification as a competitive moat.
- Offer performance-linked commercial contracts (short-term pilots with measurables, then scaled LaaS agreements) to reduce buyer friction and accelerate adoption.
- Form supply or co-development partnerships with component suppliers to secure access to high-efficacy LED dies and spectrum IP.
- Invest in field data platforms that convert sensor and control telemetry into repeatable crop-specific ROI narratives.
- Use targeted M&A to acquire control-software, thermal-recovery technologies, or local installation networks—focusing on fast integration and value capture.
Conclusion — what to prioritize now
For leadership teams making 2026 capital and product decisions, the immediate imperative is twofold: mitigate compliance risk through an actionable certification plan, and accelerate the shift from product-led to system-led commercial models that deliver verifiable TCO improvements. The market’s robust CAGR and near-term doubling trajectory to 2032 underscore a substantial runway—but capturing premium value will depend on execution of the integration, service, and channel plays described above.
Next steps
PW Consulting’s full report contains the segment-level breakouts, scenario Excel models, and vendor scorecards necessary to operationalize 2026 plans. This preview intentionally highlights strategic direction while reserving the detailed segment and financial tables for the full study. Contact PW Consulting or visit our report page to access the complete analysis and downloadable tools that will support board-level decision-making and commercial execution for 2026.
For detailed analysis of this topic, please visit the official page: Horticultural LED Lighting Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Omega-3 Market 2026: Strategic Outlook and Decision Playbook
As PW Consulting’s Senior Strategic Advisor and Chief Industry Analyst, I present a concise, action-oriented preview of our full Omega-3 Market research suite. Anchored on a base year of 2025 and a detailed forecast through 2032, the study synthesizes quantitative market modeling with repeatable commercial playbooks to inform high-stakes choices in 2026. At the macro level, the market has expanded from roughly USD 2.28 billion in 2020 to about USD 3.21 billion in 2025, and our forward view projects steady growth at a compound annual growth rate (CAGR) of 7.1% across the 2026–2032 forecast window, with the global market approaching the mid-single-digit billion-dollar range by 2032. This preview explains why that trajectory matters for your strategic planning — and what we deliberately withhold here to draw decision-makers to the full intelligence package.
Omega-3 Market
Why this research matters for 2026 decision-makers
- Timing and scale: The market is on a multi-year growth path with predictable expansion drivers. Executives who align capex, sourcing, and go-to-market plans to the 2026 inflection points reduce execution risk and capture premium margin pools.
- Supply and substitution dynamics: Disruptions to marine supply chains and accelerating algal innovation create both near-term procurement risk and long-term opportunity for product differentiation.
- Regulatory sensitivity: Prescription-level approvals and label revisions have outsized downstream effects on perception, reimbursement, and clinical partnerships — especially for players bridging pharma and nutraceutical channels.
- M&A and partnership clarity: The market’s evolution favors early moves on vertical integration, secure supply, and ingredient innovation; our study isolates the most attractive transaction archetypes for 2026.
What the full report delivers (practical, transaction-ready content)
Beyond market sizing and high-level trend narratives, the PW Consulting report is designed as an executable toolkit for boards, corporate development teams, and commercial leaders. Key deliverables include:
Omega-3 Market
- Proprietary market model (Excel): scenario-enabled forecasts, sensitivity levers for pricing vs. volume, and bottom-up demand drivers by product archetype and channel.
- Supply-chain mapping and risk heatmap: origin analysis, concentration hotspots, seasonal and climate-linked vulnerability points, and mitigation levers for each supply node.
- Commercial playbooks: three GTM options tailored to branded supplement players, ingredient suppliers, and pharmaceutical incumbents — including margin profiles, channel economics, and minimum DIO/working capital requirements.
- Regulatory radar and clinical impact matrix: timelines for label & approval changes, recall/resolution playbooks, and stakeholder engagement frameworks for regulatory affairs and HEOR teams.
- Target screening & due diligence templates: candidate selection criteria for bolt-on acquisitions, JV scorecards, and earnout/contingent-valuation constructs.
- Product innovation and formulation roadmaps: prioritized technology bets (e.g., algal TG concentrates, encapsulation innovations) and practical supplier-partnership approaches to shorten commercialization timelines.
Market dynamics and strategic implications
The 2024–2026 period has been a crucible for the omega-3 value chain. Climatic events and quota adjustments materially reduced near-term marine-derived availability, creating price volatility and forcing buyers and processors to re-evaluate sourcing strategies. The partial recovery observed into 2025 has not erased the structural change: buyers now consider diversified raw-material sourcing and vertical contracts as baseline risk management.
Omega-3 Market
Concurrently, algal and fermentation-derived omega-3 solutions have crossed important technical thresholds — potency, cost per EPA/DHA, and supply scalability — making them credible alternatives in higher-margin nutraceutical and pharmaceutical adjacencies. That trend was underscored by product launches in early 2026 targeting high-potency vegan ingredients, signaling that innovation-led entrants will increasingly compete on sustainability and label positioning rather than price alone.
Regulatory developments also shape strategic calculus. Prescription omega-3s continue to be an arena of active labeling and licensing activity; recent FDA label refinements and ongoing licensing expansions in 2026 demonstrate how clinical evidence and approvals materially reshape market access and formulary considerations. At the same time, isolated manufacturing recalls in 2026 highlight the reputational and operational knock-on effects that can temporarily depress demand for certain industrial channels.
Competitive landscape — who matters and what to watch
The competitive set spans specialized marine ingredient harvesters and processors, established branded supplement manufacturers, large chemical and life-science suppliers, and clinical-stage pharma companies. Each archetype requires a distinct strategic play:
- Aker Biomarine (Oslo): a vertically integrated marine ingredient player with a strong position in krill and fish oil supply. Key strengths: supply-chain control, sustainability certification expertise, and partner-friendly commercial models. Strategic risk: exposure to marine catch volatility.
- GC Rieber VivoMega (Kristiansund): recently pivoting into high-potency algal ingredient launches aimed at premium vegan nutraceuticals. Strengths include R&D momentum and positioning around sustainability-driven differentiation; watch their scale-up timelines and cost-in-use metrics.
- Nordic Naturals (Watsonville): a consumer-facing leader driving branded premiumization and channel penetration. Their playbook centers on product development, direct-to-consumer marketing, and retail partnerships — an attractive counterparty for ingredient suppliers seeking stable offtake.
- BASF (Ludwigshafen): a broad-based supplier whose expertise in APIs and formulation support presents a strategic option for large pharma and CPG partners seeking regulatory-grade inputs and global distribution muscle.
- Amarin (Bridgewater): the prescription omega-3 incumbent whose licensing and market-access moves materially influence clinical adoption and perception across both prescription and over-the-counter segments. Recent licensing expansions underscore the role of clinical evidence as a market-shaping asset.
- KD Pharma Group (Switzerland/UK): scaling through strategic acquisitions and API consolidation; a key supplier to both pharmaceutical and nutraceutical manufacturers. Their moves reflect industry consolidation and are worth watching for supply security implications.
Scenarios for 2026–2032 (and tactical triggers)
- Baseline (most likely): Continuation of the current trajectory with the market expanding at roughly a mid-single-digit CAGR (7.1% in our central forecast). Strategic implication: optimize pricing architecture and secure multi-year supply contracts while pursuing high-margin product extensions.
- Supply-constrained premiumization: Prolonged marine supply tightness drives premium pricing and faster conversion to algal or fermentation substitutes for premium SKUs. Tactical moves: accelerate vertical integration, invest in captive algal capacity, and prioritize supplier diversification.
- Rapid algal adoption: Breakthroughs in cost-to-potency for algal oils create an accelerated shift in ingredient mix, favoring innovators and formulation specialists. Recommended actions: pursue licensing/joint development agreements with algal specialists, co-develop label claims, and sequence launches to capture early-adopter health-conscious consumers.
90-day executive playbook: actions that produce measurable outcomes
- Conduct a supply-security audit: map single-source dependencies, quantify one-year and three-year exposure, and execute conditional purchase agreements for at least 50–70% of near-term needs (tailor percentage to risk appetite).
- Initiate two strategic supplier conversations: one with a marine-integrated supplier for preferential terms and one with an algal/fermentation innovator to pilot alternative formulations.
- Fast-track a regulatory & clinical risk review: prioritize those SKUs with label sensitivity and set a timeline for HEOR studies or real-world evidence collection where required.
- Define M&A scouting criteria: target size, integration complexity, and time-to-revenue metrics for bolt-on producers or formulation specialists that would materially improve margin or secure supply.
- Refine commercial segmentation: shift marketing investment toward proof-driven, clinically-differentiated SKUs and e-commerce channels that have shown higher elasticity and lifetime value.
Closing: what you gain from the full PW Consulting study
This preview captures the contours of the opportunity and the near-term hazards. The full PW Consulting Omega-3 Market report converts these insights into executable outputs: granular regional and application splits, supplier scorecards, transaction-ready valuation ranges, downloadable financial models, and a prioritized list of 10 acquisition/joint-venture targets mapped to five investment theses. We intentionally withhold those detailed segment tables and target-level analytics here to ensure senior decision-makers engage with the complete intelligence package and the associated client advisory programming.
For boards, corporate development teams, and commercial leaders preparing budgets and capital allocation plans for 2026, this study is the difference between reactive scrambling and proactive capture. Contact PW Consulting to access the full market model, supplier diligence templates, and the tailored 12–18 month implementation plan that aligns with your risk profile and strategic ambition.
For detailed analysis of this topic, please visit the official page: Omega-3 Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Automotive Seat Heater Market to Reach USD 4,557.6M by 2032 at 6.6% CAGR
By pmarketresearch, 2026-07-08
Automotive Seat Heater Market — Strategic Primer for 2026 Decision Makers
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present this concise yet insight-rich primer to orient executive teams, product leaders, and corporate strategists ahead of the critical planning cycle in 2026. This piece synthesizes the market trajectory, competitive dynamics, regulatory and technology pressures, and the practical decision levers that will determine success over the 2026–2032 forecast window. It intentionally showcases analytical depth while preserving the granular segmentation and scenario tables that comprise the full advisory—those assets remain available in the full report for teams that require executable, model-backed intelligence.
Automotive Seat Heater Market
Market at a glance: growth profile and recent rhythm
The automotive seat heater market enters 2026 from a position of steady recovery and structural opportunity. Using 2025 as the base year, the market is approaching a multi-year expansion path driven by broader vehicle feature penetration, cabin thermal comfort expectations in electrified vehicles, and materials/architecture shifts among suppliers and OEMs. Our macro forecast projects a compound annual growth rate (CAGR) of 6.6% through 2032, taking the market from the 2025 baseline into materially higher absolute levels by the end of the forecast window.
Automotive Seat Heater Market
Historical dynamics since 2020 show a market that absorbed macroeconomic volatility while retaining a long-term positive trend in unit and content-per-vehicle adoption. That resilience—coupled with a predictable upgrade cycle tied to vehicle refreshes and rising expectations for thermal comfort in electrified platforms—creates a clear, investable runway for suppliers and OEMs willing to align technology, cost, and compliance strategies.
Automotive Seat Heater Market
Why this report matters to 2026 strategy
- Capital allocation and foot-printing: The market’s growth profile requires firms to decide where to place manufacturing capacity, invest in automation for thin-film and carbon-based heating elements, or opt for contract manufacturing. Timing these investments will materially affect cost position in the 2027–2030 window.
- Technology bets: Suppliers face a binary choice in some product lines—double down on tried-and-tested resistance wire approaches or accelerate migration to carbon-based, sheet, and zonal heating technologies that favor energy efficiency and packaging integration for EV cabins.
- OEM sourcing and supplier tiers: Procurement teams need a clear rubric for evaluating incumbent versus emergent suppliers across quality, homologation time, total cost of ownership (TCO), and co-development capability for seat-integrated thermal systems.
- Regulatory and safety compliance: Evolving Western European and global safety standards mandate additional testing and product design investments; failure to pre-emptively operationalize compliance can derail product launches and create warranty exposure.
Technology and regulation: twin forces reshaping product roadmaps
Two forces are accelerating structural change. First, material and architecture innovation—driven by lighter, lower-power heating solutions and improved thermal management—has become a primary differentiator. Leading OEMs are specifying lower-voltage, faster warm-up, and zoned heating systems that integrate with seat ventilation, occupant sensors, and body control modules. Second, regulatory scrutiny—particularly in Western Europe—has raised the bar for safety testing, electrical fault tolerance, and long-term durability. Meeting these standards is non-negotiable and increasingly requires documented R&D investment, compliance testing, and traceable quality systems.
For suppliers, the implication is clear: product roadmaps must prioritize energy efficiency, fail-safe electrical protection, and testable durability to pass both OEM requirements and third-party homologation. For OEMs, specifying future-proof interfaces and software hooks for thermal control allows greater differentiation in user experience without repeated hardware redesigns.
Competitive landscape — strategic positioning of key players
The market structure today is characterized by a mix of global Tier-1 integrators, component specialists, and regional players operating across both OEM and aftermarket channels. Market concentration is moderate: the top three suppliers do not control an overwhelming share, with the top five collectively forming a meaningful but not dominant bloc—this creates space for both consolidation and niche leadership. Competitive dynamics split along capability clusters: full-seat integrators, heating-element specialists, and cost-competitive regional manufacturers.
- Gentherm Incorporated (Ann Arbor, MI): A technology-led player with a broad product portfolio including wire, carbon fiber, over-sewable and zonal heating solutions. Their CCS® Heat systems and focus on energy-efficient integration position them strongly for OEM programs that value modularity and advanced thermal management.
- Lear Corporation (Southfield, MI): An integrated seating systems leader that embeds thermal functions into full seat assemblies. Lear’s advantage lies in seat-level integration, scale, and OEM relationships—important where seat architecture decisions are centralized with the vehicle OEM.
- Panasonic Corporation (Kadoma, Osaka): Brings cross-domain electronics and automotive interior expertise. Panasonic’s strength is system-level integration and the ability to fold seat heating into broader cabin electronics packages.
- W.E.T. Automotive Systems AG (Oberderdingen, Germany): Specializes in conductive sheet-type heating elements; a strong fit for OEMs seeking thin, uniform heating panels and compact integration.
- Regional and aftermarket players (multiple headquartered in China and the USA): A cohort of agile manufacturers focus on standard and carbon variants for both OEM and aftermarket segments. These firms often compete on cost, rapid time-to-market, or specialized customer solutions (e.g., retrofits, model-specific kits).
Collectively, this competitive set creates multiple strategic entry points: partners for system integration, acquisition targets for technology access, and potential disruptors in low-cost, high-volume supply corridors.
What the full PW Consulting report delivers — practical, actionable, and implementable
The full market research report transcends conventional market-size narratives and delivers playbooks and decision tools firms need to act in 2026:
- Bottom-up and top-down forecast models with scenario sensitivity (base, accelerated adoption, and downside); note that the full report contains granular segmentation and regional breakdowns reserved for subscribers.
- Decision frameworks for make vs. buy, including a supplier selection matrix weighted for homologation lead time, TCO, and quality risk.
- Product roadmap templates aligning heating technology choices to vehicle architecture (ICE, hybrid, BEV) and cabin energy budgets.
- Regulatory compliance checklists and test-plan blueprints tailored to major markets—highlighting test-cases that commonly extend launch cycles if unaddressed early.
- Commercial models: pricing elasticity tables, margin impact of material substitution, and go-to-market playbooks for OEM vs aftermarket channels.
- Targeted M&A screening criteria and an anonymized shortlist of potential acquisition candidates aligned to different strategic objectives (technology access, capacity, geographic coverage).
Recommended 90/180/360 day roadmap for 2026
- 0–90 days: Conduct a gap analysis of current product portfolio vs. energy-efficiency and safety requirements; initiate prioritized supplier dialogues for carbon-based and sheet-heating options; secure homologation test slots for any upcoming platform launches.
- 90–180 days: Pilot a cross-functional seat-thermal integration lab with one OEM program or an internal platform; finalize sourcing decisions for critical components; lock negotiation parameters for 2027 volumes.
- 180–360 days: Scale manufacturing capability (in-house or via partner); deploy field trials focused on thermal comfort and durability; finalize any strategic acquisitions or joint ventures to fill capability gaps identified in the first half of the year.
Risks, signals, and triggers to monitor
- Regulatory tightening: New test standards or extended durability specs can materially affect lead times and cost—monitor Western Europe and principal OEM markets closely.
- Material supply shocks: Rapid moves toward carbon-based heaters increase demand for specialty conductive textiles and adhesives; supply-chain resilience must be stress-tested.
- OEM specification shifts: If major OEMs consolidate thermal-control functionality at seat-platform level, advantage will accrue to integrated seating suppliers; conversely, modular interface standards would favor heating-element specialists.
- Aftermarket growth dynamics: A healthy aftermarket can erode OEM pricing leverage or create parallel growth opportunities—strategies should cover both channels.
Closing — the strategic value of this intelligence for 2026
For executives making allocation, sourcing, or M&A decisions in 2026, the essential value lies not only in recognizing that the automotive seat heater market is growing at a mid-single-digit CAGR over the 2026–2032 period, but in understanding the interplay between technology choice, regulatory expectation, competitive posture, and operational readiness. The right combination of targeted R&D, supplier alignment, and compliant product engineering will determine which firms convert favorable market growth into sustained margin expansion and strategic positioning.
To move from insight to action, PW Consulting’s full report contains the granular segmentation, scenario spreadsheets, supplier scorecards, and test-plan templates required to operationalize these recommendations. Access the comprehensive intelligence and downloadable toolkits on the PW Consulting report page to obtain the underlying models, detailed regional and application breakdowns, and company-specific playbooks reserved for report subscribers.
For detailed analysis of this topic, please visit the official page: Automotive Seat Heater Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Automotive Clutch Market to Reach USD 19.1 Billion by 2032 at 4.8% CAGR
By pmarketresearch, 2026-07-08
Automotive Clutch Market — Strategic Briefing for 2026 Decision-Makers
As PW Consulting’s lead industry analyst, I present a concise strategic primer to frame executive decisions on clutches and related drivetrain components in 2026. Drawing on our new market study (base year 2025; historical series 2020–2025; forecast horizon 2026–2032), this briefing synthesizes the macro trajectory, competitive dynamics, and executive implications you need to prioritize capital, product, and go‑to‑market choices this year — while preserving the report’s proprietary segment detail for subscribers.
Automotive Clutch Market
Market trajectory at a glance
The global automotive clutch market has moved from an estimated USD 10.3 billion in 2020 to USD 13.5 billion in 2025, reflecting a recovery and structural growth driven by vehicle production normalization, rising commercial vehicle activity in select markets, and expanded remanufacturing and aftermarket demand. Our forecast projects continued expansion through 2032, reaching approximately USD 19.1 billion, with an underlying compound annual growth rate (CAGR) of 4.8% for the 2026–2032 forecast window. The 2026 near‑term projection of about USD 14.45 billion marks the start of the next multi‑year growth phase embedded in our scenario sets.
Automotive Clutch Market
Two points matter for 2026 planning: first, growth is positive and persistent but not exponential — the market rewards disciplined product and cost positioning rather than broad, unfocused expansion. Second, concentration is material: the leading three players account for a sizeable majority of OEM volumes (CR3 ~65%), and the top five firms push that concentration higher (CR5 ~75%). This structure amplifies scale advantages for integrated suppliers and creates attractive niches for focused specialists and aftermarket innovators.
Automotive Clutch Market
Key dynamics shaping 2026 decisions
-
Supply‑chain and trade friction: Recent trade policy shifts and tariff adjustments have increased headwind risk for cross‑border part flows. Coupled with rules of origin requirements under North American trade arrangements, sourcing strategies that rely on long, tariff‑exposed value chains will face margin erosion unless actively managed.
-
Raw material volatility: Steel and aluminum price and availability remain the most direct input risks for clutch manufacturers. Firms with secured multi‑tier contracts or hedging strategies will preserve margins; those without should expect procurement cost leakage.
-
Electrification and platform change: Battery electric vehicle (BEV) penetration changes the functional role and volume profile for clutches in certain applications, while hybrids and commercial drivetrains sustain demand. The result is a bifurcated product roadmap requirement: highly engineered solutions for hybrid/custom powertrains alongside cost‑competitive suites for traditional ICE and commercial fleets.
-
Aftermarket and remanufacturing momentum: Remanufactured clutch programs — validated by recent industry awards and OEM acceptance — are creating higher margin aftermarket revenue pools. Capturing these requires reverse logistics, quality traceability, and targeted channel partnerships.
Strategic implications for 2026
-
Portfolio prioritization: Segment product R&D into three investment tracks — (1) high‑value solutions for hybrids/commercial powertrains; (2) cost‑engineered platforms for price‑sensitive OEMs; and (3) aftermarket/remanufacturing channels. Allocate incremental R&D and capex to the first and third tracks where differentiated margin returns are clearest.
-
Regional footprint logic: Use a trade‑aware footprint strategy that balances proximity to OEM hubs with tariff exposure mitigation. Tactical local content strategies (including JV or licensing structures) will be decisive in preserving access to North American and Latin American programs subject to rules of origin.
-
Supply resilience and procurement: Move from transactional buying toward integrated supplier partnerships for critical metallic inputs. Implement multi‑sourcing plus strategic buffer inventories and renegotiated contractual terms to de‑risk input price volatility.
-
M&A and alliances: With concentration high among top suppliers, the most accretive deals in 2026 are either (a) bolt‑on acquisitions that add aftermarket/reman capabilities, or (b) geographic expansions into high‑growth commercial vehicle markets via local manufacturing or alliance structures.
-
Commercial model innovation: Introduce lifecycle pricing for remanufactured programs and explore subscription models for high‑usage commercial fleets to convert one‑time sales into recurring revenue streams.
What PW Consulting’s full report delivers (practical highlights)
-
Proprietary forecast model (2026–2032) calibrated to macro scenarios — includes baseline, upside, and downside demand paths, and stress testing for tariffs and material shocks.
-
Actionable segmentation analytics — a drillable framework across region, product type, and application that identifies where margins, volume growth, and aftermarket opportunity intersect. Note: detailed segment breakouts are available only in the full report to protect intellectual property and client value.
-
Supplier risk and opportunity matrix — supplier scores for scale, geographic exposure, technology breadth, and aftermarket reach that guide sourcing and partnership decisions.
-
Competitive playbooks — tailored strategies for market leaders, challengers, and niche specialists, including go‑to‑market moves, product roadmaps, and M&A priorities.
-
Deal tracker and program pipeline — verified contract awards, program start‑of‑production (SOP) timelines, and capex footprints to help you time investments and capacity commitments.
Competitive landscape — what to watch in 2026
The ecosystem is led by established global suppliers that combine scale manufacturing, integrated drivetrain portfolios, and OEM relationships. Key firms profiled in our study include Schaeffler Group (Germany), Valeo SE (France), ZF Friedrichshafen AG (Germany), BorgWarner Inc. (USA), Eagle Industry (Japan), Amsted Automotive Group (USA), and Eaton Corporation (Ireland). Each brings a distinct strategic posture and regional focus that shapes competitive openings.
-
BorgWarner: Rapid program wins and footprint expansion in China underscore an aggressive strategy to capture dual‑clutch and wet‑clutch volume with local manufacturing scale. For 2026, expect continued emphasis on transmission module partnerships and cross‑selling into adjacent drivetrain systems.
-
Valeo: Strengthening its remanufacturing credentials (recognized by industry awards) positions Valeo to monetize aftermarket demand. OEMs seeking lifecycle cost reductions will increasingly specify reman options — forcing suppliers to demonstrate reverse‑logistics capabilities and certified process control.
-
ZF: Winning large contracts for heavy‑duty clutches in high‑growth commercial markets highlights ZF’s playbook of localizing production and leveraging established OEM relationships. This makes ZF a preferred partner where local content and supportability matter.
-
Eaton, Eagle, Amsted and others: These firms emphasize targeted regional product portfolios (e.g., Asian truck clutches, one‑way clutches for transmissions) and can be attractive acquisition or JV partners for firms seeking rapid market entry without greenfield risk.
Recent verified developments (2025–early 2026) — including contract awards in China and India, industry recognition for reman programs, and targeted product launches — validate the structural themes above: suppliers are localizing capacity in growth geographies, aftermarket and reman initiatives are moving from pilot to scale, and commercial vehicle demand is a strategic growth lever.
How to convert insight into 2026 action — an executive checklist
-
Rebalance capex: Prioritize flexible lines that can switch between wet/dry and friction/non‑friction assemblies to protect against platform volatility.
-
Secure input supply: Lock in multi‑year contracts or index‑linked supply agreements for key metallics and components to limit cost leakage.
-
Pursue aftermarket scale: Invest in certified reman corridors and partner with logistics providers to shorten returns cycles and preserve quality yield.
-
Adopt modular product architecture: Reduce engineering-to-order complexity and enable faster OEM program wins with configurable platforms.
-
Plan M&A with precision: Target sellers with ecosystem fit (reman capabilities, regional capacity, or niche technology) rather than chasing headline scale alone.
Conclusion — why 2026 matters
2026 is a year of active choices: firms that align product roadmaps to hybrid/commercial opportunities, harden procurement against tariff and material risk, and scale aftermarket/reman capabilities will secure outsized returns in a market growing from USD 13.5 billion in 2025 toward about USD 19.1 billion by 2032 at a 4.8% CAGR. Because the competitive top end remains concentrated (CR3 ~65%; CR5 ~75%), strategic moves that combine operational resilience with localized presence and a clear aftermarket model will determine winners.
PW Consulting’s full Automotive Clutch Market report contains the quantitative segment breakouts, scenario models, supplier benchmarking, and executable playbooks that operationalize the insights summarized here. For the granular regional, type, and application breakouts, as well as the downloadable forecasting model and program tracker, access the full report at our publication portal.
For detailed analysis of this topic, please visit the official page: Automotive Clutch Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Fuel Dispensers Market to Hit USD 435M by 2032 at 5.8% CAGR
By pmarketresearch, 2026-07-08
Fuel Dispensers Market 2026: Strategic Preview for Executive Decision-Making
As global forecourts, commercial fleets, and new mobility vectors evolve, the fuel dispensers market is entering a pivotal phase. PW Consulting’s latest market study—anchored to a 2025 base year and projecting through 2032—maps a clear growth path and delivers disciplined scenario analysis that is immediately actionable for C-suite teams planning capital allocation, portfolio reshaping, or market entry in 2026. This preview synthesizes the study’s top strategic takeaways while intentionally withholding detailed segment-level tables and regional shares to steer readers to the full report for proprietary datasets and granular forecasts.
Fuel Dispensers Market
Macro trajectory: steady growth with distinct inflection points
The market demonstrates a resilient recovery profile over the historical 2020–2025 window and enters the 2026–2032 forecast with a compounded annual growth rate (CAGR) of 5.8%. Measured in USD Million (base year 2025), the global market size moved from the low hundreds in 2020 to roughly 292.0 in 2025, and our baseline projects expansion to approximately 435.0 by 2032.
Fuel Dispensers Market
- 2020–2025: Stabilization and modernization—operators prioritized reliability and regulatory compliance after pandemic-era disruptions.
- 2026–2032: Transition-led growth—incremental demand from alternative fuel readiness, equipment replacement cycles, and digitization drives the mid-single-digit CAGR.
These topline dynamics matter for executives because they translate into predictable revenue bands and equipment lifecycles that can be timed for technology upgrades, manufacturing scale investments, and service network expansion without presuming explosive near-term demand shifts.
Fuel Dispensers Market
Why this study matters for 2026 strategic choices
- Timing capital expenditure: With the market on a steady upcycle, minor shifts in deployment timing (12–18 months) materially affect unit economics for manufacturing and installers. The study provides demand phasing models that allow CFOs to stress-test CAPEX schedules against conservative, base, and accelerated adoption scenarios.
- Product roadmap prioritization: Dispenser design choices—modularity, multi-fuel readiness, payment/integration architecture, and metering accuracy—have different ROI timelines. Our analysis quantifies how those choices influence payback under alternative fuel adoption curves and tightening regulatory regimes.
- M&A and partnership playbooks: Market concentration data indicate a moderately consolidated landscape. The report overlays CR3 and CR5 dynamics with capability gaps (e.g., telematics, high-flow truck dispensing, hydrogen compatibility) to identify high-impact targets and partnership structures that maximize immediate scale and technical breadth.
- Aftermarket and services optimization: Given extended equipment lifecycles and recurring inspection/regulatory demands, services (maintenance, verification, certification) are a durable revenue pool. We provide margin modeling and regional service-cost differentials that help operators design profitable aftermarket bundles.
Key market drivers and structural shifts
Three interlocking forces will shape outcomes across the forecast window:
- Regulatory tightening and metrology compliance: Mandatory measurement accuracy standards and inspection regimes are raising the bar for installed base performance and replacement thresholds. Operators that proactively align with evolving metrology and labeling rules avoid retrofit costs and regulatory downtime.
- Fuel mix diversification: The gradual integration of compressed gases, biofuels, and hydrogen-compatible equipment creates an incumbency advantage for modular dispenser platforms. While liquid petroleum fuels remain core, multi-fuel capability is a clear differentiation for next-generation deployments.
- Digitalization and forecourt ecosystem integration: Cloud connectivity, remote diagnostics, and integrated payment solutions are shifting value from hardware-only sales toward recurring software and service revenue. Early movers can lock in sticky service contracts and capture telemetry-derived product improvements.
Regulatory and standards context: compliance as strategy
Regulatory developments in 2024–2026 are not mere cost items—they are strategic levers. Key points shaping market behavior include:
-
- Accuracy expectations aligned to OIML R117-1: Retail dispensers are expected to meet measurement accuracy thresholds (±0.3%), with periodic verification mandated in multiple jurisdictions. This raises demand for higher-precision metering and validated inspection services.
- Local inspection frameworks: Some jurisdictions have introduced new inspection and testing rules for retail dispensers effective 2025, increasing frequency of field verification and accelerating replacement of legacy units that cannot be cost-effectively verified.
- Labeling requirements for non-liquid fuels: Regulatory guidance on disclosure and labeling for CNG, LNG, and hydrogen affects forecourt design, signage, and compliance workflows—areas where integrators and compliance-enabled product lines will command a premium.
Leaders should treat compliance not as a cost center but as a differentiator: compliant-ready platforms sell faster in regulated markets and reduce total cost of ownership for site operators.
Supply chain, raw materials, and margin pressures
Sustained fluctuations in high-grade steel and specialized plastics have tightened margins and extended lead times for manufacturers. Our component-level sensitivity analysis shows that material price volatility can sway OEM gross margins by several percentage points, particularly for high-flow and multi-product dispenses that require heavier hydraulic assemblies. Strategies that matter in 2026 include hedging, design-for-cost substitution, supplier diversification, and more aggressive inventory policies for long-lead subassemblies.
Competitive landscape: who matters and where
The market is populated by a mix of global incumbents and regional specialists. The top manufacturers combine broad product lines with deep forecourt systems integration; notable players we profile in the report include:
-
-
- Gilbarco Veeder-Root (Cumming, Georgia, United States): Established leader with strong retail dispenser portfolio and growing alternative-fuel capabilities, including units compatible with CNG and hydrogen.
- Wayne Fueling Systems (Blue Bell, Pennsylvania, United States): Known for connected dispenser platforms; recently launched an advanced connected dispenser series with enhanced networking and cloud features.
- Dover Fueling Solutions (Nashville, Tennessee, United States): Broad product range under multiple brand families; recent product introductions emphasize modularity and hydraulic improvements.
- Tatsuno Corporation (Tokyo, Japan): High-precision hydraulic systems and strong credentials in biofuel-compatible dispensing technology.
- Bennett Pump Company (Kansas City, Missouri, United States): Focused on commercial and high-flow truck refueling applications, with strength in multi-fuel systems for fleet environments.
- Tokheim, Piusi, Scheidt & Bachmann, Censtar, Tominaga, and Korea EnE: Each brings regional strength or niche technology (metering precision, payment integration, or commercial transfer) that complements global leaders.
-
Recent product activity underscores the pace of incremental innovation: Wayne’s October 2025 connected Helix® 5000 II launch and Dover’s February 2025 Quantum 510M modular series are examples of suppliers pushing both networking and modular hydraulic advantages to capture replacement and retrofit projects.
What PW Consulting’s full report delivers (practical, executable content)
This study is structured to support immediate decision-making across four operational horizons:
-
-
- Market sizing & scenarios: Base-case and alternate adoption scenarios (conservative to accelerated) with demand phasing by year to inform CAPEX and procurement timelines.
- Competitive playbooks: Profiles, capability matrices, and a “buy/build/partner” decision framework for different company archetypes (OEM, integrator, retailer, service provider).
- Commercial models: Unit economics for new dispenser sales, retrofit vs. replacement thresholds, and aftermarket service-margin benchmarks to size opportunity pools.
- Regulatory & compliance checklist: Jurisdictional triggers for mandatory verification, labeling, and certification along with costed compliance pathways.
-
Importantly, the proprietary sections containing granular regional splits, application-level forecasts, and vendor share tables are intentionally gated. These datasets are designed for transaction-grade use—investment committees, product leadership, and M&A teams should consult the full report for exact figures and downloadable model files.
How to convert insight into 90-day actions
-
-
- Audit installed base: Prioritize sites for upgrade based on compliance risk, uptime value, and retrofit economics—our risk matrix reduces site-level decision friction.
- Accelerate modular product trials: Shortlist two modular dispenser configurations and run pilot deployments with telemetry enabled; the report provides templated KPI dashboards for pilots.
- Set service subscription pilots: Convert maintenance and verification activities into subscription revenue pilots in two strategic markets; the study includes starter pricing and retention assumptions.
- Screen M&A targets: Use our capability-gap framework to rank acquisition or minority-investment candidates by strategic fit and integration complexity.
-
Final note: the hidden value
The top-line growth and steady CAGR establish the market’s attractive risk-return profile for balanced portfolios: predictable equipment replacement demand, durable aftermarket revenues, and pockets of high-margin innovation tied to alternative fuels and digital services. Yet, the real value for 2026 decision makers lies in the report’s proprietary, model-driven insights—detailed segmentation, vendor share matrices, price-volume sensitivity models, and scenario-ready financial templates—that convert the headline trajectory into executable business plans.
To access the full datasets, segmentation breakdowns, and operational tools that underpin these conclusions, please follow the link to PW Consulting’s Fuel Dispensers Market dossier. The gated analysis is designed to be used directly by strategy, finance, and product teams to accelerate 2026 planning cycles.
For detailed analysis of this topic, please visit the official page: Fuel Dispensers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Supercapacitors Market to Reach USD 835M by 2032 at 19.2% CAGR — Asia Pacific Leads
By pmarketresearch, 2026-07-08
Supercapacitors Market — 2026 Strategic Preview
PW Consulting’s latest Supercapacitors Market study (base year 2025; historical 2020–2025; forecast 2026–2032) crystallizes the commercial and technological inflection points that will shape strategic decisions across the energy, mobility, industrial and electronics value chains in 2026. The market has expanded rapidly over the past half-decade and, with a compound annual growth rate of 19.2% through the forecast period, PW projects an increase from an overall market size of USD 244.0 Million (2025, Million USD units) to approximately USD 835.0 Million by 2032. This preview outlines why that trajectory matters for boardrooms, product teams and M&A desks and how our full report translates growth signals into executable choices — while intentionally reserving the granular regional, application and product splits for subscribers seeking the complete intelligence package.
Supercapacitors Market
Why This Study Matters for 2026 Decisions
-
Investment Prioritization — With near-quadruple growth implied over a seven-year horizon, capital allocation must move from exploratory pilots to invest-to-scale options for firms that want to capture disproportionate share. The report gives a framework to size payback horizons under multiple commercialization scenarios, enabling CFOs to prioritize capex and R&D budgets that align with realistic time-to-revenue expectations.
Supercapacitors Market -
Product Roadmaps — Advances in materials (e.g., graphene-enhanced electrodes) and form factors (ultra-thin prismatic cells) are creating new product adjacencies. Engineering leadership can use our technology readiness and performance trade-off matrices to decide which chemistries and architectures to pursue for targeted use cases where supercapacitors deliver a differentiated system-level value.
Supercapacitors Market -
Supply Chain & Sourcing Strategies — Material cost dynamics and geopolitical designations are reshaping inputs. The report operationalizes raw-material risk into procurement scenarios and contract structures that buyer teams can deploy in 2026 to lock in supply, hedge prices or qualify alternate suppliers with minimal operational disruption.
-
M&A and Partnering Playbooks — Given an industry where the top three players collectively command a material share yet specialization remains a viable route to competitive advantage, corporate development teams can use our target-screening filters and commercial due-diligence templates to identify bolt-on acquisitions and strategic partnerships that accelerate time-to-market.
-
Regulatory & ESG Compliance — Emerging critical-mineral classifications and documented labor risks in upstream raw-material chains mean procurement and compliance officers must treat non-financial risk as a strategic input. The study links compliance levers to commercial outcomes and provides stepwise remediation plans for at-risk supply relationships.
What the Report Delivers — Practical, Hands-On Content
-
Market sizing and trend model: detailed historicals (2020–2025), a transparent forecasting methodology for 2026–2032, and scenario outputs that stress-test adoption curves under differing macroeconomic and technology-innovation assumptions.
-
Technology performance and cost matrices: comparative analysis across double-layer, pseudocapacitor and hybrid architectures; component-level cost drivers and a manufacturing cost build-up that identifies the major cost levers you can act on. Notably, activated carbon—one of the primary active materials used in EDLC designs—dominates manufacturing cost composition, representing a significant share of component cost for EDLCs.
-
Competitive profiles and go-to-market maps: concise strategic dossiers on leading suppliers and disruptors, including product positioning, core competencies, commercial strengths and likely next moves.
-
Commercial playbooks and tools: supplier scorecards, contracting templates, pilot-to-scale checklists, and an investment-case calculator that ties technical performance to revenue and margin outcomes at multiple production scales.
-
Risk and compliance modules: mitigation templates for material sourcing risk, supplier ESG due diligence checklists, and regulatory watchpoints tied to the major markets affected by mineral classification and chemical regulation.
Competitive Landscape — Who Matters and Why
The market exhibits a mix of established incumbents and fast-moving specialists. The top-tier players maintain substantial installed customer relationships and system-integration expertise, while nimble innovators are capitalizing on thin-form factors and advanced materials to create disruptive point solutions. The market concentration metrics indicate that leading firms hold a meaningful slice of the market, yet there is ample room for targeted newcomers and vertically integrated players to win niches or prompt consolidation.
-
Incumbents and system integrators — Companies with broad electrification and power-systems portfolios bring scale advantages in module assembly, system certification and channel access. These firms are the logical partners for OEMs seeking turnkey integration into EV subsystems, grid-stabilization assets and industrial power backups.
-
Specialist material and cell innovators — Firms leveraging novel materials (e.g., graphene-enhanced electrodes) and engineering breakthroughs (ultra-thin prismatic cells) are penetrating high-value verticals such as data-center power support and compact consumer form factors. Their differentiation is technological, but they face scaling and supply-chain challenges as demand ramps.
-
Regional and cost-focused manufacturers — Producers with local manufacturing footprints and cost-optimized product lines are well-positioned to serve regional infrastructure projects and cost-sensitive industrial applications, especially where supply-chain security or tariff exposure is a priority.
Recent market moves underscore these dynamics. Product launches designed for AI data-center peak-power support and ultra-thin prismatic supercapacitors for compact devices demonstrate both demand-side pull (power-dense, rapid-energy delivery) and supply-side innovation (materials and form-factor breakthroughs). These developments are instructive for corporate leaders who must weigh whether to partner with innovators, acquire intellectual property or accelerate in-house R&D.
Market Dynamics & Risk Matrix
-
Raw-material concentration — A small set of inputs dominate EDLC manufacturing costs; procurement teams should model the impact of price swings and availability shocks on margin profiles and consider hedges, multi-sourcing and strategic stockpiles.
-
Critical-mineral policy risk — Recent governmental designations of common inputs as critical minerals alter the calculus for cross-border sourcing. Supply-chain teams must integrate regulatory scenarios into supplier evaluation and logistics planning.
-
Labor and reputational risk — Reports of exploitative practices in upstream material processing introduce a reputational and regulatory compliance dimension; companies must adopt traceability and supplier audits as part of a 2026 procurement baseline.
-
Technology and market risk — New materials and architectures can change value-capture dynamics quickly; R&D leaders should run parallel roadmaps that balance near-term commercial wins with long-term platform bets.
90-Day Playbook for 2026
-
0–30 days: Rapid diagnostic — Use our supplier scorecard to map your current exposure to material and supplier risk, run a simplified sensitivity on your gross margins against raw-material price swings, and prioritize two high-impact supplier negotiations.
-
30–60 days: Technical de-risking — Execute bench-level trials with shortlisted cell technologies (guided by our TRL matrix), finalize pilot specifications and engage potential integration partners under mutual non-disclosure terms.
-
60–90 days: Commercialization decisions — Close pilots, finalize supply contracts with embedded performance SLAs, and set a phased manufacturing ramp-up plan tied to explicit go/no-go performance and commercial milestones.
What We Deliberately Withhold Here (and Why)
This preview intentionally surfaces high-level conclusions and actionable frameworks while withholding detailed segment-by-region, product-by-application revenue tables and unit-price curves. Those granular splits, supplier-level volume estimates and full raw datasets are the core of the paid report and are essential for transaction-grade decision-making. We adopt this “trailer” approach to demonstrate analytic rigor and to ensure that subscribers obtain exclusive, verifiable detail to deploy in contractual negotiations, procurement and M&A diligence.
Next Steps
For executive teams tasked with translating macro growth into defensible commercial advantage in 2026, PW Consulting offers tailored briefings, scenario workshops and deep-dive diligence engagements that operationalize the findings in the full report. Reach out to schedule a strategy session or to obtain the complete dataset, including the regional and application-level modeling that underpins the market trajectory from 2026 through 2032.
For detailed analysis of this topic, please visit the official page: Supercapacitors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Washer-Disinfectors Market: Strategic Outlook for 2026 Decision-Makers
Executive snapshot
As organizations prepare capital plans and procurement strategies for 2026, the washer-disinfectors market presents both predictable growth and concentrated competitive risk. Our base-year analysis (2025) values the global market at approximately USD 379 Million (revenue unit: Million), and PW Consulting's validated projection for the forecast window (2026–2032) is guided by a compound annual growth rate of 6.5%, taking the market to the high hundreds of millions by 2032. That topline trajectory is driven by persistent infection-control imperatives, equipment replacement cycles across central sterile supply departments (CSSDs), and rising demand for traceable, validated reprocessing workflows across clinical and dental settings.
Washer-Disinfectors Market
Why this study matters for 2026 choices
- Prioritizing capital allocation: distinguish one-off procurement needs from multi-year service and consumables commitments that will shape total cost of ownership.
- Regulatory compliance as a commercial differentiator: recent standards and pathway changes mean product design, validation, and documentation are now integral to sales and post-sale assurance.
- Tender and procurement strategy: public tenders are active across multiple regions; understanding specification nuances and supplier risk profiles is essential to win and to manage supply continuity.
- M&A and partnership scouting: moderate market concentration creates windows for bolt-on acquisitions and strategic alliances—especially in service, software traceability, and specialty endoscope reprocessing.
- Operational resilience: recall events and tighter standards increase the value of after-sales service networks and real-time process traceability for clinical customers.
What PW Consulting’s report delivers (practical intelligence)
This study is built as a decision-support toolkit focused on near-term, executable choices rather than academic breadth. Key deliverables include:
Washer-Disinfectors Market
- Top-down validated market sizing and forecast through 2032, with sensitivity bands and a transparent modelling appendix allowing clients to re-run scenarios with bespoke assumptions.
- Demand-driver mapping: buyer personas, procurement cycles by facility type, and decision-criteria scoring frameworks that procurement teams can apply immediately during RFP evaluations.
- Regulatory and standards matrix: a practitioner’s translation of the latest normative updates into product development checklists, validation scripts, and marketing claims that withstand audits.
- Competitive supplier heatmaps and vendor scorecards: technology differentiation, service footprint, pricing posture, and channel strengths—presented to preserve competitive confidentiality while enabling tactical vendor selection.
- Tender intelligence: recent award themes, specification trends, and a repertoire of language options and commercial clauses that increase win probability in public and private tenders.
- Commercial playbooks: go-to-market templates for OEMs and distributors (pricing ladders, service contracts, consumables bundling, and retrofit strategies), plus an operator playbook for CSSD managers to optimize utilization and validation.
- Risk and compliance checklists tailored to procurement, clinical engineering, and regulatory affairs teams—covering recall scenarios, post-market surveillance, and 510(k) interaction strategies where applicable.
Market dynamics shaping supplier and buyer strategy
Three industry developments in 2025–2026 crystallize the near-term strategic agenda:
Washer-Disinfectors Market
- Standards evolution: the EN ISO 15883 series received substantive updates in 2025, including parts that clarify performance and testing approaches for general washer-disinfectors, thermal disinfection for thermolabile devices, and chemical disinfection for non-critical thermolabile devices. These revisions tighten validation expectations and documentation footprints—creating both a compliance burden and a premium for product lines that embed validation-ready features.
- Regulatory and reimbursement nuances: for jurisdictions tied to FDA pathways, high-level disinfection processes that underpin reimbursement and institutional acceptance often require explicit 510(k) considerations or equivalent submissions. Manufacturers and buyers must align product claims, labelling, and validation evidence with regulatory expectations to avoid downstream reimbursement friction.
- Procurement and field risk events: the market has seen active public tenders across geographies and a notable Class 2 recall involving a major OEM in 2025. Tender activity signals continuing institutional investment, while recalls underscore the commercial and reputational cost of design or manufacturing lapses—heightening the value of robust post-market surveillance, spare-parts logistics, and service-level guarantees.
Competitive landscape — what to watch from the leading suppliers
The market is meaningfully concentrated, with the leading players commanding a majority share of institutional procurement. This concentration combines global OEM scale with specialized regional and product-line expertise. Below are the strategic profiles and implications of the most consequential players:
- STERIS Corporation — Strengths include a deep installed base in hospitals and a focus on high-level disinfection in reusable instrument processing. For buyers, STERIS represents a full-spectrum option with recognized infection-control credentials; for competitors, their brand equity raises the bar on service expectations.
- Getinge AB — Offers high-capacity, energy-efficient multi-chamber platforms with strong traceability capabilities. The firm’s product breadth is a competitive advantage, but recent recall activity highlights the operational exposure that large-scale OEMs face. Procurement teams should weigh performance claims against documented post-market support commitments.
- Steelco S.p.A. — Known for instrument washers across CSSD and pharmaceutical segments with flexible installation and maintenance services. Their positioning is attractive to buyers seeking tailored capacity solutions and close field support.
- MELAG — Focused on dental and specialist medical reprocessing with integrated documentation systems. Dental clinics and ambulatory specialty units will find their traceability and compact solutions compelling—important when designing segmented product strategies or OEM partnerships.
- Miele Professional — Offers undercounter and overcounter models emphasizing energy efficiency and ergonomics—relevant for dental surgeries and labs where footprint and operational cost matter. Their consumer brand spillover creates a premium perception in certain markets.
- Belimed AG — Provides washing and disinfection solutions with particular strength in surgical instruments and endoscopes, supported by a robust European service network, which is critical where uptime and infection control are non-negotiable.
- MMM Medical Equipment UK Ltd & iM Med — Both companies focus on flexible endoscope reprocessing and niche reprocessing technologies. Their specialization addresses a high-risk, high-compliance subsegment where channel-monitoring and process traceability deliver outsized value.
Strategic implications and recommended 90‑day actions for 2026
- Immediate procurement due diligence: require vendors to submit standardized validation dossiers mapped to EN ISO 15883 clauses and, where relevant, evidence of regulatory filings (e.g., 510(k) status). Include contractual remedies tied to recalls and spare parts availability.
- Embed lifecycle costing in RFPs: move beyond headline price to model consumables, validation labour, energy use, and mid-life retrofits. The highest-value vendors will be those who can shift the conversation to annualized operational cost reductions.
- Prioritize traceability and software integration: demand solutions with audit-ready electronic documentation and compatibility with hospital IT systems—this is increasingly a procurement blocker for tertiary care facilities.
- Service network and spare-parts stress-testing: include scenario-based KPIs in contracts (e.g., mean time to repair, guaranteed parts availability during recalls) to mitigate downtime risk highlighted by recent market events.
- M&A and partnership scouting: suppliers with narrow product portfolios but attractive service footprints are prime acquisition targets for larger OEMs seeking to expand specialty reprocessing capabilities.
Access and next steps
This introduction previews the actionable intelligence that organizations need to make robust 2026 decisions. The full PW Consulting Washer-Disinfectors Market report provides the granular, source-verified detail (regional and application splits, vendor scorecards, tender-level intelligence, and our financial model) that procurement, product, and corporate strategy teams will use to execute with confidence. For organizations evaluating capital projects, preparing for tenders, or sizing M&A opportunities, our proprietary model and supplier due-diligence appendices convert industry insight into operational directives.
To obtain the full dataset, vendor benchmarking, and the reproducible forecast model, visit our research access page or contact PW Consulting’s healthcare equipment practice. The detailed segmentation and supplier profiles are presented in a way that supports confidential procurement negotiations and defensible boardroom recommendations.
For detailed analysis of this topic, please visit the official page: Washer-Disinfectors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com