

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Automotive Seat Heater Market to Reach USD 4,557.6M by 2032 at 6.6% CAGR

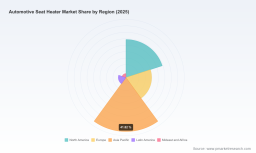
Automotive Seat Heater Market — Strategic Primer for 2026 Decision Makers
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present this concise yet insight-rich primer to orient executive teams, product leaders, and corporate strategists ahead of the critical planning cycle in 2026. This piece synthesizes the market trajectory, competitive dynamics, regulatory and technology pressures, and the practical decision levers that will determine success over the 2026–2032 forecast window. It intentionally showcases analytical depth while preserving the granular segmentation and scenario tables that comprise the full advisory—those assets remain available in the full report for teams that require executable, model-backed intelligence.
Automotive Seat Heater Market
Market at a glance: growth profile and recent rhythm
The automotive seat heater market enters 2026 from a position of steady recovery and structural opportunity. Using 2025 as the base year, the market is approaching a multi-year expansion path driven by broader vehicle feature penetration, cabin thermal comfort expectations in electrified vehicles, and materials/architecture shifts among suppliers and OEMs. Our macro forecast projects a compound annual growth rate (CAGR) of 6.6% through 2032, taking the market from the 2025 baseline into materially higher absolute levels by the end of the forecast window.
Automotive Seat Heater Market
Historical dynamics since 2020 show a market that absorbed macroeconomic volatility while retaining a long-term positive trend in unit and content-per-vehicle adoption. That resilience—coupled with a predictable upgrade cycle tied to vehicle refreshes and rising expectations for thermal comfort in electrified platforms—creates a clear, investable runway for suppliers and OEMs willing to align technology, cost, and compliance strategies.
Automotive Seat Heater Market
Why this report matters to 2026 strategy
- Capital allocation and foot-printing: The market’s growth profile requires firms to decide where to place manufacturing capacity, invest in automation for thin-film and carbon-based heating elements, or opt for contract manufacturing. Timing these investments will materially affect cost position in the 2027–2030 window.
- Technology bets: Suppliers face a binary choice in some product lines—double down on tried-and-tested resistance wire approaches or accelerate migration to carbon-based, sheet, and zonal heating technologies that favor energy efficiency and packaging integration for EV cabins.
- OEM sourcing and supplier tiers: Procurement teams need a clear rubric for evaluating incumbent versus emergent suppliers across quality, homologation time, total cost of ownership (TCO), and co-development capability for seat-integrated thermal systems.
- Regulatory and safety compliance: Evolving Western European and global safety standards mandate additional testing and product design investments; failure to pre-emptively operationalize compliance can derail product launches and create warranty exposure.
Technology and regulation: twin forces reshaping product roadmaps
Two forces are accelerating structural change. First, material and architecture innovation—driven by lighter, lower-power heating solutions and improved thermal management—has become a primary differentiator. Leading OEMs are specifying lower-voltage, faster warm-up, and zoned heating systems that integrate with seat ventilation, occupant sensors, and body control modules. Second, regulatory scrutiny—particularly in Western Europe—has raised the bar for safety testing, electrical fault tolerance, and long-term durability. Meeting these standards is non-negotiable and increasingly requires documented R&D investment, compliance testing, and traceable quality systems.
For suppliers, the implication is clear: product roadmaps must prioritize energy efficiency, fail-safe electrical protection, and testable durability to pass both OEM requirements and third-party homologation. For OEMs, specifying future-proof interfaces and software hooks for thermal control allows greater differentiation in user experience without repeated hardware redesigns.
Competitive landscape — strategic positioning of key players
The market structure today is characterized by a mix of global Tier-1 integrators, component specialists, and regional players operating across both OEM and aftermarket channels. Market concentration is moderate: the top three suppliers do not control an overwhelming share, with the top five collectively forming a meaningful but not dominant bloc—this creates space for both consolidation and niche leadership. Competitive dynamics split along capability clusters: full-seat integrators, heating-element specialists, and cost-competitive regional manufacturers.
- Gentherm Incorporated (Ann Arbor, MI): A technology-led player with a broad product portfolio including wire, carbon fiber, over-sewable and zonal heating solutions. Their CCS® Heat systems and focus on energy-efficient integration position them strongly for OEM programs that value modularity and advanced thermal management.
- Lear Corporation (Southfield, MI): An integrated seating systems leader that embeds thermal functions into full seat assemblies. Lear’s advantage lies in seat-level integration, scale, and OEM relationships—important where seat architecture decisions are centralized with the vehicle OEM.
- Panasonic Corporation (Kadoma, Osaka): Brings cross-domain electronics and automotive interior expertise. Panasonic’s strength is system-level integration and the ability to fold seat heating into broader cabin electronics packages.
- W.E.T. Automotive Systems AG (Oberderdingen, Germany): Specializes in conductive sheet-type heating elements; a strong fit for OEMs seeking thin, uniform heating panels and compact integration.
- Regional and aftermarket players (multiple headquartered in China and the USA): A cohort of agile manufacturers focus on standard and carbon variants for both OEM and aftermarket segments. These firms often compete on cost, rapid time-to-market, or specialized customer solutions (e.g., retrofits, model-specific kits).
Collectively, this competitive set creates multiple strategic entry points: partners for system integration, acquisition targets for technology access, and potential disruptors in low-cost, high-volume supply corridors.
What the full PW Consulting report delivers — practical, actionable, and implementable
The full market research report transcends conventional market-size narratives and delivers playbooks and decision tools firms need to act in 2026:
- Bottom-up and top-down forecast models with scenario sensitivity (base, accelerated adoption, and downside); note that the full report contains granular segmentation and regional breakdowns reserved for subscribers.
- Decision frameworks for make vs. buy, including a supplier selection matrix weighted for homologation lead time, TCO, and quality risk.
- Product roadmap templates aligning heating technology choices to vehicle architecture (ICE, hybrid, BEV) and cabin energy budgets.
- Regulatory compliance checklists and test-plan blueprints tailored to major markets—highlighting test-cases that commonly extend launch cycles if unaddressed early.
- Commercial models: pricing elasticity tables, margin impact of material substitution, and go-to-market playbooks for OEM vs aftermarket channels.
- Targeted M&A screening criteria and an anonymized shortlist of potential acquisition candidates aligned to different strategic objectives (technology access, capacity, geographic coverage).
Recommended 90/180/360 day roadmap for 2026
- 0–90 days: Conduct a gap analysis of current product portfolio vs. energy-efficiency and safety requirements; initiate prioritized supplier dialogues for carbon-based and sheet-heating options; secure homologation test slots for any upcoming platform launches.
- 90–180 days: Pilot a cross-functional seat-thermal integration lab with one OEM program or an internal platform; finalize sourcing decisions for critical components; lock negotiation parameters for 2027 volumes.
- 180–360 days: Scale manufacturing capability (in-house or via partner); deploy field trials focused on thermal comfort and durability; finalize any strategic acquisitions or joint ventures to fill capability gaps identified in the first half of the year.
Risks, signals, and triggers to monitor
- Regulatory tightening: New test standards or extended durability specs can materially affect lead times and cost—monitor Western Europe and principal OEM markets closely.
- Material supply shocks: Rapid moves toward carbon-based heaters increase demand for specialty conductive textiles and adhesives; supply-chain resilience must be stress-tested.
- OEM specification shifts: If major OEMs consolidate thermal-control functionality at seat-platform level, advantage will accrue to integrated seating suppliers; conversely, modular interface standards would favor heating-element specialists.
- Aftermarket growth dynamics: A healthy aftermarket can erode OEM pricing leverage or create parallel growth opportunities—strategies should cover both channels.
Closing — the strategic value of this intelligence for 2026
For executives making allocation, sourcing, or M&A decisions in 2026, the essential value lies not only in recognizing that the automotive seat heater market is growing at a mid-single-digit CAGR over the 2026–2032 period, but in understanding the interplay between technology choice, regulatory expectation, competitive posture, and operational readiness. The right combination of targeted R&D, supplier alignment, and compliant product engineering will determine which firms convert favorable market growth into sustained margin expansion and strategic positioning.
To move from insight to action, PW Consulting’s full report contains the granular segmentation, scenario spreadsheets, supplier scorecards, and test-plan templates required to operationalize these recommendations. Access the comprehensive intelligence and downloadable toolkits on the PW Consulting report page to obtain the underlying models, detailed regional and application breakdowns, and company-specific playbooks reserved for report subscribers.
For detailed analysis of this topic, please visit the official page: Automotive Seat Heater Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com