

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Supercapacitors Market to Reach USD 835M by 2032 at 19.2% CAGR — Asia Pacific Leads

Supercapacitors Market — 2026 Strategic Preview
PW Consulting’s latest Supercapacitors Market study (base year 2025; historical 2020–2025; forecast 2026–2032) crystallizes the commercial and technological inflection points that will shape strategic decisions across the energy, mobility, industrial and electronics value chains in 2026. The market has expanded rapidly over the past half-decade and, with a compound annual growth rate of 19.2% through the forecast period, PW projects an increase from an overall market size of USD 244.0 Million (2025, Million USD units) to approximately USD 835.0 Million by 2032. This preview outlines why that trajectory matters for boardrooms, product teams and M&A desks and how our full report translates growth signals into executable choices — while intentionally reserving the granular regional, application and product splits for subscribers seeking the complete intelligence package.
Supercapacitors Market
Why This Study Matters for 2026 Decisions
-
Investment Prioritization — With near-quadruple growth implied over a seven-year horizon, capital allocation must move from exploratory pilots to invest-to-scale options for firms that want to capture disproportionate share. The report gives a framework to size payback horizons under multiple commercialization scenarios, enabling CFOs to prioritize capex and R&D budgets that align with realistic time-to-revenue expectations.
Supercapacitors Market -
Product Roadmaps — Advances in materials (e.g., graphene-enhanced electrodes) and form factors (ultra-thin prismatic cells) are creating new product adjacencies. Engineering leadership can use our technology readiness and performance trade-off matrices to decide which chemistries and architectures to pursue for targeted use cases where supercapacitors deliver a differentiated system-level value.
Supercapacitors Market -
Supply Chain & Sourcing Strategies — Material cost dynamics and geopolitical designations are reshaping inputs. The report operationalizes raw-material risk into procurement scenarios and contract structures that buyer teams can deploy in 2026 to lock in supply, hedge prices or qualify alternate suppliers with minimal operational disruption.
-
M&A and Partnering Playbooks — Given an industry where the top three players collectively command a material share yet specialization remains a viable route to competitive advantage, corporate development teams can use our target-screening filters and commercial due-diligence templates to identify bolt-on acquisitions and strategic partnerships that accelerate time-to-market.
-
Regulatory & ESG Compliance — Emerging critical-mineral classifications and documented labor risks in upstream raw-material chains mean procurement and compliance officers must treat non-financial risk as a strategic input. The study links compliance levers to commercial outcomes and provides stepwise remediation plans for at-risk supply relationships.
What the Report Delivers — Practical, Hands-On Content
-
Market sizing and trend model: detailed historicals (2020–2025), a transparent forecasting methodology for 2026–2032, and scenario outputs that stress-test adoption curves under differing macroeconomic and technology-innovation assumptions.
-
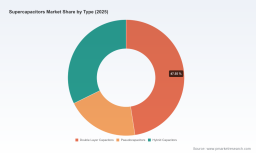
Technology performance and cost matrices: comparative analysis across double-layer, pseudocapacitor and hybrid architectures; component-level cost drivers and a manufacturing cost build-up that identifies the major cost levers you can act on. Notably, activated carbon—one of the primary active materials used in EDLC designs—dominates manufacturing cost composition, representing a significant share of component cost for EDLCs.
-
Competitive profiles and go-to-market maps: concise strategic dossiers on leading suppliers and disruptors, including product positioning, core competencies, commercial strengths and likely next moves.
-
Commercial playbooks and tools: supplier scorecards, contracting templates, pilot-to-scale checklists, and an investment-case calculator that ties technical performance to revenue and margin outcomes at multiple production scales.
-
Risk and compliance modules: mitigation templates for material sourcing risk, supplier ESG due diligence checklists, and regulatory watchpoints tied to the major markets affected by mineral classification and chemical regulation.
Competitive Landscape — Who Matters and Why
The market exhibits a mix of established incumbents and fast-moving specialists. The top-tier players maintain substantial installed customer relationships and system-integration expertise, while nimble innovators are capitalizing on thin-form factors and advanced materials to create disruptive point solutions. The market concentration metrics indicate that leading firms hold a meaningful slice of the market, yet there is ample room for targeted newcomers and vertically integrated players to win niches or prompt consolidation.
-
Incumbents and system integrators — Companies with broad electrification and power-systems portfolios bring scale advantages in module assembly, system certification and channel access. These firms are the logical partners for OEMs seeking turnkey integration into EV subsystems, grid-stabilization assets and industrial power backups.
-
Specialist material and cell innovators — Firms leveraging novel materials (e.g., graphene-enhanced electrodes) and engineering breakthroughs (ultra-thin prismatic cells) are penetrating high-value verticals such as data-center power support and compact consumer form factors. Their differentiation is technological, but they face scaling and supply-chain challenges as demand ramps.
-
Regional and cost-focused manufacturers — Producers with local manufacturing footprints and cost-optimized product lines are well-positioned to serve regional infrastructure projects and cost-sensitive industrial applications, especially where supply-chain security or tariff exposure is a priority.
Recent market moves underscore these dynamics. Product launches designed for AI data-center peak-power support and ultra-thin prismatic supercapacitors for compact devices demonstrate both demand-side pull (power-dense, rapid-energy delivery) and supply-side innovation (materials and form-factor breakthroughs). These developments are instructive for corporate leaders who must weigh whether to partner with innovators, acquire intellectual property or accelerate in-house R&D.
Market Dynamics & Risk Matrix
-
Raw-material concentration — A small set of inputs dominate EDLC manufacturing costs; procurement teams should model the impact of price swings and availability shocks on margin profiles and consider hedges, multi-sourcing and strategic stockpiles.
-
Critical-mineral policy risk — Recent governmental designations of common inputs as critical minerals alter the calculus for cross-border sourcing. Supply-chain teams must integrate regulatory scenarios into supplier evaluation and logistics planning.
-
Labor and reputational risk — Reports of exploitative practices in upstream material processing introduce a reputational and regulatory compliance dimension; companies must adopt traceability and supplier audits as part of a 2026 procurement baseline.
-
Technology and market risk — New materials and architectures can change value-capture dynamics quickly; R&D leaders should run parallel roadmaps that balance near-term commercial wins with long-term platform bets.
90-Day Playbook for 2026
-
0–30 days: Rapid diagnostic — Use our supplier scorecard to map your current exposure to material and supplier risk, run a simplified sensitivity on your gross margins against raw-material price swings, and prioritize two high-impact supplier negotiations.
-
30–60 days: Technical de-risking — Execute bench-level trials with shortlisted cell technologies (guided by our TRL matrix), finalize pilot specifications and engage potential integration partners under mutual non-disclosure terms.
-
60–90 days: Commercialization decisions — Close pilots, finalize supply contracts with embedded performance SLAs, and set a phased manufacturing ramp-up plan tied to explicit go/no-go performance and commercial milestones.
What We Deliberately Withhold Here (and Why)
This preview intentionally surfaces high-level conclusions and actionable frameworks while withholding detailed segment-by-region, product-by-application revenue tables and unit-price curves. Those granular splits, supplier-level volume estimates and full raw datasets are the core of the paid report and are essential for transaction-grade decision-making. We adopt this “trailer” approach to demonstrate analytic rigor and to ensure that subscribers obtain exclusive, verifiable detail to deploy in contractual negotiations, procurement and M&A diligence.
Next Steps
For executive teams tasked with translating macro growth into defensible commercial advantage in 2026, PW Consulting offers tailored briefings, scenario workshops and deep-dive diligence engagements that operationalize the findings in the full report. Reach out to schedule a strategy session or to obtain the complete dataset, including the regional and application-level modeling that underpins the market trajectory from 2026 through 2032.
For detailed analysis of this topic, please visit the official page: Supercapacitors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com