

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Fuel Dispensers Market to Hit USD 435M by 2032 at 5.8% CAGR

Fuel Dispensers Market 2026: Strategic Preview for Executive Decision-Making
As global forecourts, commercial fleets, and new mobility vectors evolve, the fuel dispensers market is entering a pivotal phase. PW Consulting’s latest market study—anchored to a 2025 base year and projecting through 2032—maps a clear growth path and delivers disciplined scenario analysis that is immediately actionable for C-suite teams planning capital allocation, portfolio reshaping, or market entry in 2026. This preview synthesizes the study’s top strategic takeaways while intentionally withholding detailed segment-level tables and regional shares to steer readers to the full report for proprietary datasets and granular forecasts.
Fuel Dispensers Market
Macro trajectory: steady growth with distinct inflection points
The market demonstrates a resilient recovery profile over the historical 2020–2025 window and enters the 2026–2032 forecast with a compounded annual growth rate (CAGR) of 5.8%. Measured in USD Million (base year 2025), the global market size moved from the low hundreds in 2020 to roughly 292.0 in 2025, and our baseline projects expansion to approximately 435.0 by 2032.
Fuel Dispensers Market
- 2020–2025: Stabilization and modernization—operators prioritized reliability and regulatory compliance after pandemic-era disruptions.
- 2026–2032: Transition-led growth—incremental demand from alternative fuel readiness, equipment replacement cycles, and digitization drives the mid-single-digit CAGR.
These topline dynamics matter for executives because they translate into predictable revenue bands and equipment lifecycles that can be timed for technology upgrades, manufacturing scale investments, and service network expansion without presuming explosive near-term demand shifts.
Fuel Dispensers Market
Why this study matters for 2026 strategic choices
- Timing capital expenditure: With the market on a steady upcycle, minor shifts in deployment timing (12–18 months) materially affect unit economics for manufacturing and installers. The study provides demand phasing models that allow CFOs to stress-test CAPEX schedules against conservative, base, and accelerated adoption scenarios.
- Product roadmap prioritization: Dispenser design choices—modularity, multi-fuel readiness, payment/integration architecture, and metering accuracy—have different ROI timelines. Our analysis quantifies how those choices influence payback under alternative fuel adoption curves and tightening regulatory regimes.
- M&A and partnership playbooks: Market concentration data indicate a moderately consolidated landscape. The report overlays CR3 and CR5 dynamics with capability gaps (e.g., telematics, high-flow truck dispensing, hydrogen compatibility) to identify high-impact targets and partnership structures that maximize immediate scale and technical breadth.
- Aftermarket and services optimization: Given extended equipment lifecycles and recurring inspection/regulatory demands, services (maintenance, verification, certification) are a durable revenue pool. We provide margin modeling and regional service-cost differentials that help operators design profitable aftermarket bundles.
Key market drivers and structural shifts
Three interlocking forces will shape outcomes across the forecast window:
- Regulatory tightening and metrology compliance: Mandatory measurement accuracy standards and inspection regimes are raising the bar for installed base performance and replacement thresholds. Operators that proactively align with evolving metrology and labeling rules avoid retrofit costs and regulatory downtime.
- Fuel mix diversification: The gradual integration of compressed gases, biofuels, and hydrogen-compatible equipment creates an incumbency advantage for modular dispenser platforms. While liquid petroleum fuels remain core, multi-fuel capability is a clear differentiation for next-generation deployments.
- Digitalization and forecourt ecosystem integration: Cloud connectivity, remote diagnostics, and integrated payment solutions are shifting value from hardware-only sales toward recurring software and service revenue. Early movers can lock in sticky service contracts and capture telemetry-derived product improvements.
Regulatory and standards context: compliance as strategy
Regulatory developments in 2024–2026 are not mere cost items—they are strategic levers. Key points shaping market behavior include:
-
- Accuracy expectations aligned to OIML R117-1: Retail dispensers are expected to meet measurement accuracy thresholds (±0.3%), with periodic verification mandated in multiple jurisdictions. This raises demand for higher-precision metering and validated inspection services.
- Local inspection frameworks: Some jurisdictions have introduced new inspection and testing rules for retail dispensers effective 2025, increasing frequency of field verification and accelerating replacement of legacy units that cannot be cost-effectively verified.
- Labeling requirements for non-liquid fuels: Regulatory guidance on disclosure and labeling for CNG, LNG, and hydrogen affects forecourt design, signage, and compliance workflows—areas where integrators and compliance-enabled product lines will command a premium.
Leaders should treat compliance not as a cost center but as a differentiator: compliant-ready platforms sell faster in regulated markets and reduce total cost of ownership for site operators.
Supply chain, raw materials, and margin pressures
Sustained fluctuations in high-grade steel and specialized plastics have tightened margins and extended lead times for manufacturers. Our component-level sensitivity analysis shows that material price volatility can sway OEM gross margins by several percentage points, particularly for high-flow and multi-product dispenses that require heavier hydraulic assemblies. Strategies that matter in 2026 include hedging, design-for-cost substitution, supplier diversification, and more aggressive inventory policies for long-lead subassemblies.
Competitive landscape: who matters and where
The market is populated by a mix of global incumbents and regional specialists. The top manufacturers combine broad product lines with deep forecourt systems integration; notable players we profile in the report include:
-
-
- Gilbarco Veeder-Root (Cumming, Georgia, United States): Established leader with strong retail dispenser portfolio and growing alternative-fuel capabilities, including units compatible with CNG and hydrogen.
- Wayne Fueling Systems (Blue Bell, Pennsylvania, United States): Known for connected dispenser platforms; recently launched an advanced connected dispenser series with enhanced networking and cloud features.
- Dover Fueling Solutions (Nashville, Tennessee, United States): Broad product range under multiple brand families; recent product introductions emphasize modularity and hydraulic improvements.
- Tatsuno Corporation (Tokyo, Japan): High-precision hydraulic systems and strong credentials in biofuel-compatible dispensing technology.
- Bennett Pump Company (Kansas City, Missouri, United States): Focused on commercial and high-flow truck refueling applications, with strength in multi-fuel systems for fleet environments.
- Tokheim, Piusi, Scheidt & Bachmann, Censtar, Tominaga, and Korea EnE: Each brings regional strength or niche technology (metering precision, payment integration, or commercial transfer) that complements global leaders.
-
Recent product activity underscores the pace of incremental innovation: Wayne’s October 2025 connected Helix® 5000 II launch and Dover’s February 2025 Quantum 510M modular series are examples of suppliers pushing both networking and modular hydraulic advantages to capture replacement and retrofit projects.
What PW Consulting’s full report delivers (practical, executable content)
This study is structured to support immediate decision-making across four operational horizons:
-
-
- Market sizing & scenarios: Base-case and alternate adoption scenarios (conservative to accelerated) with demand phasing by year to inform CAPEX and procurement timelines.
- Competitive playbooks: Profiles, capability matrices, and a “buy/build/partner” decision framework for different company archetypes (OEM, integrator, retailer, service provider).
- Commercial models: Unit economics for new dispenser sales, retrofit vs. replacement thresholds, and aftermarket service-margin benchmarks to size opportunity pools.
- Regulatory & compliance checklist: Jurisdictional triggers for mandatory verification, labeling, and certification along with costed compliance pathways.
-
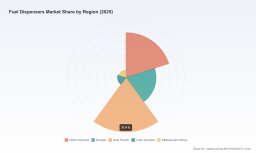
Importantly, the proprietary sections containing granular regional splits, application-level forecasts, and vendor share tables are intentionally gated. These datasets are designed for transaction-grade use—investment committees, product leadership, and M&A teams should consult the full report for exact figures and downloadable model files.
How to convert insight into 90-day actions
-
-
- Audit installed base: Prioritize sites for upgrade based on compliance risk, uptime value, and retrofit economics—our risk matrix reduces site-level decision friction.
- Accelerate modular product trials: Shortlist two modular dispenser configurations and run pilot deployments with telemetry enabled; the report provides templated KPI dashboards for pilots.
- Set service subscription pilots: Convert maintenance and verification activities into subscription revenue pilots in two strategic markets; the study includes starter pricing and retention assumptions.
- Screen M&A targets: Use our capability-gap framework to rank acquisition or minority-investment candidates by strategic fit and integration complexity.
-
Final note: the hidden value
The top-line growth and steady CAGR establish the market’s attractive risk-return profile for balanced portfolios: predictable equipment replacement demand, durable aftermarket revenues, and pockets of high-margin innovation tied to alternative fuels and digital services. Yet, the real value for 2026 decision makers lies in the report’s proprietary, model-driven insights—detailed segmentation, vendor share matrices, price-volume sensitivity models, and scenario-ready financial templates—that convert the headline trajectory into executable business plans.
To access the full datasets, segmentation breakdowns, and operational tools that underpin these conclusions, please follow the link to PW Consulting’s Fuel Dispensers Market dossier. The gated analysis is designed to be used directly by strategy, finance, and product teams to accelerate 2026 planning cycles.
For detailed analysis of this topic, please visit the official page: Fuel Dispensers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com