

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Automotive Clutch Market to Reach USD 19.1 Billion by 2032 at 4.8% CAGR

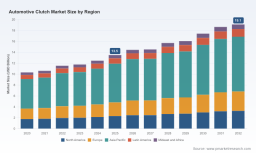
Automotive Clutch Market — Strategic Briefing for 2026 Decision-Makers
As PW Consulting’s lead industry analyst, I present a concise strategic primer to frame executive decisions on clutches and related drivetrain components in 2026. Drawing on our new market study (base year 2025; historical series 2020–2025; forecast horizon 2026–2032), this briefing synthesizes the macro trajectory, competitive dynamics, and executive implications you need to prioritize capital, product, and go‑to‑market choices this year — while preserving the report’s proprietary segment detail for subscribers.
Automotive Clutch Market
Market trajectory at a glance
The global automotive clutch market has moved from an estimated USD 10.3 billion in 2020 to USD 13.5 billion in 2025, reflecting a recovery and structural growth driven by vehicle production normalization, rising commercial vehicle activity in select markets, and expanded remanufacturing and aftermarket demand. Our forecast projects continued expansion through 2032, reaching approximately USD 19.1 billion, with an underlying compound annual growth rate (CAGR) of 4.8% for the 2026–2032 forecast window. The 2026 near‑term projection of about USD 14.45 billion marks the start of the next multi‑year growth phase embedded in our scenario sets.
Automotive Clutch Market
Two points matter for 2026 planning: first, growth is positive and persistent but not exponential — the market rewards disciplined product and cost positioning rather than broad, unfocused expansion. Second, concentration is material: the leading three players account for a sizeable majority of OEM volumes (CR3 ~65%), and the top five firms push that concentration higher (CR5 ~75%). This structure amplifies scale advantages for integrated suppliers and creates attractive niches for focused specialists and aftermarket innovators.
Automotive Clutch Market
Key dynamics shaping 2026 decisions
-
Supply‑chain and trade friction: Recent trade policy shifts and tariff adjustments have increased headwind risk for cross‑border part flows. Coupled with rules of origin requirements under North American trade arrangements, sourcing strategies that rely on long, tariff‑exposed value chains will face margin erosion unless actively managed.
-
Raw material volatility: Steel and aluminum price and availability remain the most direct input risks for clutch manufacturers. Firms with secured multi‑tier contracts or hedging strategies will preserve margins; those without should expect procurement cost leakage.
-
Electrification and platform change: Battery electric vehicle (BEV) penetration changes the functional role and volume profile for clutches in certain applications, while hybrids and commercial drivetrains sustain demand. The result is a bifurcated product roadmap requirement: highly engineered solutions for hybrid/custom powertrains alongside cost‑competitive suites for traditional ICE and commercial fleets.
-
Aftermarket and remanufacturing momentum: Remanufactured clutch programs — validated by recent industry awards and OEM acceptance — are creating higher margin aftermarket revenue pools. Capturing these requires reverse logistics, quality traceability, and targeted channel partnerships.
Strategic implications for 2026
-
Portfolio prioritization: Segment product R&D into three investment tracks — (1) high‑value solutions for hybrids/commercial powertrains; (2) cost‑engineered platforms for price‑sensitive OEMs; and (3) aftermarket/remanufacturing channels. Allocate incremental R&D and capex to the first and third tracks where differentiated margin returns are clearest.
-
Regional footprint logic: Use a trade‑aware footprint strategy that balances proximity to OEM hubs with tariff exposure mitigation. Tactical local content strategies (including JV or licensing structures) will be decisive in preserving access to North American and Latin American programs subject to rules of origin.
-
Supply resilience and procurement: Move from transactional buying toward integrated supplier partnerships for critical metallic inputs. Implement multi‑sourcing plus strategic buffer inventories and renegotiated contractual terms to de‑risk input price volatility.
-
M&A and alliances: With concentration high among top suppliers, the most accretive deals in 2026 are either (a) bolt‑on acquisitions that add aftermarket/reman capabilities, or (b) geographic expansions into high‑growth commercial vehicle markets via local manufacturing or alliance structures.
-
Commercial model innovation: Introduce lifecycle pricing for remanufactured programs and explore subscription models for high‑usage commercial fleets to convert one‑time sales into recurring revenue streams.
What PW Consulting’s full report delivers (practical highlights)
-
Proprietary forecast model (2026–2032) calibrated to macro scenarios — includes baseline, upside, and downside demand paths, and stress testing for tariffs and material shocks.
-
Actionable segmentation analytics — a drillable framework across region, product type, and application that identifies where margins, volume growth, and aftermarket opportunity intersect. Note: detailed segment breakouts are available only in the full report to protect intellectual property and client value.
-
Supplier risk and opportunity matrix — supplier scores for scale, geographic exposure, technology breadth, and aftermarket reach that guide sourcing and partnership decisions.
-
Competitive playbooks — tailored strategies for market leaders, challengers, and niche specialists, including go‑to‑market moves, product roadmaps, and M&A priorities.
-
Deal tracker and program pipeline — verified contract awards, program start‑of‑production (SOP) timelines, and capex footprints to help you time investments and capacity commitments.
Competitive landscape — what to watch in 2026
The ecosystem is led by established global suppliers that combine scale manufacturing, integrated drivetrain portfolios, and OEM relationships. Key firms profiled in our study include Schaeffler Group (Germany), Valeo SE (France), ZF Friedrichshafen AG (Germany), BorgWarner Inc. (USA), Eagle Industry (Japan), Amsted Automotive Group (USA), and Eaton Corporation (Ireland). Each brings a distinct strategic posture and regional focus that shapes competitive openings.
-
BorgWarner: Rapid program wins and footprint expansion in China underscore an aggressive strategy to capture dual‑clutch and wet‑clutch volume with local manufacturing scale. For 2026, expect continued emphasis on transmission module partnerships and cross‑selling into adjacent drivetrain systems.
-
Valeo: Strengthening its remanufacturing credentials (recognized by industry awards) positions Valeo to monetize aftermarket demand. OEMs seeking lifecycle cost reductions will increasingly specify reman options — forcing suppliers to demonstrate reverse‑logistics capabilities and certified process control.
-
ZF: Winning large contracts for heavy‑duty clutches in high‑growth commercial markets highlights ZF’s playbook of localizing production and leveraging established OEM relationships. This makes ZF a preferred partner where local content and supportability matter.
-
Eaton, Eagle, Amsted and others: These firms emphasize targeted regional product portfolios (e.g., Asian truck clutches, one‑way clutches for transmissions) and can be attractive acquisition or JV partners for firms seeking rapid market entry without greenfield risk.
Recent verified developments (2025–early 2026) — including contract awards in China and India, industry recognition for reman programs, and targeted product launches — validate the structural themes above: suppliers are localizing capacity in growth geographies, aftermarket and reman initiatives are moving from pilot to scale, and commercial vehicle demand is a strategic growth lever.
How to convert insight into 2026 action — an executive checklist
-
Rebalance capex: Prioritize flexible lines that can switch between wet/dry and friction/non‑friction assemblies to protect against platform volatility.
-
Secure input supply: Lock in multi‑year contracts or index‑linked supply agreements for key metallics and components to limit cost leakage.
-
Pursue aftermarket scale: Invest in certified reman corridors and partner with logistics providers to shorten returns cycles and preserve quality yield.
-
Adopt modular product architecture: Reduce engineering-to-order complexity and enable faster OEM program wins with configurable platforms.
-
Plan M&A with precision: Target sellers with ecosystem fit (reman capabilities, regional capacity, or niche technology) rather than chasing headline scale alone.
Conclusion — why 2026 matters
2026 is a year of active choices: firms that align product roadmaps to hybrid/commercial opportunities, harden procurement against tariff and material risk, and scale aftermarket/reman capabilities will secure outsized returns in a market growing from USD 13.5 billion in 2025 toward about USD 19.1 billion by 2032 at a 4.8% CAGR. Because the competitive top end remains concentrated (CR3 ~65%; CR5 ~75%), strategic moves that combine operational resilience with localized presence and a clear aftermarket model will determine winners.
PW Consulting’s full Automotive Clutch Market report contains the quantitative segment breakouts, scenario models, supplier benchmarking, and executable playbooks that operationalize the insights summarized here. For the granular regional, type, and application breakouts, as well as the downloadable forecasting model and program tracker, access the full report at our publication portal.
For detailed analysis of this topic, please visit the official page: Automotive Clutch Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com