

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting: Trehalose Market Poised to Hit USD 275.0M by 2032 at 5.45% CAGR
By pmarketresearch, 2026-07-08
Trehalose Market 2026: Strategic Preview for C-Suites and Growth Teams
PW Consulting’s forthcoming Trehalose Market study positions decision-makers to move confidently into 2026. The trehalose market has transitioned from a niche specialty ingredient to a strategically important raw material across food, pharma, supplements and personal care. Our base-year analysis (2025) and seven-year forecast (2026–2032) synthesize historical performance, supplier economics, regulatory developments and commercialization levers so that commercial, procurement and corporate development teams can convert market signals into profitable actions.
Trehalose Market
Headline market trajectory
From a clearly identifiable recovery in the early 2020s, trehalose has recorded sustained expansion: PW Consulting estimates the global market increased from roughly USD 130.0 Million in 2020 to USD 190.85 Million in 2025. Looking ahead, the market is projected to grow at a compound annual growth rate (CAGR) of approximately 5.45% during the 2026–2032 forecast period, reaching roughly USD 275.0 Million by 2032. These headline figures reflect the combined effects of application-led demand (notably premium food and stabilizing pharma uses), diversification of supply routes, and incremental product innovation in formulation and processing.
Trehalose Market
Why this study matters for 2026 decision-making
- Timing: 2026 will be the inflection year for many strategic bets — new facility ramps, pharmacopeia-compliant supply commitments, and regulatory clarity in key markets. The supply-demand balance and pricing elasticity we model give executives the basis for capacity planning and long-term contracting.
- Cross-functional implications: Trehalose sits at the intersection of R&D (formulation benefits), procurement (feedstock and processing economics), regulatory affairs (food and pharma approvals), and sales (clean-label and premium positioning). Our study clarifies trade-offs and prioritization paths for each function.
- Scenario readiness: We provide scenario-based outcomes that translate macro assumptions into P&L and working-capital impacts — essential for boards and investors evaluating greenfield vs. brownfield expansion or M&A.
What’s inside the report (practical, executable content)
- Market size and historical trend analysis (2020–2025) plus granular forward-looking demand curves through 2032, with base-year calibration.
- Segment and channel architecture (product forms, application classes, regional frameworks) together with sensitivity testing — enabling custom “what-if” modeling.
- Supply-chain diagnostics: feedstock inputs, process technologies, conversion economics, CAPEX/OPEX benchmarks and time-to-market implications for new capacity.
- Regulatory and quality mapping for food and pharmaceutical use-cases, including pharmacopeial compliance pathways and label/claim constraints in priority jurisdictions.
- Competitive landscape and capability matrices: supplier profiles, production footprints, proprietary technologies, and route-to-market comparisons.
- Commercial playbooks: price/distribution strategies, customer segmentation, and go-to-market templates for ingredient producers and formulators.
- Investment and M&A scorecards: valuation levers, synergies, and due-diligence checklists tailored to targets in Asia, Europe, and North America.
- Risk and resilience framework: supply shocks, regulatory shifts, ESG metrics and mitigation actions with concrete KPIs.
- Appendices: data tables, methodology notes, primary interviews and a repository of regulatory citations.
Note: this preview intentionally omits detailed segment-level percentages and region/application breakdowns — the full intelligence package contains the granular split tables, primary-sourced pricing curves and scenario workbooks that clients use for operational and M&A decisions.
Trehalose Market
Competitive landscape — who to watch and why
The trehalose industry exhibits a moderate concentration profile: a small group of established suppliers hold a meaningful share of accessible capacity, while a broader set of regional producers competes on cost and proximity. The market’s concentration dynamics reward scale in capability (high-purity grades, low-endotoxin production for pharma) and investment in branded, standardized processes.
- Nagase & Co., Ltd. (Tokyo, Japan) — a strategic technology owner in the TREHA® brand, Nagase’s proprietary enzymatic starch-to-trehalose process is a differentiation vector. Their emphasis on high-purity trehalose tailored for food and beverage formulators makes them an attractive partner for co-developments and licensing arrangements (source: Nagase Food Ingredients).
- Shandong Fuyang Biotechnology Co., Ltd. (Pingyuan, Shandong, China) — a cost-competitive food-grade producer embedded in corn deep-processing networks. Their export orientation and integrated feedstock access are key competitive advantages when volume and price sensitivity dominate procurement decisions.
- Meihua Holdings Group Co., Ltd. (Langfang, Hebei, China) — a broad ingredient player supplying trehalose as a colloidal polysaccharide for freshness and quality retention. Meihua’s full ISO 14001 coverage highlights a parallel focus on operational sustainability (Meihua ESG Report, 2024), an increasingly material consideration for global buyers.
- Cargill, Incorporated (Minneapolis, USA) — as a major distributor and ingredient systems house, Cargill plays a pivotal channel role for bakery, confectionery and clean-label applications, enabling rapid customer access in North America and parts of Europe.
- Pfanstiehl (Waukegan, Illinois, USA) — differentiated by pharmacopeia-compliant trehalose (USP-NF, EP, JP, ChP), Pfanstiehl is the go-to for biopharma stabilization and cryopreservation uses, where regulatory-grade consistency and low endotoxin are non-negotiable (product information, 2026).
- Regional suppliers (e.g., Shandong Deshang, Changyi Longchang) — numerous manufacturers supply competitive volumes for food and ingredient markets. Their advantage lies in regional logistics, flexible MOQ, and localized commercial terms.
Regulatory and quality developments shaping 2026 moves
- Regulatory acceptance is advancing in major markets: Health Canada has communicated no objection to trehalose for human food applications (February 2025), reducing a critical barrier for North American commercialization paths.
- Pharma-grade certification and pharmacopeia listings (USP, EP, JP) are decisive enablers for higher-margin stabilization and cryopreservation segments; suppliers achieving these certifications command premium pricing and longer contract horizons (Pfanstiehl product information, 2026).
- Sustainability credentials — such as full ISO 14001 coverage — are becoming commercial differentiators for global retailers and ingredient buyers, and can materially influence supplier selection in RFPs (Meihua ESG Report, 2024).
Strategic implications and recommended actions for 2026
We translate market dynamics into concrete options executives should evaluate immediately. The recommended actions differ by role but cohere around three priorities: secure differentiated supply, capture premium applications, and harden commercial resilience.
- Procurement & Supply Chain
- Lock in staggered long-term contracts with tiered volume-price triggers to manage feedstock volatility and secure capacity for high-priority SKUs.
- Audit supplier capabilities against pharmacopeial and sustainability KPIs; qualify at least two independent sources for critical pharma and clean-label grades to minimize single-source exposure.
- R&D & Product Strategy
- Prioritize formulation projects where trehalose’s humectant, stabilization and freezing-point depression properties unlock premium claims (e.g., clean-label texture retention, biopharma stabilization).
- Co-invest in application trials with technology-holding partners (e.g., enzymatic process proprietors) to secure early access to next-generation grades.
- Commercial & Marketing
- Segment accounts by value capture: pursue bespoke pharma contracts and supply agreements for high-value formulators, while leveraging distribution partners for broad food and bakery penetration.
- Develop price cadence and promotional playbooks that preserve margin in an environment of periodic low-cost regional supply saturation.
- Corporate Development & Finance
- Evaluate tuck-in acquisitions in regions where feedstock integration or regulatory certifications are scarce — these deals can compress time-to-market for pharmacopeial grades.
- Use scenario P&L models to test CAPEX choices: a small biotech-grade line vs. scaling commodity volumes—each path has distinct payback and risk profiles aligned to different buyer segments.
- Regulatory & ESG
- Proactively engage regulators in key markets to accelerate acceptance for new applications and claims; maintain transparent ESG disclosures to meet buyer requirements.
Risks to monitor in 2026
- Feedstock price volatility and corn-processing throughput changes in major producing regions, which can compress margins during oversupply cycles.
- Regulatory shifts or delays in pharmacopeial recognition in target jurisdictions, impacting time-to-revenue for pharma-grade initiatives.
- New process entrants or capacity additions that alter regional pricing dynamics — our monitoring framework indicates windows of acute oversupply that require tactical response.
How PW Consulting helps executives convert insight into action
Clients use our study to calibrate three deliverables in the first half of 2026: (1) a supply and procurement playbook with contracting templates and cost-to-serve analysis; (2) a go-to-market plan for prioritized applications (food, pharma, supplements, personal care) with channel economics; and (3) an M&A pre-deal diligence pack including synergy capture models and de-risking checklists.
If your team must decide on capacity commitments, pricing architecture, or a targeted acquisition in 2026, our trehalose market model provides the scenario outputs, sensitivity ranges and supplier scorecards necessary for prudent, high-confidence decisions.
Next step
PW Consulting’s full Trehalose Market report contains the proprietary segment tables, regional and application-level forecasts, and the interactive scenario workbook that operational teams use to stress-test investment choices. For executives preparing strategic plans and budgets for 2026, the full dataset and playbooks are essential. Access the complete study and advisory services via our report landing page to receive the full intelligence package and schedule a custom briefing.
For detailed analysis of this topic, please visit the official page: Trehalose Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Transformer Oil Market to Hit USD 3,905 Million by 2032 at 6.5% CAGR
By pmarketresearch, 2026-07-08
Transformer Oil Market: Strategic Imperatives for 2026
As power systems evolve — driven by electrification, renewables, urbanization and tighter energy-efficiency mandates — the transformer oil market is moving from a commoditized backwater into a strategically important input for utilities, OEMs and industrial buyers. PW Consulting’s latest Transformer Oil Market study (base year 2025; forecast 2026–2032) synthesizes five years of historical behaviour with forward-looking scenario analysis to deliver the market intelligence executives need to set resilient, opportunity-focused strategies for 2026.
Transformer Oil Market
Macro snapshot you can act on
Our market model places the global transformer oil market at USD 2,530 Million in 2025, growing at a compound annual growth rate (CAGR) of 6.5% through the 2026–2032 forecast window, reaching roughly USD 3,905 Million by 2032. Those headline dynamics mask important second-order forces: raw material price volatility, regulatory tightening on energy performance and hazardous substances, and an accelerating shift toward ester, bio-based and circular fluids in specific high-value use cases. The full report translates this macro trajectory into decision-ready scenarios — from conservative procurement hedges to aggressive product and M&A playbooks — without exposing the proprietary segment-level data you’ll find in the paid study.
Transformer Oil Market
Why 2026 is a strategic inflection point
-
Regulatory acceleration: Since early 2025 the EU introduced stricter energy performance and greenhouse gas reduction requirements for transformers, raising the bar for dielectric fluids’ thermal and oxidative performance. Concurrently, legacy regulatory rules (for example, EPA TSCA requirements that require incineration for oils with PCB concentrations above specified thresholds) continue to impose disposal and remediation costs that change total cost of ownership calculations for older assets.
Transformer Oil Market -
Input-cost shocks and supply-side repricing: Base oil prices have shown renewed upward pressure — with reported US base oil prices around USD 1,842/MT in March 2026 — and crude volatility historically translating into rapid cost shifts. These dynamics compress margins on commodity mineral oils while improving the economics of premium, long-life fluids that lower lifecycle maintenance and replacement spending.
-
Market consolidation and buyer leverage: The market exhibits a moderate concentration profile (CR3 ~46.3%; CR5 ~61.2%), creating a structure where leading suppliers exert meaningful influence over product innovation, certification pathways and supply chain arrangements — but also where differentiated, sustainable products can carve premium niches.
Competitive landscape: where capability meets strategy
The competitive map is a mix of global majors with deep logistics and R&D footprints, regional specialists with application-specific expertise, and emerging leaders in sustainable fluids. Key supplier archetypes identified and profiled in the report include:
-
Innovation-led incumbents: European and multinational players have pushed premium grades, certification frameworks and circular initiatives. Recent commercial and deployment news underline this trend — for example, the uptake of circular transformer oils by OEMs and factory-level deployments in 2026 highlights how sustainability credentials are moving from pilot to production readiness.
-
Regional scale players: Large refiners and chemical groups supply base mineral grades at scale for domestic markets and exports, using integrated supply chains to preserve cost advantage. Their strength in price-sensitive segments coexists with an increasing focus on compliance and certification.
-
Niche specialists: Producers of natural esters and re-refined oils are building selective advantages in urban substations, offshore wind, and other fire-sensitive or sustainability-conscious applications. These suppliers often combine technical testing support with field qualification programs tailored to utilities and OEMs.
Full company profiles in the report unpack go-to-market strategies, technology differentiators, certification footprints and recent commercial developments for leading players — enabling buyers to match supplier capabilities to specific asset strategies and procurement levers.
Operational levers and strategic playbook for 2026
PW Consulting recommends a prioritized set of actions for corporate decision-makers, organized by horizon and informed by stress-tested scenarios in the full report.
-
Immediate (0–6 months) — Harden procurement and compliance. Implement hedging and flexible contracting tied to base oil indices; audit aging transformer fleets for PCB risk and disposal cost exposure; and fast-track qualification of at least one circular or natural-ester fluid as a pilot for high-value substations.
-
Near-term (6–18 months) — Shift product and capital allocation. Reallocate OPEX/CAPEX toward long-life fluids where lifecycle cost models justify higher unit prices; invest in in-situ testing capability; and establish recycling partnerships or off-take agreements with re-refiners to reduce disposal risk and capture circular premiums.
-
Mid-term (18–36 months) — Reconfigure supplier networks and M&A scouting. Pursue bolt-on acquisitions or strategic JV arrangements to secure niche ester or re-refining capability; renegotiate supply terms based on total-cost-of-ownership metrics; and embed regulatory scenario triggers into capital planning for new transformer builds.
Risk management and scenario analysis you can use
The report includes sensitivity matrices showing how +/-10–30% swings in base oil costs, varying adoption curves for ester fluids, and differentiated regulatory paths affect price, margin and NPV for buyers, suppliers and investors. It also provides a practical risk heatmap focused on supply disruption, regulatory penalties, certification delay, and reputational exposure from non-compliant disposal. These tools convert headline CAGR and market-size projections into actionable thresholds for contract clauses, inventory policy and capital allocation.
Actionable contents of the full study (high level)
-
Proprietary market model (2020–2025 historical; 2026–2032 forecast) with scenario toggles for price shocks, regulatory regimes and adoption curves for alternative fluids.
-
Supplier benchmarking and capability maps, including certification matrices, regional logistics strength and technical validation timelines.
-
Procurement playbook and sample contractual language for indexation, quality warranties and circular off-take agreements.
-
Lifecycle cost calculators and field-qualification protocols for mineral, synthetic and bio-based fluids.
-
M&A and partnership targets: screening criteria and shortlist derived from market concentration analytics and technology readiness levels.
-
Regulatory impact assessment covering PCB disposal rules, EU energy-performance measures, recent duty changes affecting trade flows, and recommended compliance pathways.
To honour the “preview” purpose of this article, we intentionally withhold proprietary granular splits and segment-by-region revenue tables; the full study includes detailed segmentation and quantitative matrices that power the tactical recommendations above.
Signals to watch in 2026
-
Certification and factory deployments: Major OEMs integrating circular and ester fluids into production lines will be an early indicator that field adoption is becoming de‑risked.
-
Raw-material and index behaviour: Sustained high base oil prices or renewed crude volatility will accelerate buyer interest in longer-life, higher-margin fluids.
-
Regulatory shifts: Any tightening of energy-performance or hazardous-waste rules materially changes lifecycle economics for legacy oils, increasing conversion activity.
-
Competitive moves: M&A by majors to acquire re-refining or ester capabilities will compress time-to-market for circular products and alter supplier bargaining dynamics.
What this means for executives
For procurement leaders, the decision calculus in 2026 must move beyond unit price to lifecycle value: qualification timelines, disposal costs, and supplier sustainability credentials will determine true TCO. For product and R&D leaders, allocating resources to ester and circular chemistry — plus the validation infrastructure to shorten qualification cycles — offers a high-return hedge against both regulation and raw material inflation. For corporate strategists and deal teams, the market’s moderate concentration suggests attractive pick-and-build opportunities to stitch regional scale to differentiated products.
PW Consulting’s Transformer Oil Market study converts the headline growth path (USD 2,530 Million in 2025 growing at 6.5% CAGR to 2032) into a clear sequence of choices: where to protect margins, where to innovate, and where to consolidate. The actionable tools in the full study — scenario models, procurement playbooks, supplier scorecards and target lists — are designed to be executed against a 2026 planning calendar.
Next steps
If you are preparing budgets, portfolio plans or acquisition screens for 2026, PW Consulting offers executive briefings and custom modelling workshops that use the report’s underlying data and scenario engines to produce bespoke recommendations for your asset base and strategic priorities. For access to the full segmentation, company profiles, and the quantitative annex that underpins the recommendations in this preview, please visit our report page or contact our industry team for a tailored briefing.
For detailed analysis of this topic, please visit the official page: Transformer Oil Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Cycle Computer Market to Grow at 6.98% CAGR to USD 344.8M by 2032
By pmarketresearch, 2026-07-08
Cycle Computer Market: Strategic Outlook for 2026 — A PW Consulting Brief
Executive summary
As cycling transitions from a recreational activity into a digitally mediated sport and mobility service, the cycle computer market is shifting from a hardware-dominant landscape to an integrated hardware–software–services economy. Our market model shows consistent expansion from the start of the last decade through 2025 and anticipates continued, above-market growth into the next planning cycle — underpinned by a compound annual growth rate of 6.98% across the forecast window. The market value measured in our 2025 base year demonstrates both resilience through 2020–2025 and a clear runway through 2032, with the 2026 inflection year marking a number of strategically significant choices for industry participants.
Cycle Computer Market
Why this report matters for 2026 decision-making
- Timing: 2026 is a pivot year for product refresh cycles, broadcast partnerships, and e-bike integrations. Firms that align roadmap investments in H1–H2 2026 will capture disproportionate share of incremental demand.
- Resource allocation: With revenue expanding year-on-year in our base curve, the report translates macro momentum into prioritized investments — product features, mapping/licensing, cloud analytics, and channel optimization — to maximize ROI.
- Competitive playbooks: The market remains relatively fragmented (low aggregated CR3/CR5 figures), creating opportunities for selective consolidation, brand partnerships, and targeted vertical integration. The research outlines which competitive moves are likely to generate asymmetric returns in 2026.
Market trajectory and key macro signals
Our long-form model tracks the market value from the historical window into a detailed 2026–2032 forecast. After a steady recovery and expansion from 2020 through 2025, the market enters a growth phase that is structurally supported by three durable trends: increased cycling participation and commuting adoption, accelerating e-bike penetration, and the monetization of route and training data through subscriptions and platform services. The projected CAGR of 6.98% reflects both these secular tailwinds and the rising willingness of consumers to pay for integrated experiences (hardware + cloud features + third-party integrations).
Cycle Computer Market
For executives planning 2026 budgets, this means there is a measurable and durable market expansion to underwrite R&D and commercial experiments — but success will hinge on differentiating around software ecosystems, accurate GNSS/mapping, and service-led monetization rather than purely incremental hardware improvements.
Cycle Computer Market
Competitive landscape — who matters and why
The vendor field is diverse, spanning global ecosystem incumbents, specialist hardware makers, and aggressive challengers from Asia and North America. Across this spectrum we see three dominant strategic archetypes:
- Full ecosystem incumbents: Companies that pair flagship devices with extensive cloud platforms, third-party integrations, and accessory ecosystems. Their advantage is lock-in via data continuity and cross-product benefits.
- Performance-specialist challengers: Brands focused on elite athletes and precision metrics (power, training load), winning loyalty through accuracy and tight integration with power meters and coaching tools.
- Value and OEM disruptors: Cost-competitive entrants and OEMs that bundle devices into bicycle and e-bike platforms, leveraging component synergies and channel relationships.
Representative players in each archetype include household ecosystem names with flagship GPS lines and broad sports platforms, focused mapping/navigation leaders emphasizing simplicity and UI responsiveness, endurance-optimized entrants offering ruggedized units for ultra-distance athletes, and a cohort of Asian suppliers rapidly upgrading hardware and closing gaps in software integration. Two recent partnership moves exemplify the market dynamics you need to consider for 2026 planning: Magene’s announced WorldTour partnership in January 2026 and iGPSPORT’s WorldTour agreement announced in late 2025. These actions underscore an intensifying strategy among mid-market brands to secure elite visibility and accelerate product credibility through pro-team alignments.
What this means for product and go-to-market strategy
- Product roadmaps must prioritize platform hooks. GPS accuracy, mapping depth, and low-latency sensor fusion (ANT+/Bluetooth/BT-SIG integrations) are table stakes; the differentiator will be how device data enables subscription services and partner integrations.
- Go-to-market should be segmented by channel economics: direct-to-consumer digital, specialty retailers, OEM/bike bundles and pro-team visibility. Each channel demands different packaging, warranties, and digital onboarding flows.
- Pricing architecture should shift to modular bundles. Consumers increasingly accept a hybrid model: an attractive device price combined with optional premium mapping/training subscriptions.
- M&A and partnership plays are actionable: target tuck-ins that supply key sensor or mapping capabilities, or commercial partnerships with teams and events to accelerate brand trust among high-value users.
Report deliverables — practical outputs for 2026 initiatives
Our Cycle Computer Market research is designed to be directly actionable for product, commercial, and corporate strategy teams. Key deliverables you will find in the full report include:
- Robust market sizing and a transparent forecasting engine with scenario variants for optimistic, base, and downside 2026 cases.
- Vendor-level profiles and capability matrices that assess ecosystem strength, software maturity, channel reach, and R&D momentum.
- Go-to-market playbooks for each channel type with suggested near-term investments, marketing KPIs, and churn-reduction tactics for subscription services.
- Technology watch and risk register covering GNSS, connectivity standards, display & battery trade-offs, and supply-chain concentration points.
- M&A screening filters and a prioritized list of inorganic targets (by capability gap), including integration timelines and estimated synergy ranges.
- Sample commercial partnership term-sheets, licensing models for mapping and navigation, and templates for pro-team engagement to maximize PR ROI.
- Case studies of successful product launches, sample A/B testing frameworks for firmware UX changes, and retailer activation pilots.
Operational implications — actions to prioritize in 2026
For executive teams finalizing 2026 plans, we recommend a three-track approach:
- Defend and deepen platform value: launch at least one subscription-bound feature that is exclusive to your ecosystem before Q4 2026. This raises switching costs and creates recurring revenue.
- Channel optimization: renegotiate OEM bundle economics to secure mid-pack placement in key e-bike models and roll out a streamlined direct-to-consumer onboarding that reduces return rates.
- Selective partnering and visibility plays: consider one high-visibility sponsorship or technical partnership (WorldTour or equivalent regional leader) to accelerate trust signals — the recent moves by two mid-market vendors illustrate the lift such deals can provide.
Market structure and consolidation outlook
Despite a healthy market expansion, industry concentration remains modest — the aggregate shares of the largest competitors do not approach monopoly levels. That fragmentation creates both risk and opportunity: risk because competitors can undercut on price or specialist features; opportunity because disciplined consolidation or capability acquisitions can generate outsized returns. For corporations evaluating M&A in 2026, the reward profile favors bolt-on acquisitions that rapidly improve software capabilities or mapping content, rather than large-scale hardware-only roll-ups.
Why PW Consulting — methodology and credibility
Our analysis integrates primary interviews across OEMs, retailers, and elite teams, proprietary device shipment triangulation, and a bottom-up build of TAM, SAM, and SOM for the forecast horizon. We model multiple demand channels, map supplier constraints, and stress-test scenarios against macro shocks (component furloughs, GNSS anomalies, and regulatory changes). The result is a pragmatic, execution-focused body of work intended to move your 2026 planning from hypothesis to action.
Next steps — where to get the missing intelligence
This brief intentionally surfaces strategic conclusions while withholding core segmentation matrices and precise channel-level revenue splits to preserve the value of the full study. If your 2026 planning cycle requires the granular segmentation, vendor scorecards, and downloadable forecasting models, access to the complete report provides the calibrated inputs for board decks, investor diligence, and product investment committees.
PW Consulting stands ready to support rapid mobilization: whether you need a half-day executive workshop to convert insights into a 90-day roadmap, a diligence package for an acquisition target, or a bespoke pricing simulation for subscription roll-outs in 2026.
For detailed analysis of this topic, please visit the official page: Cycle Computer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: PTZ Camera Market to Reach USD 4.85M by 2032, 9.8% CAGR (2026–32)
By pmarketresearch, 2026-07-08
PTZ Camera Market 2026 — Strategic Preview for Decision‑Makers
Executive summary
The PTZ (pan-tilt-zoom) camera market is in the midst of a structural growth phase driven by technology convergence, new certification regimes, and expanding use-cases across security, broadcast/production, and enterprise AV. Our base-year analysis (2025) shows the market has more than doubled in size since 2020 and, under our central scenario, will continue to expand at a compound annual growth rate of approximately 9.8% through a 2026–2032 forecast window. By 2032 the total market reaches a materially larger scale than today, creating a tactical window for hardware vendors, integrators, cloud-service providers, and strategic investors to accelerate market share gains or reposition portfolios around higher-value use-cases.
PTZ Camera Market
Why this research matters for 2026 decisions
- Timing is strategic: 2026 marks the inflection where AI-enabled features, higher-resolution sensors, and network-first architectures mature together. Decisions made now on technology roadmaps, certification priorities, and channel investments will determine competitive positioning for the remainder of the decade.
- Operational feasibility: Procurement cycles for large security and broadcast projects are lengthening; suppliers that can demonstrate certified interoperability and predictable total cost of ownership will win competitive tenders.
- Capital allocation: Given the market’s near-term growth trajectory, portfolio managers and acquirers need forward-looking scenario models (price erosion, component shortages, and regulatory risk) to de-risk M&A and product investment.
Market trajectory and macro picture
From 2020 through our base year 2025, the PTZ camera market experienced steady expansion as the adoption of IP-native architectures, streaming workflows, and remote monitoring accelerated. The research quantifies this growth and translates it into actionable projections across 2026–2032. The headline: a near-double-digit CAGR underpins a multiyear opportunity, but the growth is heterogeneous — concentrated in higher-resolution, software-enabled segments and use-cases that monetize recurring analytics and managed services.
PTZ Camera Market
Important framing for strategic planning:
PTZ Camera Market
- The market’s historical performance (2020–2025) provides a reliable baseline for capex and inventory planning.
- Our forecast scenario suite (conservative / central / aggressive) isolates sensitivity to component pricing, certification timelines, and enterprise spending cycles.
- Market concentration is moderate; incumbency offers advantages, but there is meaningful opportunity for specialized entrants and ecosystem plays.
Key technology and demand drivers
- AI and computer vision as a differentiator: Auto-tracking, auto-framing, and embedded analytics are shifting value from optics alone to software-defined functionality. Vendors integrating reliable edge AI into PTZ head units command higher ASPs and enable recurring revenue models for analytics subscriptions.
- Resolution, sensors and broadcast quality: The move to 4K and larger sensor formats for professional production use-cases is driving a bifurcation in product roadmaps — broadcast-grade systems with large sensors versus compact, networked PTZs optimized for streaming and conferencing.
- Network-native workflows: IP, NDI and multi-stream outputs are standard expectations for AV and broadcast buyers. Interoperability certifications (e.g., platform‑level room certifications) materially shorten deployment timelines.
- Regulatory and compliance inputs: Certification milestones (recent platform approvals and vendor certifications) are now commercial levers. Separately, material inputs — for example, stainless-steel components used in explosion‑proof assemblies — expose vendors to tariff and supply-chain risk that should be modelled in supplier contracts and cost projections.
- Wireless and edge connectivity: Rural/remote monitoring solutions that use LTE/5G and ruggedized PTZs are creating vertical pockets of higher-margin demand.
Competitive landscape — who matters and why
The PTZ ecosystem is populated by a mix of global incumbents, specialists focused on broadcast/AV, and security-first manufacturers. Market concentration is moderate: the top three players do not dominate the market, and the top five together leave substantial room for mid‑tier specialists and innovative entrants. Understanding the strategic intent of each cohort is critical for partnership and competitive planning.
- Broadcast & live-production specialists — Companies such as PTZOptics, Marshall Electronics, Bolin Technology, Canon, and Telycam focus on high-performance streaming and production workflows. Their differentiators include large sensors, 4K@60 capability, NDI support, and low-latency multi-output architectures. Recent product introductions and trade show wins in 2026 underscore ongoing investment in performance and AV integration.
- Security and surveillance leaders — Firms such as Hikvision, Dahua, Axis Communications, Pelco, Bosch, Honeywell, and VITEK bring deep channel penetration in perimeter and enterprise security. Their strengths lie in ruggedized designs, outdoor-ready enclosures, and integrated analytics. These vendors are evolving software ecosystems to lock in recurring revenues from analytics, cloud storage, and managed services.
- AV and conferencing vendors — Sony Electronics, Vaddio, AVer and similar players target corporate, education and medical use-cases with emphasis on certification (platform compatibility), low-latency streaming, and AI-framing. Certifications obtained in 2026 illustrate how interoperability is becoming a commercial gatekeeper for large-scale deployments.
- Specialty and vertical-focused vendors — TrueLook and other niche producers address jobsite and industrial monitoring through rugged, sometimes wireless solutions. These plays are characterized by differentiated distribution and recurring connectivity services.
Notable recent developments that inform competitive positioning:
- PTZOptics’ new product recognized at a major AV trade show in early 2026, signaling continued momentum in streaming and live-production segments.
- Sony’s 2026 InfoComm showcase emphasized AI auto-framing across new 4K models — a clear attempt to migrate broadcast-quality features into enterprise AV spaces.
- Bolin Technology and other broadcast-focused vendors exhibited larger-sensor, all-weather 4K60 PTZs at NAB 2026, indicating product-roadmap investments toward higher-margin professional production equipment.
- AVer’s platform certifications (multiple in early 2026) illustrate the commercial importance of third-party interoperability for enterprise buyers.
- Niche vendors continue to ship ruggedized LTE-enabled PTZs for remote monitoring, highlighting vertical pockets that remain less penetrated by mainstream suppliers.
Strategic implications & recommended actions for 2026
- For OEMs: Prioritize certified interoperability and edge-AI capability in next-generation SKUs. Reallocate R&D to differentiate software stacks and subscription services rather than only optical performance.
- For system integrators: Develop bundled service propositions (hardware + analytics + managed monitoring) and push for platform certifications to shorten sales cycles for large enterprise and public-sector tenders.
- For enterprise security buyers: Insist on supplier roadmaps that include long-term firmware support, security patching, and clear supply‑chain contingency plans for key components exposed to tariff volatility.
- For private equity / strategic investors: Target assets that combine hardware competence with software monetization potential or that fill vertical gaps (e.g., ruggedized wireless PTZs for remote industries).
- For procurement and operations leaders: Introduce contract clauses that address certification timelines, component price pass-throughs, and service-level guarantees to mitigate deployment risk.
What our full PTZ Camera Market report delivers (practical contents)
The complete PW Consulting study is purpose-built for executives who must convert market intelligence into operational decisions. Highlights include:
- Granular historical and forecast revenue models (by product class, application and country) with scenario sensitivity to component pricing and certification adoption rates (note: detailed segment tables and country-level figures are available in the full report).
- Supplier benchmarking and a vendor scorecard that assesses product capability, channel reach, certification maturity, and software monetization potential.
- Go‑to‑market playbooks for OEMs and integrators, including channel mapping, pricing strategies, and sample contract language for recurring services.
- Commercial models (ROI calculators) for common deployment types — security, broadcast, enterprise AV — enabling procurement teams to justify capex and Opex trade-offs.
- Supply‑chain heatmaps identifying tariff exposure (e.g., stainless-steel components used in explosion‑proof assemblies), single‑sourced modules, and logistics bottlenecks.
- M&A diligence toolkit: valuation proxies, integration risks, and a prioritized shortlist methodology for tuck-in and roll-up targets.
How to use this preview
- Use the macro growth figures and scenario insights as guardrails for FY2026 planning and 3‑year roadmaps.
- Align product roadmaps to the feature sets that attract higher lifetime value (edge AI, certification-ready networking, and multi-stream outputs).
- Prioritize vendor partnerships and certifications that shorten sales cycles for large enterprise and broadcast accounts.
- Leverage the full report’s operational tools (scorecards, ROI calculators, contract templates) to convert strategy into measurable actions within 90–180 days.
Conclusion — the strategic choice ahead
The PTZ camera market presents a clear growth runway, but success in 2026 will not be decided by optics alone. Vendors and buyers who align around certified interoperability, software-enabled value propositions, and resilient supply chains will capture disproportionate upside. PW Consulting’s full PTZ Camera Market report provides the granular forecasts, vendor intelligence, and executional toolkits necessary to translate the macro growth thesis into defensible, near-term actions.
For a deeper dive into the segmented forecasts, vendor scorecards, and deployment playbooks that underpin this preview, access the complete PW Consulting PTZ Camera Market study on our website or contact your PW Consulting advisor to schedule a briefing.
For detailed analysis of this topic, please visit the official page: PTZ Camera Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Polypropylene Pipes market to reach USD 217.22M by 2032 at 3.9% CAGR
By pmarketresearch, 2026-07-08
Polypropylene Pipes Market: Strategic Outlook to 2026 — An Executive Preview
As PW Consulting’s senior industry analyst, I present a focused strategic primer on the polypropylene (PP) pipes market — an asset-light, engineering-centric sector that will demand measured capital allocation and sharper commercial playbooks by 2026. This preview synthesizes the market’s macro trajectory, competitive dynamics, regulatory and supply-side shocks, and the practical levers that executives must prioritize to convert modest growth into disproportionate competitive advantage. The full dataset, segmented analyses and proprietary models that underpin these conclusions are available in our published report.
Polypropylene Pipes Market
Why this market matters in 2026
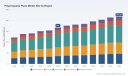
Polypropylene piping has evolved from a niche polymer alternative into a mainstream engineering choice for building services, potable networks and several industrial uses. The market’s macro posture is characterized by steady, investment-grade expansion rather than boom-and-bust volatility. After recovering from earlier cycles, global market revenue grew from roughly USD 122.0 million in 2020 to USD 168.0 million in our 2025 base year. Our forecast horizon (2026–2032) assumes a compound annual growth rate (CAGR) of about 3.9%, with the market reaching approximately USD 217.2 million by 2032.
Polypropylene Pipes Market
For corporate leaders and investors making decisions in 2026, this context matters because it signals a business environment where operational efficiency, product differentiation and channel execution — not merely volume scale — will drive returns. That translates into different capital priorities: targeted automation, selective geographic expansion, higher-margin system solutions (product + service), and disciplined M&A rather than broad-based capacity chasing.
Polypropylene Pipes Market
What the market dynamics are telling us
-
Steady demand backdrop. The historical series shows consistent expansion rather than episodic spikes. That steadiness favors companies that can optimize cost curves and build repeatable project pipelines (residential refits, commercial retrofits, and specified industrial projects).
-
Raw material tailwinds — short term. PP resin prices are expected to remain weak or broadly stable in the near term due to ample supply and balanced demand. Firms should use this window to secure multi-year procurement contracts or hedging structures to lock in margins ahead of potential feedstock tightening.
-
Regulatory and standards pressure. Compliance with pressure-piping standards (e.g., DIN 8077 / DIN 8078 in a number of markets) remains a gating factor for specification in institutional projects and large contractors. Certification timelines can materially affect go-to-market cadence for new products.
-
Installation productivity is a differentiator. Fusion welding technology reduces installation times versus traditional joining systems — a winner-take-most feature for projects where labor cost or speed matters (high-rise, MEP retrofit, rapid-deploy modular buildings). Suppliers who couple product training and certification for installers can convert better than purely price-based competitors.
-
Acceptance in potable and heating systems. Broad approvals for potable water and heating systems under many plumbing codes create a base-level market access; however, project-level specifications still hinge on legacy relationships and documented long-term performance.
Report coverage — pragmatic contents designed for 2026 decisions
Our full study is intentionally operational. Rather than a descriptive catalogue, it supplies a playbook for action across five decision horizons:
-
Near-term (0–12 months): Procurement playbook for PP resin, SKU rationalization for immediate margin lift, and quick-win process improvements on warehousing and logistics.
-
Medium-term (12–36 months): Product portfolio moves (e.g., fiber-reinforced variants, system-level solutions), targeted certification roadmaps to access regulated projects, and installer training programs to accelerate adoption.
-
Growth-led (36–60 months): Channel expansion frameworks, selective greenfield and brownfield investments, and integration scenarios for bolt-on M&A.
-
Risk and resilience: Scenario-based stress tests for feedstock shocks, regulatory shifts, and contractor labor volatility; contingency supplier maps and inventory buffer sizing.
-
M&A and partnership playbook: Target screening criteria, valuation heuristics tuned to the segment’s thin consolidation (low top-three share), and integration checklists to capture synergies from combined sales networks and spec-engineering capabilities.
The report blends quantitative models (price sensitivities, demand elasticities, and cash-flow scenarios) with actionable templates: sample supplier contracts, a certificate-timeline checklist for major standards, installer training curriculum outlines, and a 100-day integration plan for acquisitions.
Competitive landscape — who matters and why
The polypropylene pipes market remains fragmented: the top-three firms account for roughly 22.5% of market volume, while the top-five account for about 25.8%. That fragmentation creates openings for regional champions and product-specialist players to scale profitably through focused execution.
-
Aquatherm (Attendorn, Germany) — Known for PP-RCT and PP-R systems aimed at pressurized heating, cooling and plumbing. Strengths: established installer certification programs and product range tailored to mechanical contractors; risk: premium positioning in markets sensitive to price.
-
Georg Fischer Piping Systems (Schaffhausen, Switzerland) — Offers a broad PP-R and PP-RCT portfolio for potable and industrial networks. Strengths: global project experience and engineering support capabilities; opportunity: leverage industrial project pipeline to push system solutions.
-
Bänninger Kunststoff-Produkte GmbH (Germany) — Produces PP-R and PP-RCT fittings and pipes targeting drinking water and industrial uses. Strengths: precision manufacturing and strong OEM relationships; caution: scale limitations against global players.
-
Pipelife (Vienna, Austria) — Focused on hygienic hot/cold drinking water distribution systems. Strengths: product hygiene certifications and distribution reach in select European markets; path forward: expand into integrated building service contracts.
-
REHAU (Germany) — Broad building-services focus including fiber-reinforced PP-RCT options. Strengths: material innovation and building integration solutions; strategic imperative: monetize product innovation through specification partnerships with large contractors and system integrators.
Across this competitive set, winners to 2026 will be those that can convert product approvals and installation advantages into repeatable, contract-level share. That requires tighter collaboration with contractor groups, digital training platforms for fusion welding, and commercial models that shift some value capture from commodity pipe to engineered sub-systems.
Strategic implications and recommended moves for 2026
-
Lock in feedstock advantage. With resin prices subdued in the near term, secure multi-year supply or financial hedges to protect gross margins. Use scenario analysis in our report to quantify margin movement under ±15% resin swings.
-
Prioritize certification and time-to-specification. Institutional tenders and large contractors prize standards compliance and documented timelines. Fast-track DIN-equivalent certifications and map the approval lead times in priority markets.
-
Monetize installation productivity. Invest in installer training and certified fusion welding programs; sell system warranties and performance guarantees that capitalize on faster and more reliable joints.
-
Product + service bundles. Move up the value chain by offering design-assist, prefabricated assemblies and commissioning support—particularly in retrofit and modular projects where speed and coordination deliver premium pricing.
-
Targeted M&A and partnerships. Given the market’s low top-three concentration, bolt-on acquisitions that add engineering services, regional distribution or certification-ready product lines can compound returns faster than large-scale greenfield capacity plays.
-
Operationalize sustainability messaging. While life-cycle performance is not a standalone growth engine yet, suppliers that credibly reduce embodied carbon and improve recyclability will have an advantage when buyers include environmental metrics in tender scoring.
How PW Consulting’s study supports tactical 2026 choices
The full PW Consulting study provides the tactical scaffolding needed to execute the moves above: audited market-sizing (history and forecast), a procurement stress-testing tool, a regulatory compliance timeline by market, installer uptake models (fusion welding adoption curves), and a prioritized target list for M&A with modeled synergy capture rates. Importantly, while this preview outlines the strategic narrative, the granular segment tables, indexed regional demand drivers and confidential company-level revenue splits are intentionally withheld here — they are contained in the full report to preserve competitive value and ensure you have the evidence you need for board-level decisions.
Concluding perspective
By 2026, the polypropylene pipes industry will reward disciplined operators who translate steady market growth into higher-margin system sales, tighter procurement, and installer-centric commercial models. The market’s moderate CAGR and fragmented competitive structure mean that structural advantages — certification speed, fusion-welding adoption, and channel depth — will create sustainable differentiation. Executives preparing capex budgets, M&A pipelines or commercial strategies should orient around those levers now.
For an executive-ready set of tools — scenario models, segment-level forecasts, supplier scorecards, and a 100-day M&A integration playbook — consult the full PW Consulting polypropylene pipes market report. The detailed tables and proprietary subsegment analytics provide the concrete inputs needed to translate the strategic imperatives outlined here into decisive 2026 actions.
For detailed analysis of this topic, please visit the official page: Polypropylene Pipes Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: EVC Market to Reach USD 81.57B by 2032 with 18.12% CAGR
By pmarketresearch, 2026-07-08
Electric Vehicle Charger (EVC) Market 2026: Strategic Imperatives for Corporate Decision-Makers
Executive summary
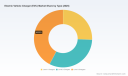
The EVC market is no longer an emerging niche — it has entered a structural growth phase that will reshape energy systems, mobility business models, and capital allocation decisions over the next decade. Our market model shows a clear trajectory: the global market expanded from USD 4.82 Billion in 2020 to USD 25.55 Billion in 2025 and is projected to reach USD 81.57 Billion by 2032, driven by an 18.12% compound annual growth rate (CAGR) across the 2026–2032 forecast window. For corporate leaders planning investments, partnerships or new product launches in 2026, this report is designed to translate the numbers into executable strategy — while reserving the granular segmentation tables and proprietary scenarios for subscribers and website visitors.
Electric Vehicle Charger (EVC) Market
Why this study matters for 2026 decisions
-
Timing is strategic: 2026 is a pivot year. Many policy, manufacturing and grid-integration initiatives launched in prior years will converge into operational-scale deployments in 2026–2028. Executives who align product roadmaps and channel strategies to this timing capture outsized returns.
Electric Vehicle Charger (EVC) Market -
Macro growth with concentrated execution challenges: strong aggregate expansion masks complex operational constraints — from site acquisition and permitting to uptime enforcement and local content rules. The ability to translate market growth into dependable, high-utilization revenue streams will separate winners from the rest.
Electric Vehicle Charger (EVC) Market -
Capital and partnership design: the financing of charger rollouts is evolving from capex-heavy proprietary models to hybrid structures that blend subsidies, tax incentives, performance contracts and grid-support revenues. The report provides practical frameworks for structuring these deals in 2026.
Market trajectory — what the headline numbers imply
Our base-year calibration (2025) anchors the model and illustrates a multi-year acceleration: after a period of rapid adoption from 2020–2022, the market consolidated in 2023–2025, establishing scalable supply chains and clearer deployment economics. The projected increase to USD 30.3 Billion in 2026 and the sustained growth to USD 81.57 Billion by 2032 reflect multiple, concurrent demand drivers — vehicle electrification rates, public and private charging investments, and the monetization of grid services through bidirectional and battery-integrated systems.
Critically, aggregate growth does not guarantee distributed profitability. Our analysis shows that revenue pools will shift between fast DC charging, managed AC deployments, residential installations and public hubs depending on regulation, utility tariffs and real-world utilization. This is why 2026 strategies must be differentiated by vertical (fleet, retail, residential) and by monetization model (paid charging, subscription services, grid services), rather than assuming uniform uptake.
Strategic implications by stakeholder
-
OEMs and hardware manufacturers: prioritize modular, software-updatable platforms that enable rapid power-scaling and remote diagnostics. Customers in 2026 will expect future-proofing — not legacy fixed-output units. Manufacturing footprint decisions must now factor in evolving trade and local content rules.
-
Charging network operators and site hosts: focus on uptime economics and integrated payment/roaming stacks. Regulatory regimes are moving towards strict reporting and uptime thresholds; operational reliability will be a competitive moat.
-
Utilities and grid operators: design tariffs that reward flexible load and enable co-optimized investments in distribution reinforcements and behind-the-meter storage. Grid-interactive charging solutions present a pathway for non-wires alternatives to accelerate charger density without prohibitive distribution upgrades.
-
Investors and financiers: structure capital with performance tranches linked to availability, energy throughput and ancillary service participation. The report includes valuation templates that stress-test portfolios against realistic uptime and utilization scenarios.
Competitive dynamics — mapping capabilities and recent moves
The market remains moderately fragmented, with leading players demonstrating differentiated strategies across hardware power, software, and manufacturing footprints. Measured concentration metrics show top-three share and top-five share that indicate room for consolidation and alliance formation rather than immediate monopoly formation.
-
XCharge — Specializes in high-power DC fast charging and integrated battery solutions. Its strategic expansion into European assembly capacity in 2026 signals an ambition to reduce lead times for high-power units and to position GridLink-enabled products in public fleet and hub deployments. For corporates, XCharge highlights the importance of aligning product roadmaps with regional manufacturing strategies to mitigate logistics risk.
-
Kempower — Known for modular DC fast chargers and scalable power modules suited for public hubs and heavy-duty applications. Its partnership activity in early 2026 underscores a broader industry trend: interoperability and simplified payment integration are becoming table stakes. OEMs that package modularity with open ecosystem integrations will unlock larger deployment pipelines.
-
Enphase Energy — Bringing bidirectional charging to market linked with distributed energy assets such as solar and storage. The move into volume production timelines in late 2026 suggests that vehicle-to-home and vehicle-to-grid capabilities are transitioning from pilot to commercial deployments, creating new value streams for residential customers and aggregators.
Regulation, incentives and operational constraints — immediate priorities
Policy developments in the U.S. and elsewhere introduce both risks and opportunities that should be modeled in 2026 strategy workstreams:
-
Operational reliability is becoming a regulatory obligation. New standards require frequent reporting of charger inventory and uptime for commercial operators and set minimum uptime benchmarks for recently installed equipment. Compliance will necessitate investment in monitoring, service provisioning and SLA enforcement.
-
Local content and procurement rules are tightening in key markets. Proposed modifications to domestic manufacturing requirements will alter sourcing economics for projects obligated after specific policy effective dates — accelerating decisions on where to locate final assembly and which BOM components to domesticize.
-
Tax credits and residential incentives remain a force-multiplier for EV charger adoption. Residential incentives can lower acquisition costs and accelerate managed-charging adoption if coupled with smart home or V2H products.
What our report contains — practical deliverables for 2026 action plans
This study is built to be a decisioning tool. Subscribers receive:
-
Market sizing and a demand model from 2020–2032 with scenario toggles for vehicle adoption, utilization rates and policy shifts.
-
Commercialization playbooks for major verticals (public hubs, retail, workplace, fleets, multifamily and single-family residences) including go-to-market timelines, margin profiles and procurement checklists.
-
Competitive landscaping with capability matrices, M&A/red team playbooks and supplier risk assessments.
-
Regulatory impact models mapping uptime, reporting and local-content policies into P&L and deployment feasibility outcomes.
-
Operational templates: uptime SLAs, remote diagnostics ROI calculators, and field-service cost models tailored to charger classes and use cases.
-
Investment scenarios and valuation models designed for financiers and corporate development teams to stress-test acquisition targets and joint-venture structures.
How to use this research in 90–180 day planning cycles
-
90 days — Rapid alignment: run the base and downside scenarios against your planned 2026 rollouts, update supplier agreements to reflect potential local-content requirements, and accelerate pilot deployments for uptime validation.
-
180 days — Scaling and capitalization: finalize manufacturing footprints, negotiate performance-linked financing, and lock down partnerships for payment, grid services and site-hosting. Use the report’s procurement playbook to de-risk tender responses and public bids.
Final note — what we intentionally hold back (and why)
Consistent with our “trailer” approach, this introduction demonstrates the report’s analytical depth and practical focus while reserving detailed segment-level tables, downloadable models, and proprietary vendor scoring for the full study. Those detailed data layers — including regional and application splits, full unit economics, and downloadable scenario models — are accessible on our website and are critical for transaction-level decision-making in 2026.
Next steps
For corporate strategy teams, investor groups, and product leaders preparing to make or defend 2026 commitments, we recommend ordering the full report to acquire the complete dataset, customizable models, and the supplier playbooks that translate strategy into executable plans. Contact PW Consulting via the source page to access the full intelligence package and schedule a briefing with our senior analysts.
For detailed analysis of this topic, please visit the official page: Electric Vehicle Charger (EVC) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Loading Dock Equipment Market Poised for 5.73% CAGR Through 2032
By pmarketresearch, 2026-07-08
Loading Dock Equipment Market: Strategic Preview for 2026 Decision-Makers
As PW Consulting’s Senior Strategy Advisor and Lead Industry Analyst, I present a forward-looking synthesis of our Loading Dock Equipment Market study — a practical briefing designed to inform executive decisions in 2026. This preview distills the high-level trajectory, competitive dynamics, regulatory inflection points, and the actionable playbook senior leaders should use to prioritize investments, partnerships, and operational changes over the coming planning cycle. It deliberately demonstrates analytical depth while reserving the granular segment-level tables and proprietary supplier scores for the full report.
Loading Dock Equipment Market
Why this market matters in 2026
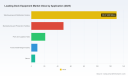
The loading dock equipment market is transitioning from a commoditized hardware space into a solutions-driven ecosystem where safety compliance, uptime guarantees, lifecycle services, and digital integration determine value capture. From 2020 through our base year of 2025 we observed steady demand growth; aggregate market revenues increased from the low hundreds of millions (USD, Million) to an estimated USD 215.0 Million in 2025. Our forecast period (2026–2032) projects sustained expansion at a compound annual growth rate (CAGR) of 5.73%, with the market moving toward an anticipated USD 344.8 Million by 2032.
Loading Dock Equipment Market
These macro dynamics create meaningful opportunities for manufacturers, systems integrators, facility operators, and capital allocators. The growth is large enough to justify strategic initiatives — from R&D in automated dock components to M&A aimed at building comprehensive service platforms — yet concentrated enough that incumbent players can preserve margins through differentiation and aftermarket services. Our market concentration analysis shows a moderately consolidated landscape: the top three vendors control roughly one-third of the market, while the top five account for just under half. This structure encourages both competitive positioning and targeted consolidation strategies.
Loading Dock Equipment Market
Key market drivers and headwinds
- Safety and regulatory pressure: Tightening safety oversight is a direct demand driver for upgraded dock solutions. For example, OSHA’s continued enforcement stance on open-sided dock guarding (OSHA 29 CFR 1910.23) remains a material consideration for capital planning and compliance-driven retrofits in 2026 and beyond.
- Operational resilience and labor economics: The push to maximize throughput with smaller labor pools is accelerating interest in mechanized and semi-automated dock technologies, intelligent controls, and service contracts that guarantee availability.
- Lifecycle monetization: Manufacturers are increasingly monetizing post-sale touchpoints — maintenance, predictive analytics, and extended warranties — which shift revenue mix from project-driven to annuity-like streams.
- Supply chain and raw material pressures: Component lead times and steel price volatility create both cost challenges and opportunities to re-engineer product families for modularity and local sourcing.
What the PW Consulting report delivers
This study is built for operational leaders and corporate strategists who need to move from awareness to action in 2026. The full deliverable contains:
- Detailed historical market sizing (2020–2025) and a seven-year forecast (2026–2032) in USD Million, anchored to our base year of 2025.
- Segment-level demand analysis across type, application, and region, with growth vectors and adoption curves for each segment (teaser: the report maps where retrofit demand outpaces new-build demand and why).
- Supplier benchmarking and capability matrices assessing product breadth, aftermarket capabilities, digital maturity, and go-to-market strength.
- Commercial playbooks for OEMs, distributors, and end-users: pricing strategies, service package design, channel optimization, and retrofit vs. replacement decision frameworks.
- Scenario planning and sensitivity analysis: stress-testing outcomes against macro shocks (steel price shocks, labor disruptions, and regulatory changes).
- Practical checklists and procurement templates to accelerate RFP cycles and shorten vendor evaluation time.
Note: This preview is intentionally non-exhaustive. Specific regional splits, application breakdowns, and supplier-level market shares are withheld here to protect the proprietary analyses included within the full report.
Competitive landscape — strategic takeaways
The competitive set includes long-established dock equipment OEMs, specialized lift and leveler manufacturers, integrated door and dock systems providers, and regional service specialists. Key industry participants exhibit a range of strategic postures:
- Full-solution integrators — firms with combined dock leveling, door systems, seals, and controls emphasize integrated uptime contracts and single-point accountability, which is attractive to large distribution centers seeking supplier consolidation.
- Product-specialist OEMs — manufacturers that focus on a narrow product line tend to lead in engineering depth and cost-competitive designs. Their edge lies in targeted innovation and scale on core SKUs.
- Aftermarket and service players — companies with dense field service networks convert installed bases into recurring revenue through maintenance, emergency repairs, and retrofit programs.
- Regional challengers — players with tight local distribution leverage speed-to-site and localized customization to win mid-market accounts against larger national brands.
Several named firms in the ecosystem demonstrate these archetypes. Some players are advancing programmable controls and remote monitoring; others compete on heavy-duty hydraulic and mechanical reliability. The result is a market where product differentiation, service economics, and channel reach determine long-term value capture more than raw manufacturing scale.
Strategic actions for 2026 — what executives should prioritize
For leadership teams deciding where to deploy capital and management attention in 2026, we recommend a three-track approach: Protect, Pivot, and Platform.
- Protect core value: Prioritize investments that defend existing revenue — e.g., bolster parts availability, accelerate field service digitization, and institute uptime SLAs for large accounts. Contractual guarantees combined with performance-based pricing are powerful retention levers.
- Pivot toward higher-margin services: Convert one-time transactional sales into recurring service revenues. Develop tiered maintenance packages, predictive service offerings using simple IoT telemetry, and retrofit bundles that address prevailing safety and compliance needs.
- Build platform capabilities: Where feasible, create interoperable control platforms and APIs that tie dock equipment into warehouse management systems and facility monitoring layers. Platforms increase switching costs and create data-driven upsell opportunities.
Operationally, procurement teams should accelerate lifecycle cost modeling (not just CAPEX) and insist on supplier transparency for mean time to repair (MTTR), parts availability, and embedded safety features. Investor and corporate development teams should screen targets that enhance service networks or add modular product technology, rather than acquiring undifferentiated manufacturing scale.
Risk and compliance lens
Regulatory enforcement is a persistent and non-obvious risk. OSHA requirements around guarding for open-sided dock areas are not just compliance checkboxes — they drive capital spending cycles and create windows for repurchase or retrofit. Facility operators must reconcile short-term budget constraints with the cost of non-compliance, downtime, and worker safety exposure. The report models the timing and size of compliance-driven demand under multiple enforcement scenarios, enabling procurement committees to plan capital appropriations accordingly.
How to use the full report for 2026 planning
Executives should treat the full report as an operational playbook rather than a passive market summary. Practical ways to use the analysis include:
- Benchmarking RFPs against supplier scorecards and validated lead-time baselines.
- Designing aftermarket service tiers with modeled margin impacts and churn assumptions.
- Prioritizing retrofit projects by ROI and regulatory exposure, using provided decision matrices.
- Screening acquisition targets with the included financial proxies and integration risk checklists.
The full deliverable includes downloadable tools and templates to speed decision cycles, from procurement checklists to a scenario-based capex prioritization spreadsheet.
Conclusion — the strategic horizon to 2032
By 2032 the loading dock equipment market is forecast to be materially larger than in 2025, underpinned by steady compound growth. That trajectory rewards firms that act now to capture durable service revenues, embed digital capabilities, and commercialize compliance-driven upgrades. The market’s moderate concentration means both incumbents and well-capitalized challengers can find profitable niches; success will hinge on execution — field service excellence, predictable supply chains, and product-roadmap alignment with safety and automation trends.
This preview is intended to accelerate your 2026 planning. For the complete segment-level analytics, supplier-specific benchmarking, pricing matrices, and the downloadable playbooks and templates referenced throughout, please consult the full PW Consulting Loading Dock Equipment Market report available via our website.
For detailed analysis of this topic, please visit the official page: Loading Dock Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Industrial Brakes Market to reach USD 1,961.21M by 2032 at 4.4% CAGR
By pmarketresearch, 2026-07-08
Industrial Brakes Market 2026: Strategic Preview for Executive Decision‑Making
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present a concise but substantive preview of our upcoming Industrial Brakes Market study — designed specifically to inform capital allocation, product strategy, and go‑to‑market decisions during 2026. This briefing highlights the macro trajectory, regulatory inflection points, competitive posture, and immediate strategic levers executives should prioritize. The full study contains the granular regional, type and application splits, detailed financial tables, and an interactive forecasting model; this article intentionally withholds those subsegment tables to preserve the report’s role as the single source of truth for tactical planning.
Industrial Brakes Market
Market trajectory: a steady, investible growth path
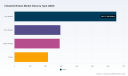
The Industrial Brakes market has demonstrated resilient expansion through the early 2020s and enters 2026 from a position of structural growth. Using 2025 as our base year, the market increased from USD 1,200.0 Million in 2020 to USD 1,454.4 Million in 2025. Our scenario-driven forecast for the 2026–2032 period projects a compound annual growth rate (CAGR) of 4.4%, with the market rising to approximately USD 1,961.2 Million by 2032 under the central case.
Industrial Brakes Market
What this trajectory means for 2026 planning: the sector is not in hyper‑growth mode, but it is predictable and sufficiently large that focused investments (product upgrades, aftermarket expansion, targeted M&A) can reliably move the needle. Organizations that treat 2026 as a year to optimize cost‑to‑serve, accelerate strategic partnerships in high‑value OEM segments, and capture aftermarket share will convert steady top‑line growth into outsized margin improvement.
Industrial Brakes Market
Why 2026 is a pivotal year
- Regulatory inflection. The Packaging and Packaging Waste Regulation (PPWR 2025/40) entered into force in February 2025 and will generally apply from August 12, 2026. The regulation — together with expanding EPR (extended producer responsibility) registers and compliance frameworks in multiple jurisdictions — alters packaging downstream behavior, influencing capital expenditure cycles for packaging machinery and the associated demand for industrial brakes.
- Shifts in input costs. Raw material pricing dynamics are reducing near‑term inflationary pressure: the Producer Price Index for plastic materials and resin registered a material decline into 2026. That creates a window in 2026 where BOM (bill of materials) cost reductions can be converted into improved margins, strategic price repositioning, or reinvestment in product features (e.g., lighter alloys, corrosion treatments, or sensor integration).
- Compliance timing in major markets. In the United States, state‑level EPR laws are moving toward compliance deadlines in spring 2026. Packaging OEMs and converters will reassess supplier contracts, total cost of ownership, and after‑sales service models — a strategic opening for brakes suppliers to negotiate embedded service agreements.
Competitive landscape and concentration
The market exhibits moderate concentration: the combined share of the top three firms sits near the mid‑50s percent range, while the top five capture just over 60 percent. These metrics point to an industry where leading vendors enjoy meaningful scale advantages and channel reach, but where focused challengers with differentiated technology or vertical specialization can still secure attractive niches.
Our competitive synthesis spotlights three players that exemplify distinct strategic postures:
- Regal Rexnord (Warner Electric™ & Stearns™ offerings) — Leveraging broad distribution and deep OEM relationships in packaging machinery, Regal Rexnord’s recent participation at PACK EXPO International 2026 reinforced its go‑to‑market strength in the packaging sector. Expect continued emphasis on integrated brake and clutch systems bundled with engineering support for OEM line integration.
- Coremo Ocmea — A European specialist with strong credentials in pneumatic caliper brakes and modular solutions for converting and packaging lines. Coremo’s modular approach enables rapid customization and short lead times — an important commercial differentiator where customers demand frequent configuration changes.
- Stearns — Known for spring‑set, power‑off electric motor brakes and clutches tailored to industrial packaging equipment, Stearns competes on reliability and aftermarket serviceability. Their product profile aligns well with OEMs that prioritize safety certifications and predictable downtime metrics.
These profiles illustrate the two dominant strategic axes in this market: scale and systems integration versus modular specialization and service intensity. Each axis yields different margin profiles and capital requirements; our full report maps those trade‑offs against buyer archetypes and procurement cycles.
Operational and commercial implications for 2026
- Prioritize compliance‑enabled offerings. With PPWR and EPR timelines converging in 2026, brakes suppliers should develop compliance‑aligned product messaging and service packages for packaging customers. This includes lifecycle reporting, take‑back/repair options, and documentation that supports producer registers.
- Capture aftermarket economics. Aftermarket service remains a durable margin pool. Companies should evaluate subscription models (predictive maintenance, condition monitoring) and bundling strategies that tie hardware sales to multi‑year service contracts.
- Exploit temporary input cost tailwinds. The decline in plastic/resin PPI in 2026 gives suppliers a narrow margin arbitrage. Use this to invest in product differentiation (sensorization, lightweight materials) or selectively fund customer incentives that lock in OEM partnerships.
- Rebalance supply chains. The combination of regulatory cost shifts and raw material volatility recommends a diversified supplier base and hedging strategies for critical components — particularly electronics and specialty alloys used in high‑end braking systems.
- M&A and partnerships. Given the industry’s moderate concentration, 2026 is an opportunistic year to evaluate bolt‑on acquisitions that deliver complementary technologies (modularity, electronic controls) or to secure regional market access through targeted deals.
What the PW Consulting report delivers (practical tools for immediate action)
PW Consulting’s Industrial Brakes Market study is built around decision‑grade outputs that executives can use in 2026 planning cycles. Highlights include:
- Multi‑scenario demand forecasts (central, upside, downside) from 2026–2032 with sensitivity levers for regulatory shifts and input price variance.
- Competitive benchmarking matrices that score vendors on product breadth, channel coverage, aftermarket capability, and integration readiness — enabling quick identification of acquisition targets or alliance partners.
- Regulatory impact models that translate PPWR and EPR obligations into OEM capex timing and incremental cost of compliance for packaging lines — actionable for contract negotiations and product roadmaps.
- Supply‑chain heat maps and a supplier risk index for critical inputs, with prescriptive sourcing strategies and contingency playbooks.
- Go‑to‑market playbooks for three buyer archetypes (OEM integrators, large converters/packagers, and aftermarket service buyers), each containing pricing tactics, commercial KPIs, and a 12‑month rollout plan.
- An interactive Excel model and slide kit that can be rebranded and used directly in board briefings or investment committees.
Risk register and early warning signals
Every strategic plan must be stress‑tested. Our study compiles a concise risk register with monitoring thresholds and recommended mitigations for 2026:
- Regulatory acceleration. If PPWR implementation tightens or additional EPR laws emerge, anticipate shifts in OEM capex and accelerated demand for compliant braking solutions.
- Input price reversal. A sudden rebound in polymer or metal prices would compress margins; lockable supplier contracts and dynamic pricing clauses should be considered.
- Channel disintermediation. OEMs internalizing service or aftermarket functions could disrupt traditional distributor models; build direct digital channels to end users.
- Competitive consolidation. M&A among top players would raise concentration and pricing pressure in some niches; prepare defensive acquisition or partnership options.
Recommended 90‑day playbook for executives
- Complete a quick‑scan of your product portfolio against PPWR/EPR reporting requirements; prioritize low‑effort product updates that unlock certified compliance.
- Negotiate short‑term supplier options to capture the 2026 plastics PPI decline; allocate at least part of the savings to product improvements or customer incentives that increase switching costs.
- Launch a pilot predictive‑maintenance offering for a key OEM customer to validate recurring revenue potential and collect operational data for future pricing models.
- Identify two acquisition or alliance targets: one that strengthens aftermarket capabilities and one that accelerates entry into a high‑value OEM segment (e.g., packaging machinery specialists).
Conclusion — the strategic value of the study for 2026
For 2026, industrial brakes is a market where clarity of execution trumps bet‑the‑business gambits. The macro picture — steady CAGR, regulatory reshaping of packaging demand, and transient input cost advantages — creates an environment ideal for value capture through focused investments in compliance support, aftermarket services, and modular product platforms. PW Consulting’s full report delivers the microdata, scenario models, and tactical playbooks required to convert these general observations into executable strategies. For teams preparing 2026 budgets, procurement cycles, or M&A roadmaps, the study is designed to be the single authoritative reference that aligns commercial, product, and finance decision‑making.
To access the granular regional, type and application splits, and to download the interactive forecasting model and board‑ready slide kit, please consult the full PW Consulting Industrial Brakes Market report.
For detailed analysis of this topic, please visit the official page: Industrial Brakes Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com