

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Industrial Brakes Market to reach USD 1,961.21M by 2032 at 4.4% CAGR

Industrial Brakes Market 2026: Strategic Preview for Executive Decision‑Making
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present a concise but substantive preview of our upcoming Industrial Brakes Market study — designed specifically to inform capital allocation, product strategy, and go‑to‑market decisions during 2026. This briefing highlights the macro trajectory, regulatory inflection points, competitive posture, and immediate strategic levers executives should prioritize. The full study contains the granular regional, type and application splits, detailed financial tables, and an interactive forecasting model; this article intentionally withholds those subsegment tables to preserve the report’s role as the single source of truth for tactical planning.
Industrial Brakes Market
Market trajectory: a steady, investible growth path
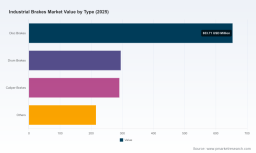
The Industrial Brakes market has demonstrated resilient expansion through the early 2020s and enters 2026 from a position of structural growth. Using 2025 as our base year, the market increased from USD 1,200.0 Million in 2020 to USD 1,454.4 Million in 2025. Our scenario-driven forecast for the 2026–2032 period projects a compound annual growth rate (CAGR) of 4.4%, with the market rising to approximately USD 1,961.2 Million by 2032 under the central case.
Industrial Brakes Market
What this trajectory means for 2026 planning: the sector is not in hyper‑growth mode, but it is predictable and sufficiently large that focused investments (product upgrades, aftermarket expansion, targeted M&A) can reliably move the needle. Organizations that treat 2026 as a year to optimize cost‑to‑serve, accelerate strategic partnerships in high‑value OEM segments, and capture aftermarket share will convert steady top‑line growth into outsized margin improvement.
Industrial Brakes Market
Why 2026 is a pivotal year
- Regulatory inflection. The Packaging and Packaging Waste Regulation (PPWR 2025/40) entered into force in February 2025 and will generally apply from August 12, 2026. The regulation — together with expanding EPR (extended producer responsibility) registers and compliance frameworks in multiple jurisdictions — alters packaging downstream behavior, influencing capital expenditure cycles for packaging machinery and the associated demand for industrial brakes.
- Shifts in input costs. Raw material pricing dynamics are reducing near‑term inflationary pressure: the Producer Price Index for plastic materials and resin registered a material decline into 2026. That creates a window in 2026 where BOM (bill of materials) cost reductions can be converted into improved margins, strategic price repositioning, or reinvestment in product features (e.g., lighter alloys, corrosion treatments, or sensor integration).
- Compliance timing in major markets. In the United States, state‑level EPR laws are moving toward compliance deadlines in spring 2026. Packaging OEMs and converters will reassess supplier contracts, total cost of ownership, and after‑sales service models — a strategic opening for brakes suppliers to negotiate embedded service agreements.
Competitive landscape and concentration
The market exhibits moderate concentration: the combined share of the top three firms sits near the mid‑50s percent range, while the top five capture just over 60 percent. These metrics point to an industry where leading vendors enjoy meaningful scale advantages and channel reach, but where focused challengers with differentiated technology or vertical specialization can still secure attractive niches.
Our competitive synthesis spotlights three players that exemplify distinct strategic postures:
- Regal Rexnord (Warner Electric™ & Stearns™ offerings) — Leveraging broad distribution and deep OEM relationships in packaging machinery, Regal Rexnord’s recent participation at PACK EXPO International 2026 reinforced its go‑to‑market strength in the packaging sector. Expect continued emphasis on integrated brake and clutch systems bundled with engineering support for OEM line integration.
- Coremo Ocmea — A European specialist with strong credentials in pneumatic caliper brakes and modular solutions for converting and packaging lines. Coremo’s modular approach enables rapid customization and short lead times — an important commercial differentiator where customers demand frequent configuration changes.
- Stearns — Known for spring‑set, power‑off electric motor brakes and clutches tailored to industrial packaging equipment, Stearns competes on reliability and aftermarket serviceability. Their product profile aligns well with OEMs that prioritize safety certifications and predictable downtime metrics.
These profiles illustrate the two dominant strategic axes in this market: scale and systems integration versus modular specialization and service intensity. Each axis yields different margin profiles and capital requirements; our full report maps those trade‑offs against buyer archetypes and procurement cycles.
Operational and commercial implications for 2026
- Prioritize compliance‑enabled offerings. With PPWR and EPR timelines converging in 2026, brakes suppliers should develop compliance‑aligned product messaging and service packages for packaging customers. This includes lifecycle reporting, take‑back/repair options, and documentation that supports producer registers.
- Capture aftermarket economics. Aftermarket service remains a durable margin pool. Companies should evaluate subscription models (predictive maintenance, condition monitoring) and bundling strategies that tie hardware sales to multi‑year service contracts.
- Exploit temporary input cost tailwinds. The decline in plastic/resin PPI in 2026 gives suppliers a narrow margin arbitrage. Use this to invest in product differentiation (sensorization, lightweight materials) or selectively fund customer incentives that lock in OEM partnerships.
- Rebalance supply chains. The combination of regulatory cost shifts and raw material volatility recommends a diversified supplier base and hedging strategies for critical components — particularly electronics and specialty alloys used in high‑end braking systems.
- M&A and partnerships. Given the industry’s moderate concentration, 2026 is an opportunistic year to evaluate bolt‑on acquisitions that deliver complementary technologies (modularity, electronic controls) or to secure regional market access through targeted deals.
What the PW Consulting report delivers (practical tools for immediate action)
PW Consulting’s Industrial Brakes Market study is built around decision‑grade outputs that executives can use in 2026 planning cycles. Highlights include:
- Multi‑scenario demand forecasts (central, upside, downside) from 2026–2032 with sensitivity levers for regulatory shifts and input price variance.
- Competitive benchmarking matrices that score vendors on product breadth, channel coverage, aftermarket capability, and integration readiness — enabling quick identification of acquisition targets or alliance partners.
- Regulatory impact models that translate PPWR and EPR obligations into OEM capex timing and incremental cost of compliance for packaging lines — actionable for contract negotiations and product roadmaps.
- Supply‑chain heat maps and a supplier risk index for critical inputs, with prescriptive sourcing strategies and contingency playbooks.
- Go‑to‑market playbooks for three buyer archetypes (OEM integrators, large converters/packagers, and aftermarket service buyers), each containing pricing tactics, commercial KPIs, and a 12‑month rollout plan.
- An interactive Excel model and slide kit that can be rebranded and used directly in board briefings or investment committees.
Risk register and early warning signals
Every strategic plan must be stress‑tested. Our study compiles a concise risk register with monitoring thresholds and recommended mitigations for 2026:
- Regulatory acceleration. If PPWR implementation tightens or additional EPR laws emerge, anticipate shifts in OEM capex and accelerated demand for compliant braking solutions.
- Input price reversal. A sudden rebound in polymer or metal prices would compress margins; lockable supplier contracts and dynamic pricing clauses should be considered.
- Channel disintermediation. OEMs internalizing service or aftermarket functions could disrupt traditional distributor models; build direct digital channels to end users.
- Competitive consolidation. M&A among top players would raise concentration and pricing pressure in some niches; prepare defensive acquisition or partnership options.
Recommended 90‑day playbook for executives
- Complete a quick‑scan of your product portfolio against PPWR/EPR reporting requirements; prioritize low‑effort product updates that unlock certified compliance.
- Negotiate short‑term supplier options to capture the 2026 plastics PPI decline; allocate at least part of the savings to product improvements or customer incentives that increase switching costs.
- Launch a pilot predictive‑maintenance offering for a key OEM customer to validate recurring revenue potential and collect operational data for future pricing models.
- Identify two acquisition or alliance targets: one that strengthens aftermarket capabilities and one that accelerates entry into a high‑value OEM segment (e.g., packaging machinery specialists).
Conclusion — the strategic value of the study for 2026
For 2026, industrial brakes is a market where clarity of execution trumps bet‑the‑business gambits. The macro picture — steady CAGR, regulatory reshaping of packaging demand, and transient input cost advantages — creates an environment ideal for value capture through focused investments in compliance support, aftermarket services, and modular product platforms. PW Consulting’s full report delivers the microdata, scenario models, and tactical playbooks required to convert these general observations into executable strategies. For teams preparing 2026 budgets, procurement cycles, or M&A roadmaps, the study is designed to be the single authoritative reference that aligns commercial, product, and finance decision‑making.
To access the granular regional, type and application splits, and to download the interactive forecasting model and board‑ready slide kit, please consult the full PW Consulting Industrial Brakes Market report.
For detailed analysis of this topic, please visit the official page: Industrial Brakes Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com