

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Polypropylene Pipes market to reach USD 217.22M by 2032 at 3.9% CAGR

Polypropylene Pipes Market: Strategic Outlook to 2026 — An Executive Preview
As PW Consulting’s senior industry analyst, I present a focused strategic primer on the polypropylene (PP) pipes market — an asset-light, engineering-centric sector that will demand measured capital allocation and sharper commercial playbooks by 2026. This preview synthesizes the market’s macro trajectory, competitive dynamics, regulatory and supply-side shocks, and the practical levers that executives must prioritize to convert modest growth into disproportionate competitive advantage. The full dataset, segmented analyses and proprietary models that underpin these conclusions are available in our published report.
Polypropylene Pipes Market
Why this market matters in 2026
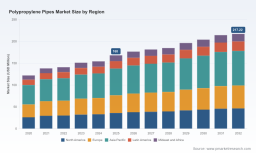
Polypropylene piping has evolved from a niche polymer alternative into a mainstream engineering choice for building services, potable networks and several industrial uses. The market’s macro posture is characterized by steady, investment-grade expansion rather than boom-and-bust volatility. After recovering from earlier cycles, global market revenue grew from roughly USD 122.0 million in 2020 to USD 168.0 million in our 2025 base year. Our forecast horizon (2026–2032) assumes a compound annual growth rate (CAGR) of about 3.9%, with the market reaching approximately USD 217.2 million by 2032.
Polypropylene Pipes Market
For corporate leaders and investors making decisions in 2026, this context matters because it signals a business environment where operational efficiency, product differentiation and channel execution — not merely volume scale — will drive returns. That translates into different capital priorities: targeted automation, selective geographic expansion, higher-margin system solutions (product + service), and disciplined M&A rather than broad-based capacity chasing.
Polypropylene Pipes Market
What the market dynamics are telling us
-
Steady demand backdrop. The historical series shows consistent expansion rather than episodic spikes. That steadiness favors companies that can optimize cost curves and build repeatable project pipelines (residential refits, commercial retrofits, and specified industrial projects).
-
Raw material tailwinds — short term. PP resin prices are expected to remain weak or broadly stable in the near term due to ample supply and balanced demand. Firms should use this window to secure multi-year procurement contracts or hedging structures to lock in margins ahead of potential feedstock tightening.
-
Regulatory and standards pressure. Compliance with pressure-piping standards (e.g., DIN 8077 / DIN 8078 in a number of markets) remains a gating factor for specification in institutional projects and large contractors. Certification timelines can materially affect go-to-market cadence for new products.
-
Installation productivity is a differentiator. Fusion welding technology reduces installation times versus traditional joining systems — a winner-take-most feature for projects where labor cost or speed matters (high-rise, MEP retrofit, rapid-deploy modular buildings). Suppliers who couple product training and certification for installers can convert better than purely price-based competitors.
-
Acceptance in potable and heating systems. Broad approvals for potable water and heating systems under many plumbing codes create a base-level market access; however, project-level specifications still hinge on legacy relationships and documented long-term performance.
Report coverage — pragmatic contents designed for 2026 decisions
Our full study is intentionally operational. Rather than a descriptive catalogue, it supplies a playbook for action across five decision horizons:
-
Near-term (0–12 months): Procurement playbook for PP resin, SKU rationalization for immediate margin lift, and quick-win process improvements on warehousing and logistics.
-
Medium-term (12–36 months): Product portfolio moves (e.g., fiber-reinforced variants, system-level solutions), targeted certification roadmaps to access regulated projects, and installer training programs to accelerate adoption.
-
Growth-led (36–60 months): Channel expansion frameworks, selective greenfield and brownfield investments, and integration scenarios for bolt-on M&A.
-
Risk and resilience: Scenario-based stress tests for feedstock shocks, regulatory shifts, and contractor labor volatility; contingency supplier maps and inventory buffer sizing.
-
M&A and partnership playbook: Target screening criteria, valuation heuristics tuned to the segment’s thin consolidation (low top-three share), and integration checklists to capture synergies from combined sales networks and spec-engineering capabilities.
The report blends quantitative models (price sensitivities, demand elasticities, and cash-flow scenarios) with actionable templates: sample supplier contracts, a certificate-timeline checklist for major standards, installer training curriculum outlines, and a 100-day integration plan for acquisitions.
Competitive landscape — who matters and why
The polypropylene pipes market remains fragmented: the top-three firms account for roughly 22.5% of market volume, while the top-five account for about 25.8%. That fragmentation creates openings for regional champions and product-specialist players to scale profitably through focused execution.
-
Aquatherm (Attendorn, Germany) — Known for PP-RCT and PP-R systems aimed at pressurized heating, cooling and plumbing. Strengths: established installer certification programs and product range tailored to mechanical contractors; risk: premium positioning in markets sensitive to price.
-
Georg Fischer Piping Systems (Schaffhausen, Switzerland) — Offers a broad PP-R and PP-RCT portfolio for potable and industrial networks. Strengths: global project experience and engineering support capabilities; opportunity: leverage industrial project pipeline to push system solutions.
-
Bänninger Kunststoff-Produkte GmbH (Germany) — Produces PP-R and PP-RCT fittings and pipes targeting drinking water and industrial uses. Strengths: precision manufacturing and strong OEM relationships; caution: scale limitations against global players.
-
Pipelife (Vienna, Austria) — Focused on hygienic hot/cold drinking water distribution systems. Strengths: product hygiene certifications and distribution reach in select European markets; path forward: expand into integrated building service contracts.
-
REHAU (Germany) — Broad building-services focus including fiber-reinforced PP-RCT options. Strengths: material innovation and building integration solutions; strategic imperative: monetize product innovation through specification partnerships with large contractors and system integrators.
Across this competitive set, winners to 2026 will be those that can convert product approvals and installation advantages into repeatable, contract-level share. That requires tighter collaboration with contractor groups, digital training platforms for fusion welding, and commercial models that shift some value capture from commodity pipe to engineered sub-systems.
Strategic implications and recommended moves for 2026
-
Lock in feedstock advantage. With resin prices subdued in the near term, secure multi-year supply or financial hedges to protect gross margins. Use scenario analysis in our report to quantify margin movement under ±15% resin swings.
-
Prioritize certification and time-to-specification. Institutional tenders and large contractors prize standards compliance and documented timelines. Fast-track DIN-equivalent certifications and map the approval lead times in priority markets.
-
Monetize installation productivity. Invest in installer training and certified fusion welding programs; sell system warranties and performance guarantees that capitalize on faster and more reliable joints.
-
Product + service bundles. Move up the value chain by offering design-assist, prefabricated assemblies and commissioning support—particularly in retrofit and modular projects where speed and coordination deliver premium pricing.
-
Targeted M&A and partnerships. Given the market’s low top-three concentration, bolt-on acquisitions that add engineering services, regional distribution or certification-ready product lines can compound returns faster than large-scale greenfield capacity plays.
-
Operationalize sustainability messaging. While life-cycle performance is not a standalone growth engine yet, suppliers that credibly reduce embodied carbon and improve recyclability will have an advantage when buyers include environmental metrics in tender scoring.
How PW Consulting’s study supports tactical 2026 choices
The full PW Consulting study provides the tactical scaffolding needed to execute the moves above: audited market-sizing (history and forecast), a procurement stress-testing tool, a regulatory compliance timeline by market, installer uptake models (fusion welding adoption curves), and a prioritized target list for M&A with modeled synergy capture rates. Importantly, while this preview outlines the strategic narrative, the granular segment tables, indexed regional demand drivers and confidential company-level revenue splits are intentionally withheld here — they are contained in the full report to preserve competitive value and ensure you have the evidence you need for board-level decisions.
Concluding perspective
By 2026, the polypropylene pipes industry will reward disciplined operators who translate steady market growth into higher-margin system sales, tighter procurement, and installer-centric commercial models. The market’s moderate CAGR and fragmented competitive structure mean that structural advantages — certification speed, fusion-welding adoption, and channel depth — will create sustainable differentiation. Executives preparing capex budgets, M&A pipelines or commercial strategies should orient around those levers now.
For an executive-ready set of tools — scenario models, segment-level forecasts, supplier scorecards, and a 100-day M&A integration playbook — consult the full PW Consulting polypropylene pipes market report. The detailed tables and proprietary subsegment analytics provide the concrete inputs needed to translate the strategic imperatives outlined here into decisive 2026 actions.
For detailed analysis of this topic, please visit the official page: Polypropylene Pipes Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com