

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Loading Dock Equipment Market Poised for 5.73% CAGR Through 2032

Loading Dock Equipment Market: Strategic Preview for 2026 Decision-Makers
As PW Consulting’s Senior Strategy Advisor and Lead Industry Analyst, I present a forward-looking synthesis of our Loading Dock Equipment Market study — a practical briefing designed to inform executive decisions in 2026. This preview distills the high-level trajectory, competitive dynamics, regulatory inflection points, and the actionable playbook senior leaders should use to prioritize investments, partnerships, and operational changes over the coming planning cycle. It deliberately demonstrates analytical depth while reserving the granular segment-level tables and proprietary supplier scores for the full report.
Loading Dock Equipment Market
Why this market matters in 2026
The loading dock equipment market is transitioning from a commoditized hardware space into a solutions-driven ecosystem where safety compliance, uptime guarantees, lifecycle services, and digital integration determine value capture. From 2020 through our base year of 2025 we observed steady demand growth; aggregate market revenues increased from the low hundreds of millions (USD, Million) to an estimated USD 215.0 Million in 2025. Our forecast period (2026–2032) projects sustained expansion at a compound annual growth rate (CAGR) of 5.73%, with the market moving toward an anticipated USD 344.8 Million by 2032.
Loading Dock Equipment Market
These macro dynamics create meaningful opportunities for manufacturers, systems integrators, facility operators, and capital allocators. The growth is large enough to justify strategic initiatives — from R&D in automated dock components to M&A aimed at building comprehensive service platforms — yet concentrated enough that incumbent players can preserve margins through differentiation and aftermarket services. Our market concentration analysis shows a moderately consolidated landscape: the top three vendors control roughly one-third of the market, while the top five account for just under half. This structure encourages both competitive positioning and targeted consolidation strategies.
Loading Dock Equipment Market
Key market drivers and headwinds
- Safety and regulatory pressure: Tightening safety oversight is a direct demand driver for upgraded dock solutions. For example, OSHA’s continued enforcement stance on open-sided dock guarding (OSHA 29 CFR 1910.23) remains a material consideration for capital planning and compliance-driven retrofits in 2026 and beyond.
- Operational resilience and labor economics: The push to maximize throughput with smaller labor pools is accelerating interest in mechanized and semi-automated dock technologies, intelligent controls, and service contracts that guarantee availability.
- Lifecycle monetization: Manufacturers are increasingly monetizing post-sale touchpoints — maintenance, predictive analytics, and extended warranties — which shift revenue mix from project-driven to annuity-like streams.
- Supply chain and raw material pressures: Component lead times and steel price volatility create both cost challenges and opportunities to re-engineer product families for modularity and local sourcing.
What the PW Consulting report delivers
This study is built for operational leaders and corporate strategists who need to move from awareness to action in 2026. The full deliverable contains:
- Detailed historical market sizing (2020–2025) and a seven-year forecast (2026–2032) in USD Million, anchored to our base year of 2025.
- Segment-level demand analysis across type, application, and region, with growth vectors and adoption curves for each segment (teaser: the report maps where retrofit demand outpaces new-build demand and why).
- Supplier benchmarking and capability matrices assessing product breadth, aftermarket capabilities, digital maturity, and go-to-market strength.
- Commercial playbooks for OEMs, distributors, and end-users: pricing strategies, service package design, channel optimization, and retrofit vs. replacement decision frameworks.
- Scenario planning and sensitivity analysis: stress-testing outcomes against macro shocks (steel price shocks, labor disruptions, and regulatory changes).
- Practical checklists and procurement templates to accelerate RFP cycles and shorten vendor evaluation time.
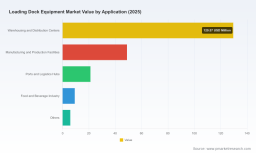
Note: This preview is intentionally non-exhaustive. Specific regional splits, application breakdowns, and supplier-level market shares are withheld here to protect the proprietary analyses included within the full report.
Competitive landscape — strategic takeaways
The competitive set includes long-established dock equipment OEMs, specialized lift and leveler manufacturers, integrated door and dock systems providers, and regional service specialists. Key industry participants exhibit a range of strategic postures:
- Full-solution integrators — firms with combined dock leveling, door systems, seals, and controls emphasize integrated uptime contracts and single-point accountability, which is attractive to large distribution centers seeking supplier consolidation.
- Product-specialist OEMs — manufacturers that focus on a narrow product line tend to lead in engineering depth and cost-competitive designs. Their edge lies in targeted innovation and scale on core SKUs.
- Aftermarket and service players — companies with dense field service networks convert installed bases into recurring revenue through maintenance, emergency repairs, and retrofit programs.
- Regional challengers — players with tight local distribution leverage speed-to-site and localized customization to win mid-market accounts against larger national brands.
Several named firms in the ecosystem demonstrate these archetypes. Some players are advancing programmable controls and remote monitoring; others compete on heavy-duty hydraulic and mechanical reliability. The result is a market where product differentiation, service economics, and channel reach determine long-term value capture more than raw manufacturing scale.
Strategic actions for 2026 — what executives should prioritize
For leadership teams deciding where to deploy capital and management attention in 2026, we recommend a three-track approach: Protect, Pivot, and Platform.
- Protect core value: Prioritize investments that defend existing revenue — e.g., bolster parts availability, accelerate field service digitization, and institute uptime SLAs for large accounts. Contractual guarantees combined with performance-based pricing are powerful retention levers.
- Pivot toward higher-margin services: Convert one-time transactional sales into recurring service revenues. Develop tiered maintenance packages, predictive service offerings using simple IoT telemetry, and retrofit bundles that address prevailing safety and compliance needs.
- Build platform capabilities: Where feasible, create interoperable control platforms and APIs that tie dock equipment into warehouse management systems and facility monitoring layers. Platforms increase switching costs and create data-driven upsell opportunities.
Operationally, procurement teams should accelerate lifecycle cost modeling (not just CAPEX) and insist on supplier transparency for mean time to repair (MTTR), parts availability, and embedded safety features. Investor and corporate development teams should screen targets that enhance service networks or add modular product technology, rather than acquiring undifferentiated manufacturing scale.
Risk and compliance lens
Regulatory enforcement is a persistent and non-obvious risk. OSHA requirements around guarding for open-sided dock areas are not just compliance checkboxes — they drive capital spending cycles and create windows for repurchase or retrofit. Facility operators must reconcile short-term budget constraints with the cost of non-compliance, downtime, and worker safety exposure. The report models the timing and size of compliance-driven demand under multiple enforcement scenarios, enabling procurement committees to plan capital appropriations accordingly.
How to use the full report for 2026 planning
Executives should treat the full report as an operational playbook rather than a passive market summary. Practical ways to use the analysis include:
- Benchmarking RFPs against supplier scorecards and validated lead-time baselines.
- Designing aftermarket service tiers with modeled margin impacts and churn assumptions.
- Prioritizing retrofit projects by ROI and regulatory exposure, using provided decision matrices.
- Screening acquisition targets with the included financial proxies and integration risk checklists.
The full deliverable includes downloadable tools and templates to speed decision cycles, from procurement checklists to a scenario-based capex prioritization spreadsheet.
Conclusion — the strategic horizon to 2032
By 2032 the loading dock equipment market is forecast to be materially larger than in 2025, underpinned by steady compound growth. That trajectory rewards firms that act now to capture durable service revenues, embed digital capabilities, and commercialize compliance-driven upgrades. The market’s moderate concentration means both incumbents and well-capitalized challengers can find profitable niches; success will hinge on execution — field service excellence, predictable supply chains, and product-roadmap alignment with safety and automation trends.
This preview is intended to accelerate your 2026 planning. For the complete segment-level analytics, supplier-specific benchmarking, pricing matrices, and the downloadable playbooks and templates referenced throughout, please consult the full PW Consulting Loading Dock Equipment Market report available via our website.
For detailed analysis of this topic, please visit the official page: Loading Dock Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com