

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting: Tonic Water Market to Reach USD 367.72 Million by 2032, Growing at 8% CAGR
By pmarketresearch, 2026-07-13
Tonic Water Market 2026: Strategic Imperatives from PW Consulting’s Industry Brief
As the tonic water category moves from a traditional mixer into a dynamic, flavor-driven beverage segment, boards and executive teams must translate rising consumer interest into defensible revenue streams. PW Consulting’s latest market research—anchored on a 2025 base year and spanning historical performance from 2020–2025 with forecasts through 2032—provides the decision-grade intelligence that leaders will use to set 2026 priorities. This preview summarizes the high-level market trajectory, competitive dynamics, and the kinds of operational playbooks included in the full study, while preserving the detailed sub-segment data for subscribers and clients.
Tonic Water Market
Why 2026 Is a Pivotal Year
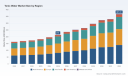
Between 2020 and 2025 the global tonic water market demonstrated steady expansion, reflecting both on-trade recovery and the acceleration of premiumization and home mixology. In 2025 the category reached a clear inflection point (base year), creating a launchpad for growth under multiple scenarios. Our forecast models—built on the 2025 baseline—project an aggregate compound annual growth rate (CAGR) of 8.0% during the 2026–2032 period, driven by premium and differentiated offerings, health-oriented formulations, and channel diversification. Under the central case, market value increases materially over the forecast horizon, signaling room for incumbent consolidation, challenger disruption, and strategic portfolio reshaping.
Tonic Water Market
Macroeconomic and Category Trajectory (Headline Figures)
- Base year: 2025 (report anchor).
- Forecast window: 2026–2032, with modeled outcomes across conservative, base, and aggressive scenarios.
- CAGR (2026–2032): 8.0% (USD, revenue unit: Million).
- Market expansion is meaningful—our models show sustained acceleration beyond the short-term post-pandemic rebound, supporting investment in capability and new SKUs.
Key Demand Drivers and Structural Shifts
- Premiumization and mixology culture: Consumers and trade operators are trading up to bespoke tonics and botanical variants that enhance cocktail narratives. Premium brands have translated provenance and ingredient stories into price premiums and boutique on-trade placement.
- Health and low-calorie alternatives: Reduced-sugar and naturally sweetened formulations continue to win distribution, particularly where brands can credibly combine taste and clean-label claims.
- Home consumption: Elevated home mixology—accelerated during recent years—remains sticky. Consumers purchasing nature-forward mixers expect variety and bar-quality performance at home.
- Channel evolution: E-commerce and direct-to-consumer models complement grocery and on-trade channels; omnichannel go-to-market strategies are required to capture full value.
- Supply chain and ingredient sourcing: Access to quinine, botanicals, and specialty flavorings creates both opportunity and vulnerability—sourcing strategies materially impact cost and margin profiles.
Competitive Landscape: Concentration and Strategic Positions
The category exhibits moderate concentration—our concentration metrics indicate that the top three players account for a majority share and the top five increase that share materially. This structure creates a dual environment: established global players retain shelf and on-trade advantages, while agile premium challengers exploit white space in flavor innovation and channel-first tactics.
Tonic Water Market
Representative company positions analyzed in the report include:
- Schweppes (London, UK): Heritage advantage with a multi-variant portfolio. Strengths: broad commercial reach, classic and low-sugar offerings, scale manufacturing. Strategic question: how to refresh legacy branding to capture premium wrists and younger demographics without eroding core equity.
- Fever-Tree (UK): Premium specialist known for provenance-led storytelling and selective distribution agreements. Strengths: brand equity in premium bars and retail; consistent innovation. Considerations: margin management as premium competition increases.
- Double Dutch (UK): Niche premium and botanical focus; recent portfolio moves indicate acceleration (including a Mediterranean-inspired launch in late 2025 and a strategic rebranding in early 2026). These actions show deliberate effort to broaden appeal while protecting craft credentials.
- Boylan Bottling Co. (US): Domestic producer emphasizing locally sourced ingredients and nostalgic positioning. Strengths: US supply chain control and retail placement; opportunity to scale via selective national partnerships.
- Britvic (UK): Large mixer portfolio with multiple tonic SKUs. Strengths: route-to-market and private label capability. Strategic trade-off: balancing scale with the need to protect premium brand margins.
- Smaller entrants (e.g., Dappled, Match Tonic, Owen’s Mixers, Arctic Blue): These brands are important sources of innovation—specialist flavor work, low-calorie formulations, and regional distribution plays. Their agility pressures incumbents on product life-cycle speed and authenticity.
Recent Strategic Moves That Matter
- Double Dutch (2025–2026): A Mediterranean-inspired tonic launch in late 2025 followed by a brand repositioning in early 2026 illustrates a playbook we expect to be replicated: introduce provenance-led SKUs, then broaden naming and marketing to maximize cross-market appeal. This two-step approach reduces initial risk while enabling scale.
- Channel partnerships and distribution pacts: Observed distribution alliances—particularly between premium specialists and regional distributors—are enabling rapid penetration into on-trade accounts and specialty retail, while protecting brand positioning.
What the Full Report Contains (Practical, Actionable Elements)
PW Consulting’s full study is designed as a decision-support toolkit for commercial, innovation, and M&A teams. Highlights include:
- Proprietary demand models (historical 2020–2025 and forecasts 2026–2032) with scenario toggles to test price, penetration, and channel assumptions.
- Interactive revenue and margin simulators (USD, Million) calibrated to distinct SKU archetypes and operating cost baselines.
- Go-to-market playbooks tailored to brands at different scale stages—covering assortment strategy, retailer negotiation frameworks, on-trade activation plans, and e-commerce conversion tactics.
- Innovation and product roadmaps: flavor prioritization matrices, cost-to-launch templates, and sensory validation protocols for botanical and low-sugar variants.
- Supplier and sourcing risk register with mitigation strategies for key raw materials, including contract structure options and regional sourcing trade-offs.
- M&A and partnership screening: criteria-based shortlists, valuation heuristics, and integration playbooks for acquiring scale or capability (e.g., flavor labs, regional bottlers).
- Regulatory and labeling guidance relevant to claims (e.g., “natural,” “zero sugar”) across major jurisdictions.
Strategic Recommendations for 2026 Decision-Makers
- Prioritize a two-tier portfolio: Maintain core mainstream SKUs to protect mass distribution while developing a distinct premium line with clear provenance and botanical storytelling. Use phased rollouts to test pricing elasticity before national scale-up.
- Invest in formulation for taste parity: Low- and no-sugar tonics must deliver on taste. Allocate R&D to mouthfeel enhancers and natural flavor extraction; consider contract R&D partnerships to accelerate time-to-market.
- Channel-specific assortment: Tailor SKUs for on-trade, grocery, and direct-to-consumer channels rather than a single blanket approach. Trade buyers and bartenders prioritize different attributes than home consumers; align packaging and price points accordingly.
- Secure upstream supply: Lock-in favorable long-term agreements for key botanicals and quinine to protect margin volatility. Consider dual-sourcing strategies for critical ingredients.
- Lean into experiential marketing: Use bartender partnerships, tasting tours, and cross-brand cocktail programs to drive premium perception and justify higher ASPs (average selling prices).
- Evaluate M&A for capability gaps: For companies seeking rapid capability expansion—whether in flavor craft, regional bottling capacity, or e-commerce infrastructure—targeted acquisitions can compress the path to scale. Use our M&A playbook for diligence and integration sequencing.
Implications by Stakeholder
- Brands: Invest in SKU differentiation, storytelling, and taste-first R&D. Defend core distribution while piloting premium variants in strategic markets.
- Retailers: Curate a balanced tonic set that captures both mainstream demand and higher-margin craft options; design in-aisle education for new flavor variants.
- Suppliers: Prepare for rising demand volatility and offer collaborative supply agreements; premium brands will pay for certified sourcing and traceability.
- Investors: Look for companies with clear routes to margin expansion via premiumization and channel diversification; prioritize those with controllable supply chains and defensible brand equity.
How to Use This Intelligence in 90 Days
- Run our scenario tool to stress-test pricing and volume assumptions for your top three SKUs.
- Pilot one premium botanical tonic in a controlled on-trade cluster while tracking sales velocity and margin contribution.
- Initiate supplier conversations to create hedging options for primary botanicals and quinine equivalents.
- Assess M&A targets against the report’s acquisition criteria and shortlist two for preliminary diligence.
PW Consulting’s full Tonic Water Market report contains the segmented tables, regional and application breakdowns, and company-level scorecards necessary to operationalize the recommendations above. This preview is intentionally selective—designed to demonstrate the report’s strategic depth while guiding you to the detailed models and segment-level insights available in the full deliverable.
Next Steps
Executives seeking to convert 2026 market momentum into sustainable advantage should review the full study and accompanying model suite. The complete package includes download-ready financial models, SKU-level P&L templates, and a prioritized implementation roadmap tailored to the tonic water value chain. Contact PW Consulting or visit the report landing page to access the full intelligence set and to arrange a strategy workshop that adapts the findings to your business context.
For detailed analysis of this topic, please visit the official page: Tonic Water Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Ferrite Magnets Market to Reach USD 8,413M by 2032 at 6.5% CAGR
By pmarketresearch, 2026-07-13
Ferrite Magnets Market — 2026 Strategic Outlook: Actionable Intelligence for Executive Decision-Making
Executive snapshot
The Ferrite Magnets market is at an inflection point. After expanding from a global market value of approximately USD 4.0 billion in 2020 to roughly USD 5.48 billion in the base year 2025, the sector is projected to continue to grow through the coming decade. Our forecast shows the market reaching an estimated USD 8.41 billion by 2032, driven by a mid-single-digit compounded annual growth rate (6.5% CAGR across the 2026–2032 forecast window). For corporate leaders, procurement heads and strategy teams preparing plans for 2026, this trajectory signals both expanding demand and intensifying competitive pressure — a combination that rewards clarity of positioning, supply-chain resilience and targeted investment in product differentiation.
Ferrite Magnets Market
Why 2026 matters: a strategic inflection
-
Base-year alignment and planning horizon. With 2025 serving as our analytical baseline and 2026 marking the start of the forecast window, companies must translate historical recovery patterns into forward-looking choices: where to allocate R&D, how to structure supplier networks, and which customer verticals to prioritize.
Ferrite Magnets Market -
Regulation and sustainability as cost and market drivers. Stricter environmental standards — particularly in Europe — are already reshaping production footprints and capital allocation. Regulations are pushing manufacturers to adopt lower-carbon processes and eco-friendlier inputs, altering total cost of ownership for product lines.
Ferrite Magnets Market -
Supply-chain rebalancing under tariff and raw-material volatility. Tariff shifts and raw-material price moves have made sourcing economics more dynamic; procurement strategies that were optimal in 2022–24 are frequently suboptimal entering 2026.
Market dynamics that will shape 2026 decisions
Three systemic forces will dominate corporate choices in 2026:
-
Input-price sensitivity. The ferrite value chain is tightly coupled to a narrow set of raw materials. Changes in the costs of key inputs such as strontium carbonate and iron oxides directly affect finished-goods pricing, margin volatility and competitive positioning. Procurement teams must therefore pair traditional cost-management tactics with financial hedging or long-term offtake arrangements to stabilize margins.
-
Regulatory and compliance pressure. Regional regulations are increasingly binding. European decarbonization goals — which are driving manufacturers to target substantial emissions reductions via process optimization — are an operational imperative rather than a reputational option. Separately, a significant share of manufacturers report ongoing difficulties achieving consistent compliance, creating an outsized opportunity for first movers who can certify low-carbon production at scale.
-
Geopolitics and tariffs. Elevated tariff regimes in major markets have already shifted sourcing calculus and increased incentive for near-shoring or onshoring higher-value manufacturing steps. Strategic decisions regarding plant location, contract manufacturing partners and inventory buffering will have outsized P&L implications in 2026.
Competitive landscape — what market structure implies for strategy
The market shows a moderate level of concentration: the three largest players capture a meaningful but non-dominant share of global shipments, while the five largest firms account for a sizable majority of market power. This structure creates a two-track competitive environment: a top-tier arena where scale, integrated supply chains and broad product portfolios matter; and a secondary terrain where specialization, speed-to-spec and customer intimacy can secure attractive margins.
Key participants and strategic positioning insights:
-
TDK Corporation — leveraging oxide-sintered powder metallurgy and microstructure control to compete on performance. TDK’s FB Series underscores an approach that blends manufacturing sophistication with diversified end-market reach (automotive, electronics and industrial). Their advantage: deep process know-how and a product roadmap aligned to sensor and high-performance motor use-cases.
-
Proterial, Ltd. — focused on high-performance ferrite technologies optimized for electrified powertrains. Their work on traction-motor-optimized magnet series positions them squarely within the xEV supplier ecosystem where torque-density and thermal stability are premium attributes.
-
Ferroxcube — prominent in soft ferrite cores and high-frequency magnetics for EMI suppression and power-electronics. Ferroxcube’s domain expertise signals an adjacency play: vertical migration from components toward systems-level magnetics in power-conversion applications.
-
Arnold Magnetic Technologies — a diversified player in bonded and sintered products and assemblies, known for flexible strip technologies and small-batch precision for motors and sensors. Arnold’s strength is custom engineering and integration services that shorten OEM development cycles.
-
Hengdian Group DMEGC — a scale leader and global producer of hard ferrite; their cost position and capacity footprint make them a natural partner for volume-driven OEMs and a competitive pressure point on commoditized components.
-
Electron Energy Corporation — specialty supplier focused on high-reliability aerospace, defense and mission-critical industrial applications. Their value proposition is performance-certification and traceability rather than cost leadership.
Strategic playbook for 2026
Executives preparing budgets and strategic roadmaps for 2026 should consider the following, prioritized by expected near-term ROI and risk mitigation effectiveness:
-
Hedge and diversify raw-material exposure. Implement layered hedging, longer-term supply contracts and dual-sourcing arrangements for critical inputs. Integrate raw-material scenarios into product pricing and warranty frameworks.
-
Invest selectively in low-carbon process upgrades. Prioritize process changes that deliver both emissions reductions and unit-cost advantages (energy efficiency, kiln modernization, waste reduction). Use sustainability credentials as a commercial differentiator in regulated markets.
-
Calibrate manufacturing footprints. Reassess the trade-offs between scale and proximity. For firms exposed to tariff regimes, localized assembly or final-processing capacity can preserve margin and shorten lead times.
-
Pursue adjacent-cluster specialization. Identify high-margin niches (e.g., traction motors, high-frequency power electronics, aerospace-grade assemblies) where product differentiation and certification barriers protect value.
-
Design for modularity and serviceability. Offer magnet modules and assemblies that reduce integration costs for OEMs and increase switching costs in multi-sourcing scenarios.
-
Use scenario-driven capital allocation. Tie CAPEX plans to scenario triggers: raw-material price bands, tariff changes, and certification timelines. This keeps balance sheets flexible while preserving optionality.
What PW Consulting’s full Ferrite Magnets Market report delivers
Our research is built to be directly operational for 2026 planning cycles. The full report includes:
-
A detailed market model (base year 2025) and a 2026–2032 forecast built on a rigorous, transparent methodology — including sensitivity scenarios for raw materials, tariffs and regulatory change.
-
Commercial playbooks for OEMs, magnet producers and component integrators that translate macro outlooks into product, pricing and go-to-market actions.
-
Supplier maps, cost-curve analyses and pricing models designed to support procurement negotiations and margin recovery plans.
-
Competitive heatmaps and an M&A shortlist, informed by market-concentration metrics and firm-level capabilities — enabling faster due diligence.
-
Technology and IP landscape coverage with implications for product roadmaps and partnership strategies across automotive, consumer electronics, industrial and aerospace segments.
-
Regulatory compliance playbooks and a sustainability roadmap aligned to the latest emissions-target requirements across major jurisdictions.
Note: this article intentionally summarizes the directional insights from our research. Detailed segment-level numbers, regional allocations and application-specific financials are available exclusively in the full report and accompanying datasets.
How to convert insight into advantage in 2026
-
Translate market modeling into actionable KPIs. Use supply-risk scores, material cost-per-unit sensitivity and time-to-certification metrics to prioritize projects.
-
Integrate procurement and R&D planning. Co-locate procurement, process engineering and customer-development resources to accelerate product qualification cycles for high-growth end-markets.
-
Use M&A as a capability acceleration lever. Given a market structure where larger players control meaningful share but pockets of specialist capability remain fragmented, bolt-on acquisitions can rapidly close capability gaps in magnet chemistry, assembly or certification domains.
-
Measure and manage regulatory-forward exposure. Build an early-warning dashboard tying regulatory developments and carbon-cost estimates to production-location decisions and client-contract clauses.
Conclusion — what to act on now
For executives whose 2026 plans will determine market positioning through the end of the decade, the window for decisive action is narrow. The broad market is growing at a steady mid-single-digit rate (6.5% CAGR across 2026–2032), creating both volume opportunities and margin pressure. The firms that will outperform are those who convert macro visibility into operational commitments: hedged supply chains; sustainable process investments that cut long-term cost; and focused product strategies aimed at high-value applications. For teams building 2026 budgets and three-year roadmaps, the imperative is to align commercial, sourcing and technical investments around scenarios that capture upside while controlling downside from raw-material volatility, regulation and evolving trade dynamics.
To access the full dataset, the detailed segment and regional analysis, and a customizable set of decision-support tools designed for 2026 strategy cycles, visit our report page or contact PW Consulting’s Ferrite Magnets practice for a briefing tailored to your business questions.
For detailed analysis of this topic, please visit the official page: Ferrite Magnets Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Lithium-Ion Separator Market to Reach USD 15,174M by 2032 at 13.5% CAGR
By pmarketresearch, 2026-07-13
Lithium‑Ion Battery Separator Market — Strategic Outlook for 2026 Decision‑Making
PW Consulting’s latest market study positions the lithium‑ion battery separator market at the center of the next wave of electrification. The industry has already more than doubled in size over the past half‑decade, expanding from roughly USD 3.30 billion (Million USD units) in 2020 to about USD 6.25 billion in 2025. Our forecast shows continued rapid growth: the market is projected to cross the USD 7.0 billion threshold in 2026 and to approach USD 15.2 billion by 2032, reflecting a 13.5% compound annual growth rate across the 2026–2032 forecast window. For executives planning 2026 budgets and strategic moves, these topline dynamics create both urgency and a clear runway for targeted investments.
Lithium-Ion Battery Separator Market
Why this study matters for 2026 decisions
- Timing of capacity and capability investments: With market volumes accelerating, firms that commit to the right mix of membrane technologies, coating capabilities, and localized capacity in 2026 will capture disproportionate share as demand scales.
- Cost and raw‑material exposure: Feedstock volatility in early 2025 has already demonstrated how quickly margins can be compressed; our report quantifies those sensitivities and models procurement levers that protect margin under multiple price trajectories.
- Regulatory compliance as a competitive moat: New region‑level rules on carbon accounting and recycled content are reshaping where and how separators are manufactured. The study translates regulatory obligations into actionable manufacturing and sourcing choices for 2026 planning cycles.
- Supplier and technology risk management: Consolidation trends and strategic pivots by legacy suppliers are reshaping the competitive map. The research equips Sourcing, Product, and Corporate Development teams to make quicker, lower‑risk decisions.
Macro dynamics shaping near‑term strategy
Several structural forces will govern outcomes in 2026 and beyond. First, the market momentum is clear: the separator market more than doubled in five years and is forecast to sustain high double‑digit growth through 2032. Leaders should assume a growth baseline consistent with a mid‑teens CAGR while stress‑testing plans against both higher and lower demand scenarios.
Lithium-Ion Battery Separator Market
Second, raw‑material shocks have become a defining near‑term risk. Unplanned outages at crackers in 2025 raised feedstock costs materially for polyolefin resins — a key input for many separator films. Our modeling shows that these upstream cost movements, absent offsetting operational changes, can erode margin rapidly for membrane manufacturers and their downstream OEM customers.
Lithium-Ion Battery Separator Market
Third, public policy is shifting from supportive to prescriptive. The U.S. Department of Energy’s technology cost targets for long‑duration storage — and accompanying cost metrics that place explicit pressure on separator unit costs — mean that manufacturers and OEMs must prioritize cost engineering and process upgrades. Concurrently, European battery rules that mandate carbon‑footprint reporting and recycled content are accelerating localization and upstream decarbonization investments, particularly for coating and finishing operations.
Finally, product‑level safety regulation is converging on separator performance — thermal stability and shut‑down behavior are becoming regulatory attributes referenced in national EV safety programs. Expect evolving test protocols and procurement checklists that elevate safety‑validated separators in supplier selection.
Competitive landscape — what to watch in 2026
The market is neither hyper‑fragmented nor concentrated to monopoly — the three largest players account for a meaningful share, and the top five together command a clear majority of market value. This structure produces a competitive dynamic where scale, differentiated technology (coatings, ceramic integration, ultra‑thin films), and global footprint matter in equal measure.
Key industry participants to monitor:
- Asahi Kasei Corporation (Tokyo) — Notable for advanced coated wet‑process films and recent product launches focused on safety and efficiency. Their R&D pathway emphasizes multi‑layer coatings that balance ionic transport with mechanical and thermal robustness.
- Toray Industries (Tokyo) — A long‑standing polymer film and coating provider that in 2025 initiated a strategic reassessment of certain assets in response to intensified price competition and regional shifts. Watch for further portfolio rebalancing or targeted collaborations.
- SK IE Technology (Seoul) — A competitive force in high‑performance separators for EVs and grid storage; technology leadership and scale make them a key supplier for OEMs pursuing high energy‑density chemistries.
- Entek International (Terre Haute) — A U.S. manufacturer expanding domestic wet‑process capacity — an example of supply chain re‑onshoring aligned with policy and customer preferences for local content.
- Ube Corporation and Sumitomo Chemical (Japan) — Established polyolefin film producers focused on high‑performance base films that form the substrate for many modern separators.
- Celgard (Charlotte) — Recognized for high‑performance microporous membranes and a strategic supplier to global battery producers.
- Freudenberg Group (Germany) and SEMCORP (Shanghai) — Both are aggressively investing in ultra‑thin and high‑strength separator technologies; SEMCORP’s rapid scale‑up continues to be a competitive dynamic OEMs must price into forecasts.
- Microporous LLC (Tennessee) — Recent U.S. production line commissioning signals accelerating capacity additions in North America, relevant to firms planning local procurement and qualification paths.
Recent corporate moves underscore shifting strategies: Microporous’s new line in 2025 accelerates U.S. capacity; Asahi Kasei’s product launch in late 2025 targets safety‑differentiated demand; Toray’s stake sale in Hungary signals portfolio optimization under price pressure; and an Arkema–SEMCORP memorandum points to cross‑industry technology alliances. Each event alters short‑term supplier availability, qualification timetables, and bargaining dynamics.
What the PW Consulting report delivers — practical assets for 2026
The study is intentionally built as a decision‑making toolkit rather than an academic exercise. Deliverables include:
- Granular market models from 2020 through 2032 with topline and scenario forecasts (including downside and accelerated adoption cases).
- Supplier benchmarking and a vetted shortlist for strategic sourcing, including production footprint, technology profiles, and qualification timelines.
- Raw‑material cost sensitivity modules that map feedstock price moves to separator landed costs, with hedging and procurement playbooks.
- Regulatory tracker translating regional battery rules and U.S. DOE cost targets into concrete manufacturing and product spec changes.
- Commercial playbooks for OEMs and converters: pricing frameworks, qualification checklists, and negotiation levers tied to capacity commitments.
- M&A and partnership opportunities prioritized by strategic fit, integration complexity, and near‑term value capture potential.
To preserve commercial value and drive actionable engagement, we present summary insights publicly while maintaining detailed regional and application splits, supplier share tables, and project‑level capacity schedules behind our subscriber gateway.
How to convert insight into 2026 action — recommended playbook
For executives charting plans this year, the following prioritized actions will materially reduce downside risk and maximize upside capture:
- Operational readiness: Fast‑track qualification of at least two alternative suppliers per critical product family; prioritize suppliers with nearby coating capabilities to comply with EU recycled‑content and carbon rules.
- Cost engineering to DOE targets: Reconfigure procurement and design specifications to align with the DOE’s unit‑cost expectations for long‑duration storage; evaluate process investments (e.g., extrusion upgrades) that lower per‑square‑meter costs.
- Sourcing resilience: Hedge or vertically integrate exposure to high‑melt‑flow polypropylene where economically sensible; use multi‑year contracts with flex volumes tied to verified quality metrics.
- Localize strategic operations: For customers operating in regulated markets, prioritize local coating or finishing to shorten qualification cycles, reduce logistics risk, and comply with carbon/recycled content mandates.
- Product and safety differentiation: Shift R&D mix toward separators that demonstrably improve thermal stability and safety‑related test performance; regulatory referenced attributes will become commercial differentiators.
- M&A and partnerships: Pursue tuck‑in deals for coating know‑how and near‑market capacity; consider strategic alliances with resin suppliers to secure feedstock continuity.
Scenarios you must model in 2026 planning
The report provides three practicable scenarios executives should stress‑test in 2026 planning cycles:
- Base case: Growth following the market’s mid‑teens CAGR projection, with moderate feedstock volatility and gradual regulatory compliance costs.
- Cost‑shock case: Prolonged feedstock price inflation and supply tightness leading to margin compression unless mitigated by process upgrades and local sourcing.
- Regulatory‑accelerated localization: Tighter regional content and carbon rules forcing faster build‑out of local coating/finishing capacity, advantaging firms with early localization plays.
Closing — why engage now
2026 is a pivotal year: the market has achieved scale, policy pressure is rising, and supplier footprints are being reconfigured. Our study quantifies these inflection points and converts them into executable choices — from precise capex timing and supplier hedging to product development priorities and M&A targets. We intentionally summarize high‑level trends here to enable rapid executive ingestion; the full intelligence package contains the gated segmentation, supplier shares, and project‑by‑project capacity maps that translate strategic intent into operational plans.
For boards, C‑suite leaders, and investment committees preparing 2026 approvals, the granular datasets and playbooks in our report are crafted to cut months off planning cycles and to reduce execution risk. Contact PW Consulting to access the complete report and the supporting models that convert the market’s strong growth trajectory into defensible, high‑value decisions.
For detailed analysis of this topic, please visit the official page: Lithium-Ion Battery Separator Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Winches Market to Grow at 4.2% CAGR, Reach USD 2.34B by 2032
By pmarketresearch, 2026-07-13
Winches Market 2026: Strategic Preview for Executives — What PW Consulting’s New Study Reveals (and What It Intentionally Keeps Back)
Executive snapshot
As companies plan capital allocation and product strategy for 2026, the winches market presents a mix of steady growth, concentrated pockets of supplier power, and accelerating regulatory and materials pressures that will reshape supplier economics and customer expectations. PW Consulting’s forthcoming Winches Market study synthesizes five years of historical data (2020–2025) with a seven‑year forecast (2026–2032), delivering a forward-looking playbook that combines quantitative market sizing and scenario analysis with operationally actionable guidance for procurement, R&D, and M&A teams.
Winches Market
Market trajectory in macro terms
Understanding the broad market trajectory is the essential first step for strategic decision‑making. The global winches market expanded from approximately USD 1.43 billion in 2020 to roughly USD 1.76 billion by the base year 2025. Our model projects a compound annual growth rate (CAGR) of about 4.2% across the 2026–2032 forecast window, taking the market toward the upper end of a USD ~2.34 billion range by 2032 under the central case. This is a market of steady expansion rather than explosive disruption: demand is driven by a mix of replacement cycles, infrastructure projects, maritime activity, and the gradual technology refresh of fleets and industrial equipment.
Winches Market
Why these headline numbers matter for 2026 decisions
-
Capital allocation: A 4.2% CAGR implies predictable, low‑volatility topline growth — an environment where targeted, efficiency‑focused investments (production modernization, digital service layers, and certification readiness) often outpace broad greenfield expansion.
Winches Market -
Portfolio prioritization: Manufacturers and OEMs should prioritize higher‑margin adjacent services (aftermarket monitoring, certified inspection, retrofit kits) and selective electrification initiatives where ROI timeframes align with procurement cycles.
-
M&A and partnerships: The market’s moderate consolidation metrics (notably the concentration among leading players) create windows for bolt‑on acquisitions and strategic alliances to capture aftermarket share and certification‑driven retrofit demand.
Dynamics reshaping the market (what we see through 2026)
-
Regulatory inflection: From January 2026, revised international maritime safety provisions require newly installed shipboard lifting appliances — including winches — to meet certified design, testing, and inspection standards. This is a near‑term compliance inflection that raises the bar for suppliers serving marine and offshore segments. Companies that achieve and demonstrate compliance quickly will capture premium aftermarket and retrofit opportunities.
-
Input cost volatility: Persistent steel price swings and alloy supply constraints are exerting margin pressure and complicating long‑range procurement. Our report quantifies scenarios for raw‑material pass‑through and offers hedging and supplier diversification tactics for procurement leaders.
-
Technology and electrification: Electric systems continue to displace traditional solutions where duty cycles and energy availability align. However, hydraulic and pneumatic technologies retain relevance in high‑duty and specialty applications. The near term will be characterized by hybridization and modularization rather than wholesale substitution.
-
Service and digitalization: Predictive maintenance, digital certification logs, and remote inspection services are emerging as key differentiators, enabling suppliers to increase lifetime revenue and lock in customers through recurring contracts.
Competitive landscape — positioning and implications
The market is neither winner‑takes‑all nor highly fragmented; top suppliers exert meaningful influence while a broad intermediary base services regional and specialist niches. Our analysis delves into the strategic posture of core players and the playbooks they are likely to follow into 2026.
-
Ramsey Winch (Prescott, Arizona) : Known for durable planetary and worm‑gear architectures, Ramsey competes on reliability and aftermarket support. Their strength in towing and recovery segments positions them well to capitalize on retrofit demand driven by regulatory updates and fleet renewal cycles.
-
Thern (Winona, Minnesota) : Thern’s vertically integrated U.S. manufacturing and breadth across electric, hydraulic, air, and hand winches make them a go‑to for industrial customers requiring customization and quick lead times. Expect continued premium positioning around custom engineering services.
-
Warn Industries (Clackamas, Oregon) & Superwinch (Hartford, Connecticut) : Both are recognized for vehicle and powersports winches. Their consumer and light commercial roots make them agile adopters of electrification and aftermarket accessory strategies targeted at end‑users rather than industrial procurement teams.
-
Duff‑Norton & Patterson Manufacturing : These suppliers bridge hoists and winches for manufacturing and handling. Their strength lies in integration with factory systems and service contracts; they are logical partners for automation and digital‑maintenance plays.
-
Lewmar, Ronstan, Seldén : Marine‑focused vendors with strong brand equity in sailing and commercial vessels. IMO’s tightened standards amplify the premium for certified marine solutions and create an aftermarket service runway for these players.
-
KÖSTER, Crosby Group, Ingersoll Rand : European and global players active in diversified industrial segments where safety certification, rigging systems, and integrated lifting solutions command higher margins. Their global distribution networks and safety credentials make them attractive to large fleet owners and contractors.
Our concentration analysis shows a market where the top three and top five firms hold meaningful but not overwhelming shares — enough to influence standards and pricing, yet leaving opportunity for focused challengers and service specialists. The study evaluates competitive moves (product launches, certification campaigns, government contracts) and maps likely trajectories through 2026 based on capability gaps and regulatory timelines.
Recent signals that matter
-
Government procurement and defense contracts are resurfacing as material demand drivers, exemplified by recent multi‑million dollar awards for mooring and marine winches. These contracts accelerate certification needs and create long lead demand for specialty suppliers.
-
Repeated regulatory notices from maritime authorities reiterate that compliance timing will dictate where and when retrofit or replacement waves materialize. Suppliers slow to adapt risk being excluded from certified tenders.
-
Industry commentary on raw‑material pressures underscores the importance of contract structures that protect margins while remaining competitive in capital procurement cycles.
Operationally actionable insights provided in the report
PW Consulting’s Winches Market study is designed as a strategist’s toolkit. Highlights include:
-
Market sizing and demand scenarios (base, upside, downside) with clear implications for capacity planning and inventory strategy.
-
Regulatory compliance roadmap — a practical checklist that maps certification steps, timelines, and typical testing regimes for marine and offshore installations.
-
Procurement playbook — recommended contract clauses, supplier selection frameworks, and hedging tactics to manage steel and component price volatility.
-
Technology and product roadmap — evaluation of electrification thresholds, hybrid system economics, and retrofit conversion kits that maximize ROI within typical fleet replacement cycles.
-
Aftermarket and service monetization models — pricing benchmarks, service‑level structures, and digital‑service playbooks for converting one‑time sales into recurring revenue.
-
Competitive heatmaps and capability matrices — who competes where, which firms are certification leaders, and where white spaces exist for targeted go‑to‑market plays.
-
M&A and partnership thesis — prioritization framework for inorganic growth targets that accelerate access to certification, aftermarket channels, or critical components.
How executives should use this preview to shape 2026 strategy
-
Prioritize certification readiness in product roadmaps and supplier selection: regulatory timelines create near‑term windows to win premium contracts and aftermarket retrofits.
-
Allocate capital to modular electrification and digital service capabilities rather than blanket factory expansion: targeted investments can unlock higher lifetime value per asset.
-
Hedge raw‑material exposure and redesign to reduce high‑steel components where feasible — small design changes and alternative materials can protect margins without sacrificing safety.
-
Seek bolt‑on acquisitions in service and inspection to build recurring revenue streams and defensive aftermarket positions against larger competitors.
What we are intentionally withholding here (and why)
To preserve the study’s commercial value and adhere to our “trailer” principle, this article intentionally omits granular region‑by‑region and application‑level splits, product‑type volumes, and detailed pricing tables that underpin procurement decisions. These proprietary segment matrices and price curves are included in the full report and form the basis for the operational playbooks and bidding models we provide to clients. If your team needs the segment tables, buyer personas, and the supplier decision matrices to execute a 2026 plan, the full study contains them in downloadable and spreadsheet formats.
Quick practical next steps
-
Procurement and product teams: Request the regulatory compliance appendix and the pricing sensitivity sheets to stress‑test your 2026 budgets.
-
Strategy and corporate development: Use our M&A prioritization framework and competitive heatmaps to short‑list targets for due diligence.
-
Operations and service leads: Adopt the predictive‑maintenance and aftermarket monetization templates to create recurring revenue pilots before Q4 2026.
Concluding note
The winches market in 2026 will reward companies that combine disciplined operations with certification leadership and a services‑first mindset. PW Consulting’s Winches Market study provides the synthesis of historical trends, granular forecasting, and executable playbooks your team needs to make informed decisions. For access to the full data tables, segmented forecasts, and downloadable strategic toolkits, please visit our report page — the detailed intelligence you need to act in 2026 is there, behind the curtain we’ve kept intentionally closed in this preview.
For detailed analysis of this topic, please visit the official page: Winches Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Metal Bellows Market to Reach USD 326.1 Million by 2032 at 6.2% CAGR
By pmarketresearch, 2026-07-13
Metal Bellows Market — 2026 Strategic Preview: Trajectory, Risks, and Executive Playbook
As companies prepare budgets and product roadmaps for 2026, understanding where the metal bellows market is headed — and why — becomes a practical imperative. Our latest PW Consulting market research uses a 2025 base year and a 2026–2032 forecast window to translate technical complexity into boardroom-ready choices. The headline: the global metal bellows market is on a steady expansion path at roughly a 6.2% compound annual growth rate, rising from a mid‑hundreds USD million base in 2025 to a materially larger industry by the early 2030s. This preview explains why that growth is credible, where strategic risk clusters will concentrate, and how manufacturers, OEMs, and tiered suppliers should prioritize investments in 2026 to capture value.
Metal Bellows Market
Why 2026 is a Pivotal Year for Strategy
Three converging forces make 2026 a strategic inflection point. First, demand drivers across high‑precision segments — aerospace, semiconductor, and energy — are recovering into structurally higher baselines following cyclical softness earlier in the decade. Second, regulatory tightening and updated harmonized standards are raising compliance thresholds, imposing engineering and testing costs but also creating barriers to entry that incumbent producers can exploit. Third, raw material volatility and supply chain consolidation are compressing supplier options and compressing margin levers for producers who cannot adapt their procurement and design strategies.
Metal Bellows Market
For executives, the business question is straightforward: do you treat 2026 as a year to defend margin through operational efficiency, or a year to invest in capability upgrades (e.g., edge‑welding automation, qualification labs) that will underpin growth through the forecast horizon? The optimal path depends on your exposure to regulated, high‑value applications and on your relative position in the supplier concentration curve.
Metal Bellows Market
Market Trajectory: A Demand‑Side Synthesis
-
Growth profile: The market’s steady mid‑single‑digit CAGR reflects a mix of resilient replacement demand and incremental new demand from electrification, additive manufacturing supply chains, and higher‑temperature applications. The forecast envelope suggests a consistent climb from the 2025 base year into the early 2030s, driven by applications that value reliability and materials performance more than raw price.
-
Application mix matters: While commodity‑grade bellows continue to compete on price, the fastest value accrual occurs where design margins are defensible — specialty alloys, tight tolerances, and certified expansion joints for pressure systems. Buyers in regulated industries are willing to pay for demonstrated qualification and traceability.
-
Concentration signal: Market concentration data show a modestly consolidating industry: the top three and top five suppliers account for a meaningful share of revenue, underlining both the scale advantages of established players and the strategic room for regional or technical specialists to capture niche premium positions.
Competitive Dynamics — Who Wins and Why
The competitive landscape is heterogeneous, composed of long‑established western engineering houses, specialist U.S. edge‑welded producers, and cost‑focused manufacturers in Asia. Each cluster has distinct strategic playbooks:
-
Heritage engineering houses (e.g., UK and U.S. specialists): They win on application expertise, certification track records, and relationships in aerospace and power generation. Their chief advantage is the ability to monetize integrated assemblies and certified testing packages for safety‑critical uses.
-
High‑precision U.S. suppliers: These firms often focus on edge‑welded and electroformed bellows tailored to semiconductor and vacuum applications. Their proximity to key OEMs and control over manufacturing tolerances support premium pricing in cleanroom and vacuum environments.
-
Volume and cost players in Asia: Competitive on price and lead times for standard expansion joints and corrugated compensators, these producers expand through industrial piping and marine opportunities. Their trajectory depends on moving up the value chain via certifications and export credentials.
From a 2026 decision perspective, incumbents should prioritize: (a) accelerating qualification pathways that capture regulated contract wins, (b) selectively automating processes that reduce unit cost without degrading certification capability, and (c) tightening supply agreements for critical alloys to insulate margins.
Regulation, Standards and Certification: The New Baseline
Regulatory changes are not theoretical — they alter procurement and qualification calendars. The recent European harmonized standard for metal bellows expansion joints, updated into the mid‑2020s, tightens safety and testing expectations for pressure applications. Simultaneously, long‑standing directives covering pressure equipment continue to inform design verification and product liability exposure.
Implication for 2026: suppliers that already embed certified engineering processes will outcompete newcomers in regulated tenders. Buyers should demand evidence of harmonized standard compliance early in the RFQ phase to avoid costly late‑stage rework. Investors evaluating M&A opportunities should stress‑test target portfolios against the incremental CapEx and OPEX needed for compliance.
Raw Materials and Cost Volatility
Material choice drives performance and margin. Stainless steels remain the workhorse for many applications, but nickel and titanium alloys dominate where heat and chemical exposure demand superior properties. Those alloys introduce two operational realities: longer lead times and higher unit cost; and in some cases, slower approval cycles when used in regulated assemblies.
For 2026 planning, procurement teams must shift from reactive spot buying to multi‑tiered sourcing strategies: lock in strategic contracts for critical alloys, develop validated secondary suppliers, and explore alloy substitution where technically feasible. Engineering teams should quantify lifecycle benefits (reduced maintenance, longer MTBF) to justify alloy premium in customer quotes.
Practical Contents of the Full Report (What You Get)
Our full PW Consulting Metal Bellows report is designed for immediate operational use by strategic planners, commercial teams, and M&A professionals. It includes:
-
Robust market sizing and forward projections using a base year of 2025 and a forecast period through 2032, with transparent methodology and sensitivity scenarios;
-
Buyer decision maps for aerospace, semiconductor, oil & gas and power generation purchasers — including qualification timelines, sample inspection protocols, and contract negotiation levers;
-
Supply chain heat maps that identify single‑source risks, key alloy exposures and logistics bottlenecks;
-
Actionable pricing playbooks aligned to product type and application criticality, designed to help commercial teams defend margin while competing on value;
-
Scenario planning modules that quantify the P&L impact of certification costs, alloy price shocks, and demand shifts across high‑value end markets;
-
A competitive intelligence annex profiling leading suppliers with capability matrices, strategic strengths, and likely near‑term moves;
-
Integration checklists for M&A and partnership diligence, including recommended warranty frameworks and post‑acquisition integration milestones.
Company‑Level Strategic Readouts
Based on recent public developments and capability signals, the mid‑2020s competitive battlefield will reward firms that combine certification agility with focused product differentiation:
-
Specialist edge‑welded providers that serve aerospace and semiconductor clients should deepen engineering partnerships with major OEMs, institutionalize co‑development frameworks, and invest in cleanroom qualification racks.
-
Manufacturers of expansion joints and piping compensators should emphasize lifecycle cost models for buyers — showcasing inspection intervals and failure‑mode economics rather than competing solely on list price.
-
Regional manufacturers should prioritize accredited testing and export compliance to access high‑value western tenders, while also exploring modular manufacturing arrangements with global partners.
Recent Developments — Tactical Signals to Watch
Two developments provide immediate tactical cues: a new product line launch focused on high‑temperature applications by an established supplier, and the publication of an updated European harmonized standard for metal bellows used in pressure applications. Together they underscore a larger theme — technical innovation and regulatory alignment are co‑evolving, and firms that can demonstrate both will command privileged access to regulated projects.
How to Use This Research in a 2026 Playbook
-
For CEOs and CFOs: stress‑test CapEx plans against certification and alloy price scenarios included in our sensitivity modules. Use the market trajectory to justify selective capacity investments and to set realistic revenue milestones across regulated vs. commodity segments.
-
For Heads of Product and Engineering: map product roadmaps to buyer qualification cycles — prioritize resources for products with the best combination of technical defensibility and addressable market growth.
-
For Commercial Teams: rework RFP templates to require early proof of compliance with applicable harmonized standards; adopt value‑based quoting for safety‑critical assemblies.
-
For M&A and Partnerships: use the competitive annex and integration checklists to identify acquisition targets that close capability gaps (certification, alloy processing, application expertise) rather than simply adding volume.
Next Steps — Accessing the Full Intelligence
This preview is expressly structured to demonstrate analytic depth while preserving the granular segmentation and proprietary model outputs for the full report. If your strategic planning for 2026 depends on differentiated positioning — whether through technology investment, go‑to‑market changes, or M&A — the complete PW Consulting Metal Bellows Market study contains the structured scenarios, supplier scorecards, and procurement playbooks you will need.
Contact PW Consulting to arrange an executive briefing and to obtain the full dataset and modelling tools that underpin the conclusions summarized here. Use the briefing to align 2026 budgets, prioritize capability investments, and operationalize the scenarios most relevant to your end‑market exposure.
For detailed analysis of this topic, please visit the official page: Metal Bellows Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Aerial Work Platform (AWP) Market — Strategic Outlook for 2026 Decision‑Makers
As PW Consulting’s lead industry analyst, I present an executive preview of our newest Aerial Work Platform (AWP) market study — a pragmatic, decision‑focused playbook for executives, investors, and operations leaders preparing to act in 2026. The analysis synthesizes historical performance (2020–2025), establishes 2025 as the study’s base year, and projects through a 2026–2032 forecast window. At the macro level, the global AWP market is tracked in USD Billion, with measured growth from an estimated 9.32 in 2020 to approximately 12.85 in 2025, and a modeled expansion to roughly 19.85 by 2032 under a central case CAGR of 6.5% for the forecast period. These headline numbers frame a market that is both resilient and in the middle innings of structural transformation.
Aerial Work Platform (AWP) Market
Why this study matters in 2026
-
Strategic timing: 2026 is a pivotal year in which updated standards, rising input costs, and accelerating adoption of electrification and sensorization converge to reshape product roadmaps, procurement cycles, and rental fleet strategies. Organizations that align capital deployment and product investments to these inflection points will capture outsized returns.
Aerial Work Platform (AWP) Market -
Decision calibration: Whether your priority is CapEx allocation, rental fleet refresh, aftermarket services expansion, or M&A, the study provides scenario‑based lenses to stress‑test choices against regulatory and commodity shocks that are already altering unit economics.
Aerial Work Platform (AWP) Market -
Operational readiness: New training and equipment requirements elevate the importance of operator certification, telematics‑enabled maintenance, and supplier partnerships. This report turns regulatory change into operational checklists for 2026 rollouts.
What the report delivers — practical, implementable outputs
-
Scenario‑based demand models: Three forward scenarios (base, upside, downside) with transparent assumptions for macro growth drivers, rental penetration, and replacement cycles. These models are delivered in editable formats to support boardroom stress tests.
-
Investment and ROI playbooks: Capital planning tools for OEMs and rental companies, including lifecycle cost (TCO) templates, electrification payback analysis, and utilization thresholds that trigger fleet refresh decisions.
-
Regulatory impact maps: Precise operational implications of recently reapproved and updated standards, plus compliant implementation pathways for training, sensor integration, and safety retrofits.
-
Supply chain heatmaps: End‑to‑end views identifying single‑source exposure, raw‑material cost pass‑through risk (steel and electronic components), and recommended hedging and supplier diversification actions.
-
Competitive playbooks and an M&A scouting list: Relative positioning across portfolio breadth, technology capability, and aftermarket service footprints — framed to inform acquisition targets and alliance opportunities.
-
Performance dashboards and KPIs: Operational scorecards for rental utilization, maintenance intervals, spare parts inventory turns, and telematics adoption that translate to P&L sensitivities.
Market dynamics shaping 2026 strategy
-
Standards and training: The ANSI/SAIA A92 series updates effective in 2026 raise the bar on MEWP operator training, inspection protocols, and equipment features. Notably, new rules require enhanced wind‑speed sensing and specific requirements for railings and tire construction on outdoor and rough‑terrain models. For operators and OEMs, compliance is not a paper exercise — it will affect product specifications, aftermarket fitment programs, and training service revenues.
-
Input cost pressure: Semi‑finished steel prices have increased meaningfully (reflected in industry indices through early 2026), raising baseline chassis and structural component costs. Our models indicate that even modest, persistent steel cost increases materially compress gross margins unless mitigated through procurement strategies, local sourcing, or design optimization.
-
Technology evolution: Electromechanical drive systems, integrated sensor suites, and predictive maintenance telematics are migrating from premium options to core specifications in new builds and higher‑utilization rental fleets. The net effect is bifurcated: product ASPs rise, while lifecycle maintenance profiles improve — a trade that rewards OEMs and rental companies with differentiated service offerings.
-
Market structure: The AWP market remains moderately concentrated. Our concentration metrics show leading players holding a significant share of the addressable market (CR3 and CR5 figures are part of the report’s executive appendices). For fast followers and challengers, this concentration implies that scale in distribution, aftermarket reach, and rental partnerships are determinative of near‑term share gains.
-
Rental economics and utilization: Rental firms are recalibrating fleet mixes in response to urban construction patterns, infrastructure maintenance cycles, and the increased availability of electric variants. The economics of rental vs. free‑market purchase depend on utilization thresholds that our TCO models make explicit for several operator archetypes.
Competitive landscape — what to watch in 2026
The study includes a granular competitive assessment of core OEMs and regional champions. Highlights for strategic attention include:
-
MEC Aerial Work Platforms (Kerman, CA) — A focused specialist in electric scissor lifts, rough terrain booms, and compact mobile elevating equipment. MEC’s strengths are product depth in niche electric platforms and direct OEM relationships with rental operators targeting low‑emissions urban contracts.
-
Genie (Snoqualmie, WA) — A full‑spectrum player with broad reach across scissor and boom categories. Genie’s product breadth and distribution scale make it a bellwether for technology standardization and aftermarket penetration strategies.
-
JLG Industries (McConnellsburg, PA) — Notable for recent product launches that embed advanced sensors and contact‑free maintenance concepts into electric scissor platforms. JLG’s developments merit close observation for how OEMs commercialize safety and maintenance innovations as revenue drivers.
-
Terex Corporation (Greenwich, CT) — The completion of Terex’s merger with REV Group in early 2026 expands its specialty equipment footprint and positions the combined entity to pursue integrated fleet offers across adjacent vehicle classes.
-
Haulotte Group (Lorette, France) — Active in the powered access trade show circuit and focused on supporting rental companies with targeted AWP technologies. Haulotte’s channel activity signals a push to capture share in professional rental segments.
-
Tadano Ltd. (Tokyo, Japan) — Recently introduced modular mobile elevating platforms for North American markets manufactured in Japan; this reflects a strategy of leveraging high‑reliability manufacturing as a competitive differentiator in premium segments.
-
Zoomlion (Changsha, China) — A major developer of scissor, straight, and articulated booms with strong ties to large infrastructure projects. Zoomlion’s scale and cost competitiveness matter for global procurement strategies and pricing dynamics in emerging markets.
Recent developments to act upon
-
JLG’s mid‑2025 launch of an aviation‑package electric scissor lift with advanced sensing and contact‑free maintenance capabilities points to the first movers capturing aftermarket service revenues through embedded diagnostics.
-
Tadano’s early‑2025 product entries for North America signal renewed competition in machine reliability and regional manufacturing footprints — an important consideration for fleet planners seeking shorter lead times.
-
Terex’s 2026 merger activity redefines consolidation dynamics and will accelerate platform bundling opportunities across specialty equipment categories.
-
Participation of major OEMs at international trade events in 2026 underscores a synchronized push to support rental companies on technology adoption and compliance transitions.
Strategic imperatives for 2026
-
Embed regulatory compliance into product and service roadmaps now — treat ANSI/SAIA updates as product requirements, not after‑the‑fact retrofits.
-
Prioritize telematics and predictive maintenance in new fleet acquisitions to lower downtime and improve fleet economics; model the incremental ASP versus lifecycle savings for your specific utilization profile.
-
Mitigate raw‑material risk through diversified sourcing, long‑term supplier agreements, and design options that reduce steel intensity without compromising safety margins.
-
Reassess rental vs. ownership thresholds using our TCO templates — small changes in utilization or discount rates can flip the optimal capital strategy.
-
Scan acquisition targets for aftermarket service networks and telematics capabilities rather than only production capacity; service synergies are where consolidation unlocks margin expansion.
-
Launch operator training and certification programs aligned to the new standards to create a competitive advantage and reduce client switching costs.
How to use the full report
This preview surfaces the analytical spine and strategic takeaways. The complete PW Consulting AWP study includes the full set of sub‑segment revenue tables, regional and application breakdowns, supplier scorecards, and downloadable scenario models. In keeping with our “preview” approach, we intentionally withhold detailed sub‑segment revenue splits in this executive introduction — those figures, along with editable forecasting spreadsheets and supplier benchmarking matrices, are available in the full report.
For boards, Chief Engineers, and transaction teams operating on 2026 timelines, this study is designed to be the central reference that converts market rhythms into executable plans. To access the full dataset, complete models, and our bespoke advisory options, please visit the PW Consulting report landing page linked from our research catalog.
— PW Consulting, Strategic Advisory & Industry Analysis
For detailed analysis of this topic, please visit the official page: Aerial Work Platform (AWP) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Dyes Market Poised for 4.1% CAGR in 2026-2032 Forecast
By pmarketresearch, 2026-07-13
Dyes Market 2026: Strategic Signals for Decision-Makers — A PW Consulting Preview
Executive summary
As firms prepare their 2026 strategic plans, the dyes market presents a classic mix of steady expansion and accelerating structural change. Our latest market study — anchored on a 2025 base year and a comprehensive 2020–2025 historical review — finds the global dyes market at approximately USD 323.5 Million in 2025, with a steady compound annual growth rate (CAGR) of 4.1% projected through 2032 (reaching roughly USD 427 Million by 2032). This trajectory masks pronounced micro-trends: supply-chain fragility, regulatory tightening, a sustainability-driven product migration, and a competitive landscape where a handful of global majors coexist with nimble regional specialists.
Dyes Market
Why this preview matters for 2026 planning
Beyond headline growth, the 2026 planning cycle must reckon with tactical inflection points that could materially affect margins, market access, and capital allocation. Our report is written for boards, strategy teams, procurement heads, and business-unit leaders who must translate macro stability into resilient, near-term action. This preview highlights the strategic choices — sourcing, product portfolio, compliance, and M&A posture — that will determine which players capture disproportionate value as the market evolves.
Dyes Market
Market trajectory and what the numbers imply
The market’s mid-single-digit CAGR masks a nuanced picture. From a 2020 base through 2025, the market expanded steadily; the forecast period to 2032 assumes continuation of that pace, but with asymmetric upside tied to sustainability adoption and substitution dynamics. For executives, the implication is pragmatic: modest topline growth will reward operational excellence, while any ambition for outsized returns will require either capturing premiumization in specialty dyes or participating in consolidation and backward integration.
Dyes Market
Structural dynamics shaping 2026 decisions
-
Regulatory tightness and compliance costs — Regulatory actions continue to be a central constraint. Notable regulatory frameworks classify certain production streams as hazardous and prohibit specific high-risk chemistries. These rules raise both operating costs and barriers to entry in several markets. Expect compliance-driven CAPEX (effluent treatment, process containment, documentation systems) to be a line-item in capital budgets for 2026.
-
Raw-material volatility and procurement strategy — Price swings in aromatic intermediates and specialty chemicals have compressed margins historically and continue to do so. Procurement sophistication (multi-sourcing, hedging, long-term supplier agreements) and localized feedstock strategies will distinguish resilient operators from those exposed to margin shocks.
-
Sustainability-driven product shift — The market shows an accelerating preference for bio-based and low-VOC colorants, driven both by regulation and customer demand from downstream textile and consumer goods firms. This is creating a bifurcated market: commodity-grade dyes under margin pressure and specialty, lower-footprint solutions commanding premium pricing and customer lock-in.
-
Market concentration and competitive dynamics — The industry concentration is meaningful: the top three firms account for nearly half of market share, and the top five for approximately two-thirds. That structure fosters differentiated competitive plays: scale players focus on distribution, regulatory compliance, and integrated offerings; mid-sized and niche suppliers compete on formulation expertise, speed-to-market, and service for regional textile clusters.
-
Trade-show activity and commercial signaling — The 2026 trade calendar has shown robust participation across regional events, signaling sustained commercial engagement and active product launches. These forums remain important barometers for client demand, regulatory messaging, and buyer-supplier matchmaking.
Competitive landscape — implications for strategy
The industry features several global incumbents with broad portfolios and integrated manufacturing footprints, alongside regional champions and specialty innovators. Global producers bring scale, regulatory sophistication, and R&D resources; regional players — particularly in textile-cluster geographies — offer agility and cost advantages. For 2026, executives should evaluate competitive positions across three vectors:
-
Scale & integration: Large multinational producers leverage integrated value chains to stabilize margins and meet compliance expectations. This reduces exposure to intermediates' price swings but requires ongoing CAPEX and operational discipline.
-
Specialization & innovation: Specialty chemicals firms and independent innovators capture premium pockets where performance, sustainability claims, or formulation complexity matter. These firms can be attractive targets for strategic partnerships or acquisition if a buyer seeks rapid entry into premium segments.
-
Regional footprints & service models: Manufacturers rooted in textile hubs combine proximity-to-customer with tailored service models. Their value lies in shortened lead times and deep customer relationships — an asset in a market where time-to-color and compliance documentation increasingly influence procurement decisions.
What the PW Consulting report delivers (practical contents)
Our full report is designed as an operational playbook for 2026. Key deliverables include:
-
Validated market sizing and forward-looking scenario models (base case, regulatory-constrained, and accelerated-sustainability adoption) with sensitivity analytics tied to raw-material price paths.
-
Competitive benchmarking and capability heatmaps across manufacturing scale, regulatory readiness, R&D intensity, and distribution reach.
-
Supplier scorecards and a procurement playbook that includes hedging templates, long-term contracting frameworks, and nearshoring decision matrices.
-
Regulatory impact assessment and compliance roadmap, detailing required investments, timeline risks, and mitigation strategies for hazardous-stream classification and substance bans.
-
Innovation and portfolio optimization frameworks to prioritize investment in bio-based and low-VOC products, including product substitution matrices and go-to-market playbooks for premium segments.
-
M&A and partnership pipeline: target-screening criteria, synergy case templates, and transaction structuring guidance tailored for both buyers (scale seekers) and sellers (specialty innovators).
-
Executive dashboards and investor-ready slide decks for communicating strategy, capital requests, or divestiture rationales.
Strategic implications and recommended 2026 plays
Based on our analysis, executives should consider a portfolio of actions that combine offense and defense:
-
Defensive: Accelerate compliance investments now rather than react later. Early adopters of robust effluent and hazardous-stream controls will face lower regulatory interruption risk and can use compliance as a commercial differentiator.
-
Operational: Build procurement resilience via diversified sourcing, localized feedstock options, and disciplined hedging. Margins in a mid-single-digit growth market are fragile in the face of input volatility.
-
Offensive: Allocate a proportion of R&D and commercial resources to bio-based and low-VOC chemistries that command premium placement with brand-conscious downstream buyers. Consider strategic partnerships with textile and coatings customers for co-development and offtake agreements.
-
Portfolio: Evaluate bolt-on acquisitions of specialty firms to acquire formulation IP, regulatory dossiers, or regional channels — an efficient way to move upvalue without building in-house capabilities from scratch.
-
Commercial: Revisit pricing strategies and contract structures to reflect lifecycle costs, including compliance and waste treatment. Long-term supply agreements with escalators tied to input-cost indices can protect margins while preserving customer relationships.
-
Digitalization: Implement product traceability and documentation systems to streamline compliance reporting and service downstream traceability demands — these systems are increasingly required by brand and retail customers.
Risks to monitor going into 2026
-
Regulatory surprises — additional substance bans or reclassifications could accelerate substitution and shift demand away from legacy chemistries.
-
Raw-material shocks — prolonged spikes could force margin compression for firms without hedging or sourcing flexibility.
-
Consolidation waves — strategic M&A among majors could raise competitive barriers and alter pricing dynamics in both commoditized and premium pockets.
-
Market perception — failure to demonstrate credible sustainability credentials risks losing placement with global brands and retailers in key supply chains.
How to use this preview — next steps
This preview is deliberately focused on strategic implications; the full PW Consulting study contains the actionable datasets, segment-level modeling, and vendor dossiers needed to execute the plays above. For 2026 decision-making, we recommend three immediate steps:
-
Run a 90-day compliance & procurement health check: quantify exposure across regulatory, supplier, and price-risk dimensions and prioritize quick wins.
-
Commission a focused product-portfolio review to identify where to accelerate bio-based investments and where to rationalize legacy lines.
-
Engage with potential M&A or partnership targets identified using the criteria in our playbook to accelerate access to premium niches.
Closing — why PW Consulting
Our analysis combines market economics, granular regulatory intelligence, and transaction experience to help clients convert modest market growth into durable advantage. The dyes market’s steady expansion provides a stable backdrop, but the near-term winners will be those who manage risk, move decisively on sustainability, and deploy capital to close strategic gaps. For teams preparing 2026 budgets and strategic plans, the comprehensive datasets and executable playbooks in our full report will be essential. Visit our report page to access the full dataset, interactive dashboards, and bespoke consulting options tailored to your organization’s 2026 priorities.
For detailed analysis of this topic, please visit the official page: Dyes Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: E-Beam Accelerators Market to Reach USD 270 Million by 2032 (CAGR 4.15%)
By pmarketresearch, 2026-07-13
E‑Beam Accelerators Market — Strategic Insights for 2026 Decision‑Makers
Executive teaser
As PW Consulting’s Senior Strategy Advisor and Head Industry Analyst, I present a focused preview of our latest E Beam Accelerators Market study designed to sharpen executive decision‑making in 2026. The e‑beam sector is maturing into a defined industrial ecosystem: steady compound growth, concentrated supplier dynamics, and punctuated innovation events are creating discrete windows for commercial advantage. This briefing surfaces the strategic contours you need to assess investment timing, partner selection, and go‑to‑market design — while reserving the report’s tactical, segment‑level intelligence for the full study.
E Beam Accelerators Market
Market snapshot: trajectory and structure
Our base year is 2025. Over the 2020–2025 historical period, the market demonstrated resilient expansion, and the forecast through 2032 points to continued, moderate growth at a compound annual growth rate (CAGR) of approximately 4.15%. The study’s topline revenue trajectory — mapped year‑by‑year across the historical and forecast windows — shows progression from early‑decade volumes to a materially larger market in the early 2030s, reflecting both steady demand and incremental new use‑cases for e‑beam technologies.
E Beam Accelerators Market
Market structure is neither atomized nor monopolized. The top three suppliers account for a meaningful plurality of market sales, while the top five capture a clear majority — a market concentration profile that creates both bargaining power for incumbents and exploitable gaps for challengers with focused propositions (our study quantifies these concentration metrics precisely for strategy teams).
E Beam Accelerators Market
Why this matters for 2026 corporate strategy
- Capex and procurement timing: Moderate, predictable growth supports staged capital allocations rather than large, single‑phase investments. Decisions to retrofit lines, add irradiation capacity, or shift to higher energy classes should be aligned with the near‑term adoption curve we map.
- Partnering and M&A: A market where the top five vendors control a majority of volume creates attractive bolt‑on acquisition targets for established OEMs and strategic partnerships for industrial end users seeking turnkey capability.
- Service and differentiation: With hardware commoditization at the lower end and performance differentiation at higher energies, service models (maintenance, monitoring, irradiation as a service) become pivotal profit pools.
- Regulatory and market access: Compliance timelines and certification windows will materially affect rollout schedules — companies that anticipate regulatory gating can gain months of competitive advantage.
Key demand drivers and structural headwinds
- Driver — Cross‑sector adoption: Medical sterilization, polymer cross‑linking, food safety, and industrial materials processing continue to drive incremental e‑beam demand. Where regulatory or quality pressures increase, so does the case for in‑house or contracted irradiation capacity.
- Driver — Technology modularity: Advances in low‑voltage systems and modular integration lower entry barriers for new installation architectures, enabling broader on‑site adoption across manufacturing lines.
- Headwind — Capital intensity and lead times: High‑energy systems require significant engineering, shielding, and qualification, producing long sales cycles and making project timing critical.
- Headwind — Geopolitical and supply‑chain complexity: Cross‑border deliveries, export controls, and localization requirements can delay deployment and increase total cost of ownership.
Technology and use‑case developments to watch in 2026
- Low‑voltage proliferation: Low‑energy e‑beam systems continue to gain traction in packaging and coatings because of smaller footprints and lower installation cost.
- High‑power consolidation: High‑energy and Rhodotron‑class installations remain the domain of large projects — sterilization hubs, radiopharmaceutical production, and advanced materials processing — where uptime and throughput justify the expense.
- Service‑enabled differentiation: Remote monitoring, predictive maintenance, and irradiation process control (EPS monitoring systems) are emerging as decisive differentiators in procurement decisions.
- Regulatory alignment: Certification requirements for medical and food applications are tightening; vendors offering pre‑qualified, compliant solutions shorten time‑to‑market for customers.
Competitive landscape — profiles and strategic moves
The vendor field blends global incumbents, regional specialists, and engineering‑driven challengers. Below I summarise the strategic posture of core players highlighted in our research (the full report includes quantified capability matrices and channel maps).
- NHV Corporation (Japan) — A full‑spectrum manufacturer of electron beam processing systems, NHV combines product breadth (low through high energy) with integrated services. Recent activity shows an emphasis on operational stability tools — notably an EPS monitoring system placed under contract with a tire manufacturer — and active trade show engagement to secure wire and cable applications. Their playbook is platform stability + services, aimed at minimizing customer downtime and embedding long‑term ARR streams. ( https://www.nhv.jp/en/)
- CGN Dasheng Electron Accelerator Technology Co., Ltd. (China) — A vertically integrated designer and installer, CGN Dasheng is extending international reach; it recently delivered its first accelerator into the EU in collaboration with a research or technology center. Their strength lies in high‑volume project delivery and localized irradiation centers, which are attractive to regional industrial partners seeking capacity without extensive capex. ( http://www.en.cgndasheng.com/)
- Vivarad S.A. (France) — A specialist with a global installed base across mid and high‑energy systems, Vivarad’s operational footprint — including aftercare services across 300+ units — positions it as a trusted execution partner for industrial adopters seeking low‑risk deployments. ( https://www.vivirad.com/)
- Wasik Associates (United States) — Focused on custom, turn‑key systems at medium voltage ranges, Wasik targets wire, cable, and niche medical applications where bespoke integration and rapid turnaround are priorities.
- Mevex Corporation (Canada) — Mevex is notable for linear accelerator leadership and high‑power applications, positioning them for large sterilization and materials projects where technical performance is the primary procurement criterion. ( https://www.mevex.com/)
- IBA Industrial (Belgium) — With Rhodotron® solutions and large‑scale installations, IBA is a strategic partner for national‑scale irradiation projects; recent contracts show continued movement into industrial sterilization and radiopharmaceutical segments, and underline the importance of vendor credibility in regulated sectors. ( https://www.iba-industrial.com/)
- Energy Sciences Inc. (United States) — A leader in low‑voltage EB systems, Energy Sciences serves flexible packaging, coatings, and cross‑linking markets with compact, cost‑efficient solutions and well‑established service networks. ( https://www.ebeam.com/)
Collectively, these vendors illustrate two valid competitive approaches: (1) broad platform suppliers combining hardware + service to lock recurring revenue, and (2) specialized engineering houses that win on bespoke performance and rapid deployment. Our report maps capability overlaps, channel partnerships, and service economics to help buyers and investors prioritize counterparts.
Recent industry events shaping 2026 agendas
- Major vendors continue to expand export footprints and delivery capabilities — exemplified by cross‑border deliveries into Europe and large installations tied to sterilization hubs.
- Trade shows remain critical go‑to‑market venues: vendors use physical exhibitions to demonstrate process stability and secure line‑level integrations in wire, cable, and polymer applications.
- New service offerings — such as EPS monitoring systems — are moving from pilot to commercial contracts, indicating a market pivot toward performance guarantees and outcome‑based pricing.
- Regulatory and contract announcements for large irradiation systems (e.g., multi‑accelerator installations) signal that public and private capital will continue to back centralized sterilization and materials processing infrastructure.
What the PW Consulting report delivers (practical elements)
Our full study is built for practitioners who must make decisions in 2026. Deliverables include:
- Actionable investment frameworks for capex prioritization and phased deployment in production environments.
- Competitive capability matrices that score vendors across technology classes, service models, and compliance readiness.
- Procurement playbooks detailing contracting approaches, service level agreements, and risk mitigation for international deliveries.
- Scenario models linking adoption speed to price erosion, aftermarket revenue potential, and total cost of ownership across energy classes.
- Regulatory impact assessments and a compliance roadmap for medical and food applications.
- Confidential appendices: granular segmentation, downloadable vendor scorecards, and market share analytics (these are intentionally withheld from this preview to preserve the study’s tactical value).
Strategic recommendations for 2026
- Adopt a staged investment cadence: Align procurement with validated use‑cases and phased commissioning to avoid oversized initial capex and reduce technical risk exposure.
- Pursue service partnerships: Negotiate vendor contracts that include monitoring and performance guarantees; vendors that can bundle EPS monitoring and predictive maintenance will command premium positioning.
- Prioritize vendor due diligence: Evaluate suppliers not only on equipment performance but also on installation track record, spare parts logistics, and regional regulatory experience.
- Monitor consolidation opportunities: Given market concentration dynamics, strategic buyers should track mid‑tier engineering firms for bolt‑on acquisitions that close capability gaps quickly.
- Plan for regulatory gating: Integrate certification timelines into project plans to prevent time‑to‑market slippage, especially for medical and food applications.
How to use this preview
This briefing is a gateway: it frames the strategic choices and market mechanics you’ll need in 2026 but intentionally omits the granular segmentation tables and transaction‑level market shares that operational teams require. If you are evaluating capital allocation, vendor selection, or partnership strategies this year, the full PW Consulting study will provide the segment‑level intelligence, vendor scorecards, and quantitative models to translate these recommendations into executable plans.
Next steps
For an expedited executive briefing tailored to your organization’s role in the e‑beam value chain (OEM, end user, investor, or service provider), PW Consulting can deliver a 60‑minute strat session that pairs these strategic levers with confidential, client‑only appendices from the study. Contact our market intelligence team to schedule a briefing and obtain full access to the report’s operational playbooks, segmentation data, and vendor matrices.
For detailed analysis of this topic, please visit the official page: E Beam Accelerators Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com