

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: AWP Market Forecast — 6.5% CAGR to 2032

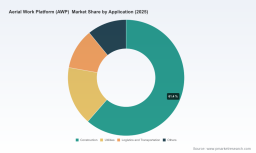
Aerial Work Platform (AWP) Market — Strategic Outlook for 2026 Decision‑Makers
As PW Consulting’s lead industry analyst, I present an executive preview of our newest Aerial Work Platform (AWP) market study — a pragmatic, decision‑focused playbook for executives, investors, and operations leaders preparing to act in 2026. The analysis synthesizes historical performance (2020–2025), establishes 2025 as the study’s base year, and projects through a 2026–2032 forecast window. At the macro level, the global AWP market is tracked in USD Billion, with measured growth from an estimated 9.32 in 2020 to approximately 12.85 in 2025, and a modeled expansion to roughly 19.85 by 2032 under a central case CAGR of 6.5% for the forecast period. These headline numbers frame a market that is both resilient and in the middle innings of structural transformation.
Aerial Work Platform (AWP) Market
Why this study matters in 2026
-
Strategic timing: 2026 is a pivotal year in which updated standards, rising input costs, and accelerating adoption of electrification and sensorization converge to reshape product roadmaps, procurement cycles, and rental fleet strategies. Organizations that align capital deployment and product investments to these inflection points will capture outsized returns.
Aerial Work Platform (AWP) Market -
Decision calibration: Whether your priority is CapEx allocation, rental fleet refresh, aftermarket services expansion, or M&A, the study provides scenario‑based lenses to stress‑test choices against regulatory and commodity shocks that are already altering unit economics.
Aerial Work Platform (AWP) Market -
Operational readiness: New training and equipment requirements elevate the importance of operator certification, telematics‑enabled maintenance, and supplier partnerships. This report turns regulatory change into operational checklists for 2026 rollouts.
What the report delivers — practical, implementable outputs
-
Scenario‑based demand models: Three forward scenarios (base, upside, downside) with transparent assumptions for macro growth drivers, rental penetration, and replacement cycles. These models are delivered in editable formats to support boardroom stress tests.
-
Investment and ROI playbooks: Capital planning tools for OEMs and rental companies, including lifecycle cost (TCO) templates, electrification payback analysis, and utilization thresholds that trigger fleet refresh decisions.
-
Regulatory impact maps: Precise operational implications of recently reapproved and updated standards, plus compliant implementation pathways for training, sensor integration, and safety retrofits.
-
Supply chain heatmaps: End‑to‑end views identifying single‑source exposure, raw‑material cost pass‑through risk (steel and electronic components), and recommended hedging and supplier diversification actions.
-
Competitive playbooks and an M&A scouting list: Relative positioning across portfolio breadth, technology capability, and aftermarket service footprints — framed to inform acquisition targets and alliance opportunities.
-
Performance dashboards and KPIs: Operational scorecards for rental utilization, maintenance intervals, spare parts inventory turns, and telematics adoption that translate to P&L sensitivities.
Market dynamics shaping 2026 strategy
-
Standards and training: The ANSI/SAIA A92 series updates effective in 2026 raise the bar on MEWP operator training, inspection protocols, and equipment features. Notably, new rules require enhanced wind‑speed sensing and specific requirements for railings and tire construction on outdoor and rough‑terrain models. For operators and OEMs, compliance is not a paper exercise — it will affect product specifications, aftermarket fitment programs, and training service revenues.
-
Input cost pressure: Semi‑finished steel prices have increased meaningfully (reflected in industry indices through early 2026), raising baseline chassis and structural component costs. Our models indicate that even modest, persistent steel cost increases materially compress gross margins unless mitigated through procurement strategies, local sourcing, or design optimization.
-
Technology evolution: Electromechanical drive systems, integrated sensor suites, and predictive maintenance telematics are migrating from premium options to core specifications in new builds and higher‑utilization rental fleets. The net effect is bifurcated: product ASPs rise, while lifecycle maintenance profiles improve — a trade that rewards OEMs and rental companies with differentiated service offerings.
-
Market structure: The AWP market remains moderately concentrated. Our concentration metrics show leading players holding a significant share of the addressable market (CR3 and CR5 figures are part of the report’s executive appendices). For fast followers and challengers, this concentration implies that scale in distribution, aftermarket reach, and rental partnerships are determinative of near‑term share gains.
-
Rental economics and utilization: Rental firms are recalibrating fleet mixes in response to urban construction patterns, infrastructure maintenance cycles, and the increased availability of electric variants. The economics of rental vs. free‑market purchase depend on utilization thresholds that our TCO models make explicit for several operator archetypes.
Competitive landscape — what to watch in 2026
The study includes a granular competitive assessment of core OEMs and regional champions. Highlights for strategic attention include:
-
MEC Aerial Work Platforms (Kerman, CA) — A focused specialist in electric scissor lifts, rough terrain booms, and compact mobile elevating equipment. MEC’s strengths are product depth in niche electric platforms and direct OEM relationships with rental operators targeting low‑emissions urban contracts.
-
Genie (Snoqualmie, WA) — A full‑spectrum player with broad reach across scissor and boom categories. Genie’s product breadth and distribution scale make it a bellwether for technology standardization and aftermarket penetration strategies.
-
JLG Industries (McConnellsburg, PA) — Notable for recent product launches that embed advanced sensors and contact‑free maintenance concepts into electric scissor platforms. JLG’s developments merit close observation for how OEMs commercialize safety and maintenance innovations as revenue drivers.
-
Terex Corporation (Greenwich, CT) — The completion of Terex’s merger with REV Group in early 2026 expands its specialty equipment footprint and positions the combined entity to pursue integrated fleet offers across adjacent vehicle classes.
-
Haulotte Group (Lorette, France) — Active in the powered access trade show circuit and focused on supporting rental companies with targeted AWP technologies. Haulotte’s channel activity signals a push to capture share in professional rental segments.
-
Tadano Ltd. (Tokyo, Japan) — Recently introduced modular mobile elevating platforms for North American markets manufactured in Japan; this reflects a strategy of leveraging high‑reliability manufacturing as a competitive differentiator in premium segments.
-
Zoomlion (Changsha, China) — A major developer of scissor, straight, and articulated booms with strong ties to large infrastructure projects. Zoomlion’s scale and cost competitiveness matter for global procurement strategies and pricing dynamics in emerging markets.
Recent developments to act upon
-
JLG’s mid‑2025 launch of an aviation‑package electric scissor lift with advanced sensing and contact‑free maintenance capabilities points to the first movers capturing aftermarket service revenues through embedded diagnostics.
-
Tadano’s early‑2025 product entries for North America signal renewed competition in machine reliability and regional manufacturing footprints — an important consideration for fleet planners seeking shorter lead times.
-
Terex’s 2026 merger activity redefines consolidation dynamics and will accelerate platform bundling opportunities across specialty equipment categories.
-
Participation of major OEMs at international trade events in 2026 underscores a synchronized push to support rental companies on technology adoption and compliance transitions.
Strategic imperatives for 2026
-
Embed regulatory compliance into product and service roadmaps now — treat ANSI/SAIA updates as product requirements, not after‑the‑fact retrofits.
-
Prioritize telematics and predictive maintenance in new fleet acquisitions to lower downtime and improve fleet economics; model the incremental ASP versus lifecycle savings for your specific utilization profile.
-
Mitigate raw‑material risk through diversified sourcing, long‑term supplier agreements, and design options that reduce steel intensity without compromising safety margins.
-
Reassess rental vs. ownership thresholds using our TCO templates — small changes in utilization or discount rates can flip the optimal capital strategy.
-
Scan acquisition targets for aftermarket service networks and telematics capabilities rather than only production capacity; service synergies are where consolidation unlocks margin expansion.
-
Launch operator training and certification programs aligned to the new standards to create a competitive advantage and reduce client switching costs.
How to use the full report
This preview surfaces the analytical spine and strategic takeaways. The complete PW Consulting AWP study includes the full set of sub‑segment revenue tables, regional and application breakdowns, supplier scorecards, and downloadable scenario models. In keeping with our “preview” approach, we intentionally withhold detailed sub‑segment revenue splits in this executive introduction — those figures, along with editable forecasting spreadsheets and supplier benchmarking matrices, are available in the full report.
For boards, Chief Engineers, and transaction teams operating on 2026 timelines, this study is designed to be the central reference that converts market rhythms into executable plans. To access the full dataset, complete models, and our bespoke advisory options, please visit the PW Consulting report landing page linked from our research catalog.
— PW Consulting, Strategic Advisory & Industry Analysis
For detailed analysis of this topic, please visit the official page: Aerial Work Platform (AWP) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com