

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: E-Beam Accelerators Market to Reach USD 270 Million by 2032 (CAGR 4.15%)

E‑Beam Accelerators Market — Strategic Insights for 2026 Decision‑Makers
Executive teaser
As PW Consulting’s Senior Strategy Advisor and Head Industry Analyst, I present a focused preview of our latest E Beam Accelerators Market study designed to sharpen executive decision‑making in 2026. The e‑beam sector is maturing into a defined industrial ecosystem: steady compound growth, concentrated supplier dynamics, and punctuated innovation events are creating discrete windows for commercial advantage. This briefing surfaces the strategic contours you need to assess investment timing, partner selection, and go‑to‑market design — while reserving the report’s tactical, segment‑level intelligence for the full study.
E Beam Accelerators Market
Market snapshot: trajectory and structure
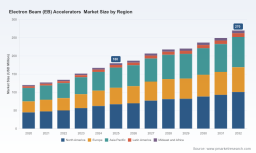
Our base year is 2025. Over the 2020–2025 historical period, the market demonstrated resilient expansion, and the forecast through 2032 points to continued, moderate growth at a compound annual growth rate (CAGR) of approximately 4.15%. The study’s topline revenue trajectory — mapped year‑by‑year across the historical and forecast windows — shows progression from early‑decade volumes to a materially larger market in the early 2030s, reflecting both steady demand and incremental new use‑cases for e‑beam technologies.
E Beam Accelerators Market
Market structure is neither atomized nor monopolized. The top three suppliers account for a meaningful plurality of market sales, while the top five capture a clear majority — a market concentration profile that creates both bargaining power for incumbents and exploitable gaps for challengers with focused propositions (our study quantifies these concentration metrics precisely for strategy teams).
E Beam Accelerators Market
Why this matters for 2026 corporate strategy
- Capex and procurement timing: Moderate, predictable growth supports staged capital allocations rather than large, single‑phase investments. Decisions to retrofit lines, add irradiation capacity, or shift to higher energy classes should be aligned with the near‑term adoption curve we map.
- Partnering and M&A: A market where the top five vendors control a majority of volume creates attractive bolt‑on acquisition targets for established OEMs and strategic partnerships for industrial end users seeking turnkey capability.
- Service and differentiation: With hardware commoditization at the lower end and performance differentiation at higher energies, service models (maintenance, monitoring, irradiation as a service) become pivotal profit pools.
- Regulatory and market access: Compliance timelines and certification windows will materially affect rollout schedules — companies that anticipate regulatory gating can gain months of competitive advantage.
Key demand drivers and structural headwinds
- Driver — Cross‑sector adoption: Medical sterilization, polymer cross‑linking, food safety, and industrial materials processing continue to drive incremental e‑beam demand. Where regulatory or quality pressures increase, so does the case for in‑house or contracted irradiation capacity.
- Driver — Technology modularity: Advances in low‑voltage systems and modular integration lower entry barriers for new installation architectures, enabling broader on‑site adoption across manufacturing lines.
- Headwind — Capital intensity and lead times: High‑energy systems require significant engineering, shielding, and qualification, producing long sales cycles and making project timing critical.
- Headwind — Geopolitical and supply‑chain complexity: Cross‑border deliveries, export controls, and localization requirements can delay deployment and increase total cost of ownership.
Technology and use‑case developments to watch in 2026
- Low‑voltage proliferation: Low‑energy e‑beam systems continue to gain traction in packaging and coatings because of smaller footprints and lower installation cost.
- High‑power consolidation: High‑energy and Rhodotron‑class installations remain the domain of large projects — sterilization hubs, radiopharmaceutical production, and advanced materials processing — where uptime and throughput justify the expense.
- Service‑enabled differentiation: Remote monitoring, predictive maintenance, and irradiation process control (EPS monitoring systems) are emerging as decisive differentiators in procurement decisions.
- Regulatory alignment: Certification requirements for medical and food applications are tightening; vendors offering pre‑qualified, compliant solutions shorten time‑to‑market for customers.
Competitive landscape — profiles and strategic moves
The vendor field blends global incumbents, regional specialists, and engineering‑driven challengers. Below I summarise the strategic posture of core players highlighted in our research (the full report includes quantified capability matrices and channel maps).
- NHV Corporation (Japan) — A full‑spectrum manufacturer of electron beam processing systems, NHV combines product breadth (low through high energy) with integrated services. Recent activity shows an emphasis on operational stability tools — notably an EPS monitoring system placed under contract with a tire manufacturer — and active trade show engagement to secure wire and cable applications. Their playbook is platform stability + services, aimed at minimizing customer downtime and embedding long‑term ARR streams. ( https://www.nhv.jp/en/)
- CGN Dasheng Electron Accelerator Technology Co., Ltd. (China) — A vertically integrated designer and installer, CGN Dasheng is extending international reach; it recently delivered its first accelerator into the EU in collaboration with a research or technology center. Their strength lies in high‑volume project delivery and localized irradiation centers, which are attractive to regional industrial partners seeking capacity without extensive capex. ( http://www.en.cgndasheng.com/)
- Vivarad S.A. (France) — A specialist with a global installed base across mid and high‑energy systems, Vivarad’s operational footprint — including aftercare services across 300+ units — positions it as a trusted execution partner for industrial adopters seeking low‑risk deployments. ( https://www.vivirad.com/)
- Wasik Associates (United States) — Focused on custom, turn‑key systems at medium voltage ranges, Wasik targets wire, cable, and niche medical applications where bespoke integration and rapid turnaround are priorities.
- Mevex Corporation (Canada) — Mevex is notable for linear accelerator leadership and high‑power applications, positioning them for large sterilization and materials projects where technical performance is the primary procurement criterion. ( https://www.mevex.com/)
- IBA Industrial (Belgium) — With Rhodotron® solutions and large‑scale installations, IBA is a strategic partner for national‑scale irradiation projects; recent contracts show continued movement into industrial sterilization and radiopharmaceutical segments, and underline the importance of vendor credibility in regulated sectors. ( https://www.iba-industrial.com/)
- Energy Sciences Inc. (United States) — A leader in low‑voltage EB systems, Energy Sciences serves flexible packaging, coatings, and cross‑linking markets with compact, cost‑efficient solutions and well‑established service networks. ( https://www.ebeam.com/)
Collectively, these vendors illustrate two valid competitive approaches: (1) broad platform suppliers combining hardware + service to lock recurring revenue, and (2) specialized engineering houses that win on bespoke performance and rapid deployment. Our report maps capability overlaps, channel partnerships, and service economics to help buyers and investors prioritize counterparts.
Recent industry events shaping 2026 agendas
- Major vendors continue to expand export footprints and delivery capabilities — exemplified by cross‑border deliveries into Europe and large installations tied to sterilization hubs.
- Trade shows remain critical go‑to‑market venues: vendors use physical exhibitions to demonstrate process stability and secure line‑level integrations in wire, cable, and polymer applications.
- New service offerings — such as EPS monitoring systems — are moving from pilot to commercial contracts, indicating a market pivot toward performance guarantees and outcome‑based pricing.
- Regulatory and contract announcements for large irradiation systems (e.g., multi‑accelerator installations) signal that public and private capital will continue to back centralized sterilization and materials processing infrastructure.
What the PW Consulting report delivers (practical elements)
Our full study is built for practitioners who must make decisions in 2026. Deliverables include:
- Actionable investment frameworks for capex prioritization and phased deployment in production environments.
- Competitive capability matrices that score vendors across technology classes, service models, and compliance readiness.
- Procurement playbooks detailing contracting approaches, service level agreements, and risk mitigation for international deliveries.
- Scenario models linking adoption speed to price erosion, aftermarket revenue potential, and total cost of ownership across energy classes.
- Regulatory impact assessments and a compliance roadmap for medical and food applications.
- Confidential appendices: granular segmentation, downloadable vendor scorecards, and market share analytics (these are intentionally withheld from this preview to preserve the study’s tactical value).
Strategic recommendations for 2026
- Adopt a staged investment cadence: Align procurement with validated use‑cases and phased commissioning to avoid oversized initial capex and reduce technical risk exposure.
- Pursue service partnerships: Negotiate vendor contracts that include monitoring and performance guarantees; vendors that can bundle EPS monitoring and predictive maintenance will command premium positioning.
- Prioritize vendor due diligence: Evaluate suppliers not only on equipment performance but also on installation track record, spare parts logistics, and regional regulatory experience.
- Monitor consolidation opportunities: Given market concentration dynamics, strategic buyers should track mid‑tier engineering firms for bolt‑on acquisitions that close capability gaps quickly.
- Plan for regulatory gating: Integrate certification timelines into project plans to prevent time‑to‑market slippage, especially for medical and food applications.
How to use this preview
This briefing is a gateway: it frames the strategic choices and market mechanics you’ll need in 2026 but intentionally omits the granular segmentation tables and transaction‑level market shares that operational teams require. If you are evaluating capital allocation, vendor selection, or partnership strategies this year, the full PW Consulting study will provide the segment‑level intelligence, vendor scorecards, and quantitative models to translate these recommendations into executable plans.
Next steps
For an expedited executive briefing tailored to your organization’s role in the e‑beam value chain (OEM, end user, investor, or service provider), PW Consulting can deliver a 60‑minute strat session that pairs these strategic levers with confidential, client‑only appendices from the study. Contact our market intelligence team to schedule a briefing and obtain full access to the report’s operational playbooks, segmentation data, and vendor matrices.
For detailed analysis of this topic, please visit the official page: E Beam Accelerators Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com