

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Ferrite Magnets Market to Reach USD 8,413M by 2032 at 6.5% CAGR

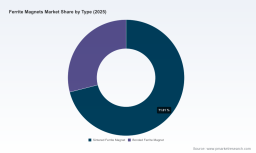
Ferrite Magnets Market — 2026 Strategic Outlook: Actionable Intelligence for Executive Decision-Making
Executive snapshot
The Ferrite Magnets market is at an inflection point. After expanding from a global market value of approximately USD 4.0 billion in 2020 to roughly USD 5.48 billion in the base year 2025, the sector is projected to continue to grow through the coming decade. Our forecast shows the market reaching an estimated USD 8.41 billion by 2032, driven by a mid-single-digit compounded annual growth rate (6.5% CAGR across the 2026–2032 forecast window). For corporate leaders, procurement heads and strategy teams preparing plans for 2026, this trajectory signals both expanding demand and intensifying competitive pressure — a combination that rewards clarity of positioning, supply-chain resilience and targeted investment in product differentiation.
Ferrite Magnets Market
Why 2026 matters: a strategic inflection
-
Base-year alignment and planning horizon. With 2025 serving as our analytical baseline and 2026 marking the start of the forecast window, companies must translate historical recovery patterns into forward-looking choices: where to allocate R&D, how to structure supplier networks, and which customer verticals to prioritize.
Ferrite Magnets Market -
Regulation and sustainability as cost and market drivers. Stricter environmental standards — particularly in Europe — are already reshaping production footprints and capital allocation. Regulations are pushing manufacturers to adopt lower-carbon processes and eco-friendlier inputs, altering total cost of ownership for product lines.
Ferrite Magnets Market -
Supply-chain rebalancing under tariff and raw-material volatility. Tariff shifts and raw-material price moves have made sourcing economics more dynamic; procurement strategies that were optimal in 2022–24 are frequently suboptimal entering 2026.
Market dynamics that will shape 2026 decisions
Three systemic forces will dominate corporate choices in 2026:
-
Input-price sensitivity. The ferrite value chain is tightly coupled to a narrow set of raw materials. Changes in the costs of key inputs such as strontium carbonate and iron oxides directly affect finished-goods pricing, margin volatility and competitive positioning. Procurement teams must therefore pair traditional cost-management tactics with financial hedging or long-term offtake arrangements to stabilize margins.
-
Regulatory and compliance pressure. Regional regulations are increasingly binding. European decarbonization goals — which are driving manufacturers to target substantial emissions reductions via process optimization — are an operational imperative rather than a reputational option. Separately, a significant share of manufacturers report ongoing difficulties achieving consistent compliance, creating an outsized opportunity for first movers who can certify low-carbon production at scale.
-
Geopolitics and tariffs. Elevated tariff regimes in major markets have already shifted sourcing calculus and increased incentive for near-shoring or onshoring higher-value manufacturing steps. Strategic decisions regarding plant location, contract manufacturing partners and inventory buffering will have outsized P&L implications in 2026.
Competitive landscape — what market structure implies for strategy
The market shows a moderate level of concentration: the three largest players capture a meaningful but non-dominant share of global shipments, while the five largest firms account for a sizable majority of market power. This structure creates a two-track competitive environment: a top-tier arena where scale, integrated supply chains and broad product portfolios matter; and a secondary terrain where specialization, speed-to-spec and customer intimacy can secure attractive margins.
Key participants and strategic positioning insights:
-
TDK Corporation — leveraging oxide-sintered powder metallurgy and microstructure control to compete on performance. TDK’s FB Series underscores an approach that blends manufacturing sophistication with diversified end-market reach (automotive, electronics and industrial). Their advantage: deep process know-how and a product roadmap aligned to sensor and high-performance motor use-cases.
-
Proterial, Ltd. — focused on high-performance ferrite technologies optimized for electrified powertrains. Their work on traction-motor-optimized magnet series positions them squarely within the xEV supplier ecosystem where torque-density and thermal stability are premium attributes.
-
Ferroxcube — prominent in soft ferrite cores and high-frequency magnetics for EMI suppression and power-electronics. Ferroxcube’s domain expertise signals an adjacency play: vertical migration from components toward systems-level magnetics in power-conversion applications.
-
Arnold Magnetic Technologies — a diversified player in bonded and sintered products and assemblies, known for flexible strip technologies and small-batch precision for motors and sensors. Arnold’s strength is custom engineering and integration services that shorten OEM development cycles.
-
Hengdian Group DMEGC — a scale leader and global producer of hard ferrite; their cost position and capacity footprint make them a natural partner for volume-driven OEMs and a competitive pressure point on commoditized components.
-
Electron Energy Corporation — specialty supplier focused on high-reliability aerospace, defense and mission-critical industrial applications. Their value proposition is performance-certification and traceability rather than cost leadership.
Strategic playbook for 2026
Executives preparing budgets and strategic roadmaps for 2026 should consider the following, prioritized by expected near-term ROI and risk mitigation effectiveness:
-
Hedge and diversify raw-material exposure. Implement layered hedging, longer-term supply contracts and dual-sourcing arrangements for critical inputs. Integrate raw-material scenarios into product pricing and warranty frameworks.
-
Invest selectively in low-carbon process upgrades. Prioritize process changes that deliver both emissions reductions and unit-cost advantages (energy efficiency, kiln modernization, waste reduction). Use sustainability credentials as a commercial differentiator in regulated markets.
-
Calibrate manufacturing footprints. Reassess the trade-offs between scale and proximity. For firms exposed to tariff regimes, localized assembly or final-processing capacity can preserve margin and shorten lead times.
-
Pursue adjacent-cluster specialization. Identify high-margin niches (e.g., traction motors, high-frequency power electronics, aerospace-grade assemblies) where product differentiation and certification barriers protect value.
-
Design for modularity and serviceability. Offer magnet modules and assemblies that reduce integration costs for OEMs and increase switching costs in multi-sourcing scenarios.
-
Use scenario-driven capital allocation. Tie CAPEX plans to scenario triggers: raw-material price bands, tariff changes, and certification timelines. This keeps balance sheets flexible while preserving optionality.
What PW Consulting’s full Ferrite Magnets Market report delivers
Our research is built to be directly operational for 2026 planning cycles. The full report includes:
-
A detailed market model (base year 2025) and a 2026–2032 forecast built on a rigorous, transparent methodology — including sensitivity scenarios for raw materials, tariffs and regulatory change.
-
Commercial playbooks for OEMs, magnet producers and component integrators that translate macro outlooks into product, pricing and go-to-market actions.
-
Supplier maps, cost-curve analyses and pricing models designed to support procurement negotiations and margin recovery plans.
-
Competitive heatmaps and an M&A shortlist, informed by market-concentration metrics and firm-level capabilities — enabling faster due diligence.
-
Technology and IP landscape coverage with implications for product roadmaps and partnership strategies across automotive, consumer electronics, industrial and aerospace segments.
-
Regulatory compliance playbooks and a sustainability roadmap aligned to the latest emissions-target requirements across major jurisdictions.
Note: this article intentionally summarizes the directional insights from our research. Detailed segment-level numbers, regional allocations and application-specific financials are available exclusively in the full report and accompanying datasets.
How to convert insight into advantage in 2026
-
Translate market modeling into actionable KPIs. Use supply-risk scores, material cost-per-unit sensitivity and time-to-certification metrics to prioritize projects.
-
Integrate procurement and R&D planning. Co-locate procurement, process engineering and customer-development resources to accelerate product qualification cycles for high-growth end-markets.
-
Use M&A as a capability acceleration lever. Given a market structure where larger players control meaningful share but pockets of specialist capability remain fragmented, bolt-on acquisitions can rapidly close capability gaps in magnet chemistry, assembly or certification domains.
-
Measure and manage regulatory-forward exposure. Build an early-warning dashboard tying regulatory developments and carbon-cost estimates to production-location decisions and client-contract clauses.
Conclusion — what to act on now
For executives whose 2026 plans will determine market positioning through the end of the decade, the window for decisive action is narrow. The broad market is growing at a steady mid-single-digit rate (6.5% CAGR across 2026–2032), creating both volume opportunities and margin pressure. The firms that will outperform are those who convert macro visibility into operational commitments: hedged supply chains; sustainable process investments that cut long-term cost; and focused product strategies aimed at high-value applications. For teams building 2026 budgets and three-year roadmaps, the imperative is to align commercial, sourcing and technical investments around scenarios that capture upside while controlling downside from raw-material volatility, regulation and evolving trade dynamics.
To access the full dataset, the detailed segment and regional analysis, and a customizable set of decision-support tools designed for 2026 strategy cycles, visit our report page or contact PW Consulting’s Ferrite Magnets practice for a briefing tailored to your business questions.
For detailed analysis of this topic, please visit the official page: Ferrite Magnets Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com