

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
Same-Day Delivery to Reach USD 55.22B by 2032, Growing at a 20.96% CAGR — PW Consulting Insight
By pmarketresearch, 2026-07-13
Same‑day Delivery Market: Strategic Imperatives for 2026 — A PW Consulting Preview
Executive snapshot
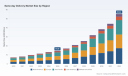
The same‑day delivery sector has moved from a competitive differentiator to a core operating requirement for retail, grocery, healthcare, and B2B value chains. PW Consulting’s latest market study (base year 2025) shows the market accelerating at a compound annual growth rate of 20.96% through our 2026–2032 forecast horizon. After roughly doubling in size from 2020 to 2025, total market revenue in 2025 stood at USD 14.59 Billion and — under our central scenario — is projected to exceed USD 55 Billion by 2032. That pace creates both strategic urgency and lucrative opportunity for organizations crafting their 2026 resource allocations.
Same-day Delivery Market
Why this study matters to decisions you will make in 2026
-
Timing: With consumer expectations and enterprise capability converging, 2026 is a pivotal year for committing capital and operational models. Quick moves now capture outsized market share while late entrants face higher customer acquisition costs and steeper margins pressure.
Same-day Delivery Market -
Risk management: Regulatory changes and labor re‑pricing are crystallizing. Our analysis synthesizes outcomes across alternative labor regimes and crowdsourced hybrid models, enabling CFOs and COOs to stress‑test capital and operating budgets against plausible 2026 policy shifts.
Same-day Delivery Market -
Vendor strategy: The market remains relatively unconcentrated by global incumbents (top‑three players account for a minority share of global volumes). This fragmentation means differentiated partnership strategies and local scale plays can be decisive — especially where last‑mile margins vary dramatically.
Market dynamics shaping 2026 strategy
-
Demand elasticity and consumer willingness to pay: Our consumer modelling shows a persistent premium for immediacy — a majority of buyers expect same‑day options and a meaningful subset will pay extra for faster fulfilment. Pricing architecture that captures that premium without eroding conversion will be a top strategic lever for 2026.
-
Network topology evolution: We identify a clear shift toward hybridization — conversion of rural stations into micro‑hubs, increased use of ship‑from‑store, and wider deployment of micro‑fulfillment centers. These changes reduce door‑to‑door times but require capital, cross‑functional redesign, and new inventory policies.
-
Workforce and regulatory friction: Local ordinances and renewed scrutiny of gig employment models are changing the cost calculus of crowdsourced fleets. Operators that secure compliant contracts, invest in driver safety/certification, and build flexible staffing models will preserve margin and service quality.
-
Service differentiation: The space is expanding beyond groceries and food into apparel, electronics, urgent B2B parts and healthcare deliveries. This product mix diversity demands tailored handling, routing, and SLA frameworks — and differentiates winners from commodity carriers.
Competitive landscape — who is shaping same‑day today
The sector features a mix of global integrators, national retailers with captive networks, and platform‑based crowdsourced players. Key market actors include Amazon, FedEx, UPS (including the Roadie platform), Walmart (and Sam’s Club), Target, DoorDash, Instacart, Shipt, and Roadie — each pursuing distinct strategies that together map an evolving competitive topology.
-
Amazon continues to scale depth and density, converting local stations into hybrid hubs to broaden reach and shorten fulfilment windows — a move that materially expands viable same‑day catchments for Prime members in smaller population centers.
-
Traditional carriers (FedEx, UPS) are layering time‑definite same‑day products and integrating crowdsourced capacity to serve ad‑hoc surges and special SKUs, balancing speed with cost control.
-
National retailers (Walmart, Target and Sam’s Club) are leveraging store networks for inventory proximity and experimenting with sub‑hour delivery in dense corridors, making store operations a critical point of strategic investment.
-
Platform players (DoorDash, Instacart, Shipt, Roadie) are extending beyond food into retail fulfilment, offering low‑friction retail partnerships and on‑demand capacity that reduce time‑to‑market for brands seeking same‑day presence.
Notable 2026 developments that influenced our analysis include Amazon’s push into thousands of smaller towns via hybrid hubs (Feb 2026), FedEx’s new time‑definite SameDay Local product (Mar 2026), Sam’s Club debuting 1‑hour delivery (Mar 2026), Target expanding next‑day reach (May 2026), and DoorDash widening retail partnerships (Apr 2026). These moves illustrate two intersecting trends: geographic densification of same‑day supply and product category expansion into mainstream retail.
What PW Consulting’s report contains (practical, executable intelligence)
-
Robust market sizing and scenarios — top‑down and bottom‑up approaches calibrated to 2020–2025 realized flows, with sensitivity analyses across three adoption trajectories through 2032.
-
Segment economics and cost‑to‑serve models — modular spreadsheets that allow you to toggle labour regimes, vehicle mixes, average order values, and fulfilment radii to produce bespoke unit economics.
-
Network design playbook — site selection criteria for micro‑fulfilment and hybrid hub conversion, inventory allocation heuristics, and a phased rollout template that minimizes service disruption.
-
Vendor and partnership matrix — evaluation criteria and scoring for carriers, platform partners, and technology vendors (including integration complexity, SLA performance, commercial terms, and scalability).
-
Regulatory and labour impact module — scenario outputs that quantify margin sensitivity to wage changes, certification costs, and gig‑work policy permutations.
-
Operational KPIs and 90‑day pilot templates — defined metrics (cost per order, same‑day attach rate, AOV lift, on‑time SLA, driver utilization) and a sprint plan to test hypotheses with minimal capital outlay.
-
Investor and board‑ready slide pack — concise recommendations, upside/downside cases, and trigger points for escalation or additional investment.
Actionable recommendations for 2026 (for CEOs, COOs, CPOs, and Heads of Logistics)
-
Decide your value capture model: define whether same‑day is an acquisition channel, a margin‑enhancing product, or a loss‑leader. This choice drives pricing, inventory policy, and whether to build or partner.
-
Pilot fast, scale selectively: run 12‑week pilots that couple store‑based fulfilment with dynamic pricing experiments; use our cost‑to‑serve tool to set success thresholds before committing capex.
-
Design for regulatory resilience: model wage and certification shocks into your unit economics and prefer contractual flex (e.g., variable pay components, scalable contractor pools) where feasible.
-
Leverage hybrid capacity: convert select rural or underutilized facilities into hybrid hubs to broaden same‑day reach without a full greenfield build.
-
Monetize service tiers: introduce transparent service tiers (free/standard, paid accelerated, premium guaranteed windows) and A/B test to identify optimal price elasticity.
-
Operationalize data flows: invest in last‑mile orchestration, real‑time capacity signals, and predictive ETA engines to compress failed delivery rates and reduce re‑delivers — the largest hidden cost center in same‑day operations.
How to read the signals — a short checklist for 2026 investment decisions
-
Is your current service level delivering a measurable revenue premium (AOV lift or conversion)? If not, recalibrate pricing or target product lines where immediacy truly matters.
-
Can you run with a partner to test customer acceptance without capex? If yes, run a controlled cohort test to establish baseline economics.
-
Have you stress‑tested your model against a wage‑upside and regulatory compliance costs? Use scenario outputs to set go/no‑go investment gates.
-
Do you have an exit or scale trigger? Establish measurable KPIs (cost per order, attach rate, margin contribution) that automatically trigger scale‑up or wind‑down.
Why PW Consulting’s preview — and what we intentionally withhold
This preview is designed to communicate the strategic contours and practical implications of a rapidly expanding same‑day market so executives can begin to prioritize 2026 decisions. Consistent with our “preview” approach, we deliberately omit the granular split tables and proprietary segment breakouts (regional percentages, per‑channel revenue slices, and detailed vendor share snapshots) from this public summary. Those detailed segmentations and our interactive financial models are available in the full report and the report portal, where clients can access downloadable tools and run customized scenarios against their internal assumptions.
Next steps
-
For immediate decision support in 2026, request PW Consulting’s executive briefing and the interactive cost‑to‑serve model. These resources will allow your team to run the exact scenarios your CFO needs for Budget 2026 and to set pragmatic pilot targets for H1 2026.
-
If you are evaluating build vs. partner options, schedule a workshop with our network design and vendor selection specialists to translate market signals into a 12‑24 month implementation roadmap.
Same‑day delivery is no longer an experiment — it is an axis along which market share, customer lifetime value, and operational excellence will be contested in 2026. PW Consulting’s full study provides the empirical foundation and the executable tools to ensure that your organization’s investments are timed, sized, and structured to win. For complete segment analyses, vendor share tables, and our downloadable scenario models, please visit the full report page or contact your PW Consulting representative.
For detailed analysis of this topic, please visit the official page: Same-day Delivery Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Mancozeb Market — USD 1,675M in 2025; 4.55% CAGR to 2032
By pmarketresearch, 2026-07-13
Mancozeb Market — Strategic Preview for 2026 Decision-Making
Executive snapshot
As companies set budgets, procurement strategies and portfolio priorities for 2026, the global mancozeb market is entering a phase in which regulatory friction, concentrated supplier power and steady demand growth will jointly shape commercial outcomes. Our PW Consulting study (base year 2025) synthesizes a seven-year forecast horizon (2026–2032) and a five‑year historical window (2020–2025) to give leadership teams the scenario intelligence required to act with conviction. Key macro facts that frame the thinking in this preview: the market is measured in USD Million, registered a recovery and growth trajectory through 2020–2025, and our modeled compound annual growth rate for the forecast window is 4.55%.
Mancozeb Market
Market trajectory: what the topline shows
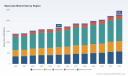
Using consistent USD-million accounting, the market size expanded from the low‑1,400s in 2020 to about 1,675 in 2025 (base year) and is projected to reach roughly 2,287 by 2032 under the central case. The 4.55% CAGR that underpins our forecast reflects a balance of persistent crop protection demand, substitution dynamics where regulatory constraints bite, and episodic supply dislocations that create short-term price volatility.
Mancozeb Market
- Recovery and resilience: Historical volumes and values show the market regained momentum after global agricultural disruptions in the early 2020s, stabilising into a mid-single-digit growth profile by 2025.
- Durable demand drivers: Mancozeb continues to be embedded in disease‑management programs for high‑value crops, which underpins baseline demand even where use is restricted by regulation.
- Price and supply sensitivity: Periodic supply tightness—driven by feedstock availability and regulatory-driven export flows—creates asymmetric price responses that favor nimble producers and well‑positioned buyers.
Competitive landscape and implications
The market exhibits moderate concentration: the top three players account for a meaningful but not dominant share, and the top five push the concentration higher. This structure influences negotiation dynamics, margin capture and the pace of consolidation.
Mancozeb Market
- Concentration metrics: CR3 and CR5 measures indicate a market where leading manufacturers exert pricing and distribution influence, but meaningful room remains for regional specialists and challenger players.
- Strategic moves to watch: Recent deal flow and tactical pricing actions have already altered the competitive map. One major player completed a notable acquisition of a solo mancozeb business in 2024, consolidating a legacy brand and access to proprietary formulation technologies. That same player executed a targeted price adjustment in 2025 in response to tighter supply and demand realignment, illustrating how ownership moves and commercial policy quickly translate to market pricing.
- Profiles at a glance: Legacy formulators and technical-grade producers span established multinationals and regional champions. Competitive positioning now hinges on brand portfolios, formulation IP, downstream channel reach and the ability to manage regulatory exposure across jurisdictions.
Regulatory and trade risk — a core strategic variable
Regulatory dynamics are the single largest non‑demand variable in our scenarios. Mancozeb has been the subject of enduring regulatory scrutiny: it was banned for use in certain markets in 2020 due to reproductive toxicity designations, even while production and export activity continue to be notified and tracked. Parallel registration reviews and risk mitigations in other major jurisdictions add layers of complexity that alter both legal market access and reputational calculus for corporates.
- Dual reality of bans vs. exports: In some regulatory regimes, domestic use is prohibited but production and exports continue under notified frameworks. That dichotomy creates cross‑border arbitrage opportunities and compliance obligations for producers and trading houses.
- Ongoing reviews: Classification as a toxicant for reproduction and as an endocrine disruptor has prompted registration and mitigation discussions in certain major markets, potentially tightening use-patterns or requiring label and application restrictions.
- Operational consequence: Companies must overlay regulatory timelines on supply contracts, insurance exposures and customer segmentation to avoid stranded inventory, compliance breaches or reputational damage.
Practical implications for 2026 corporate strategy
For executive teams deciding where to allocate R&D, capex, procurement and commercial investment in 2026, the PW Consulting view delivers three practical priorities:
- Hedge for regulatory and supply volatility: Negotiate flexible supply contracts that incorporate regulatory‑event triggers, and maintain dual‑sourced supplier relationships for critical technical grades. Tactical inventory buffers calibrated by probabilistic regulatory scenarios are more cost‑efficient than one‑size safety stock policies.
- Reassess go‑to‑market segmentation: Differentiate customer segments by regulatory exposure and willingness to pay for compliant, branded formulations versus commoditized technical supply. That segmentation guides sales compensation, distribution investments and account management intensity.
- Make M&A and partnership decisions with a regulatory overlay: Acquisition targets should be evaluated not only on their volumes or geographic footprints, but also on the regulatory risk embedded in their end‑market exposure and product registrations. Technology or formulation assets that reduce application rates or improve environmental profiles increase optionality.
Competitive scenarios and likely market moves
We model three plausible competitive scenarios for 2026–2030, each with distinct strategic implications for market participants:
- Consolidation with premiumization: Continued M&A among established producers and brand owners results in higher price discipline and premiumization of differentiated formulations. Winners invest in supply chain control and secure feedstock agreements.
- Regulatory fragmentation: Increasing disparity in national regulations forces a bifurcated market—commoditized technical exports flow through tolerant trade channels while constrained domestic markets favor alternative chemistries and integrated pest management solutions.
- Innovation‑led substitution: Accelerated adoption of alternative active ingredients and non‑chemical controls reduces long‑term volumes for legacy fungicides, but creates niches for value‑added formulations and digital agronomy services around disease forecasting and optimized application.
What PW Consulting’s full report equips you to do
The full Mancozeb Market research report is designed as an operational playbook for commercial and corporate strategy teams. It goes beyond narrative to supply analytical tools you can deploy immediately:
- Market sizing and scenario engine: Granular forecast models (to 2032) with demand drivers, elasticity assumptions and alternative regulatory scenarios — model-ready for internal stress testing.
- Supply chain and supplier maps: Verified manufacturer, toll-producer and distribution footprints with capacity overlays and points of single-source risk.
- Pricing and cost models: TPM for raw materials, landed cost calculators, and price‑sensitivity matrices that integrate recent benchmark actions and probable near‑term moves.
- Regulatory exposure grid: Jurisdictional timeline, export‑notification exposure, and compliance impact scoring to prioritize markets and customer types.
- Commercial playbooks: Channel prioritization, value proposition frames for branded vs. generic offerings, and segmented go‑to‑market approaches by customer risk profile.
- M&A and partnership frameworks: Due‑diligence checklists tailored to mancozeb assets, valuation adjustments for regulatory risk, and integration checklists for acquired formulation IP.
How to use the report in your 2026 planning cycle
Leaders should integrate our findings into three planning horizons:
- Short term (0–12 months): Implement purchasing flex clauses, reprice key accounts using the provided price elasticity tools, and prioritise inventory located in low‑regulatory‑risk corridors.
- Medium term (12–36 months): Rebalance product portfolios toward compliant formulations and invest in registration strategies or formulation innovations that lengthen the product lifecycle in higher‑value markets.
- Long term (36+ months): Reassess capital allocation to favour firms and assets that reduce dependence on a single active ingredient through diversification, service layers, or acquisition of complementary technologies.
Final note — the “trailer” approach
The analysis above is intended to demonstrate the depth and practical orientation of PW Consulting’s work: rigorous macro sizing, scenario-enabled forecasts, and direct playbooks for procurement, commercial and M&A decision-makers. To preserve the commercial utility of the full intelligence set and encourage evidence‑based action, we have intentionally summarized directional findings here while reserving detailed segmentation datasets, country‑level exposure tables and the full scenario engine for the complete report.
For executives preparing 2026 budgets and strategic roadmaps, this is the moment to convert awareness into actionable positioning. Access the full Mancozeb Market report for the detailed tables, downloadable models and step‑by‑step implementation guides that will let your team operationalize the scenarios and capture advantage where it emerges.
For detailed analysis of this topic, please visit the official page: Mancozeb Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Solid Phase Extraction (SPE) Consumables: 2026 Strategic Briefing for Decision-Makers
As labs, regulators and industrial users recalibrate priorities around environmental monitoring, biopharma analytics and high‑throughput sample preparation, the SPE consumables landscape is shifting from commodity purchasing toward strategic product selection and supplier positioning. PW Consulting’s market study — anchored on a 2025 base year and covering the 2020–2025 historical window with a 2026–2032 forecast horizon — quantifies that transition and translates it into practical decisions for 2026. In short: the market is growing at a steady mid-single-digit compound annual growth rate (5.1% CAGR across our forecast window), rising from a firmly established 2025 base toward materially larger market opportunity by 2032. This briefing highlights the strategic value of that intelligence while deliberately reserving the granular segmentation tables for the full report.
Solid Phase Extraction (SPE) Consumables (Solid Phase Extraction SPE Consumables) Market
Why this research matters to executives in 2026
- CapEx and capacity planning: Procurement teams and plant managers must align inventory, contract terms and local production capacity to a market that is expanding predictably but unevenly by application and geography. Our scenario modeling supports near-term capacity allocation choices without heavy sleeplessness about volatility.
- R&D and product roadmaps: Technical leaders need to decide whether to prioritize PFAS‑targeted chemistries, oligonucleotide‑specialized kits, automation‑friendly formats, or low‑leach plastics. The report maps where innovation premium is being captured and where features have become table stakes.
- Go‑to‑market and commercial strategy: Sales and marketing teams gain a prioritized set of end‑user segments, procurement triggers and buyer personas to shape pricing, bundling and channel incentives for 2026 wins.
- M&A and partnership screening: Corporate development groups can use the study’s concentration metrics and capability maps to identify consolidation targets, distribution targets and technology partners that accelerate access to regulatory workflows or automation ecosystems.
High‑level market dynamics shaping 2026 choices
Three converging forces underpin the SPE consumables market today: regulation‑driven demand, analytics complexity, and automation/throughput economics.
Solid Phase Extraction (SPE) Consumables (Solid Phase Extraction SPE Consumables) Market
- Regulatory acceleration: Tightening regulatory regimes for PFAS and enhanced standards for environmental and food safety testing are driving procurement of specialized SPE formats and validated workflows. Compliance now imposes product design constraints (e.g., inert, non‑leaching materials and specific sorbent chemistries) that favor suppliers with validated method kits and robust documentation.
- Analytical complexity and niche chemistry: Growing volumes of oligonucleotide therapeutics, coupled with complex environmental matrices, create demand for application‑specific SPE solutions (hybrid sorbents, mixed‑mode cartridges, dual‑bed formats). These requirements raise switching costs for end users and create pockets of margin for differentiated products.
- Automation and throughput: High‑throughput laboratories are migrating to plate‑based and automated SPE systems. Suppliers that offer platform compatibility, validated protocols and integrated consumables are increasingly preferred by contract labs and large pharma customers.
Market structure is meaningful: a concentrated competitive set controls a majority of revenues, giving leading suppliers pricing power and distribution leverage. This is a market where the top three and top five suppliers command a dominant share of sold volumes and influence standards and purchasing norms—an important input to any M&A, sourcing or competitive defense plan.
Solid Phase Extraction (SPE) Consumables (Solid Phase Extraction SPE Consumables) Market
Competitive landscape — what incumbents are doing
We profile the leading SPE consumable vendors and interpret their strategic moves so you can anticipate how competitive dynamics will evolve through 2026.
- Phenomenex — Positioned around high‑value bioanalysis. Recent launches signal a focus on oligonucleotide workflows and consistent recovery kits that reduce method development time for bioanalytical labs.
- Agilent Technologies — Leveraging broad instrument and consumables portfolios to bundle EPA‑compliant PFAS cartridges and validated workflows for regulated testing. Expect continued emphasis on method alignment and enterprise contracts.
- Waters Corporation — Strong in high‑throughput sample prep with branded cartridges and plate formats; the company’s focus is on workflow efficiency and instrument‑consumable integration for large lab footprints.
- Restek — Tactical innovator in PFAS handling, offering dual‑bed cartridges that simplify EPA‑compliant preparation in complex matrices—an example of product innovation reducing user complexity.
- GL Sciences — Moving into automated systems and PFAS‑validated offerings; automation introduces a higher lifetime value per customer and stickier relationships.
- S*Pure — Regional and niche player with a product range that supports lower‑cost supply alternatives and aftermarket manifolds; attractive for procurement diversification.
- Biotage — Focused on disks and columns with emphasis on purification workflows; strategic strength lies in specialty applications and purity‑sensitive markets.
- Merck KGaA — Offers an extensive consumables and sorbent portfolio; global reach and regulatory documentation make it a go‑to for multinational labs.
The past 18 months have included targeted product introductions — next‑generation oligo kits, PFAS dual‑bed cartridges, and automated water‑sample systems — that are not random product launches but tactical responses to regulatory requirements and throughput demands. Expect continued feature competition rather than pure price wars in the near term.
What PW Consulting’s full report delivers (practical, operational content)
This study is designed not as a marketing brochure but as a working toolkit for executives and functional leaders. Among the deliverables and tools included:
- Bottom‑up market sizing and a multi‑scenario forecast (base, upside, downside) across the 2026–2032 horizon, with sensitivity to regulatory shock events;
- Regulatory and standards mapping that ties specific methods (PFAS and others) to consumable product requirements and supplier qualification checklists;
- Supplier scorecards and a competitive feature matrix that compare product attributes, validation support, automation readiness and channel reach;
- Buyer persona models and procurement trigger maps for CROs, environmental labs, food testing labs, and in‑house pharma QC groups;
- Pricing benchmark ranges and margin‑pressure scenarios to support commercial negotiations;
- Supply‑chain resilience playbook and raw‑material exposure heatmap with suggested mitigation actions; and
- Excel‑based financial model and M&A screening tool that allows you to test inorganic scenarios against market concentration and growth vectors.
These components are configured to enable immediate decision use — from negotiating supplier contracts in Q1 2026 to selecting technology targets for a bolt‑on acquisition.
Recommended strategic moves for 2026
- Prioritize validated PFAS and oligonucleotide product releases: If you are a manufacturer, accelerate development and regulatory validation of kits and cartridges that match prevailing methods; buyers should pre‑qualify suppliers that demonstrate method compliance and supply continuity.
- Invest in automation compatibility: Design consumables and packaging with robotic and plate‑based workflows in mind. Platform compatibility drives higher switching costs and recurring revenue.
- Diversify supply base while deepening strategic partnerships: Mitigate single‑source risk by qualifying secondary suppliers in 2026, but pursue strategic partnerships with instrument OEMs to create integrated workflow offerings.
- Use concentration to inform M&A or defense: The leading suppliers enjoy structural advantages—buyers or mid‑tier suppliers should evaluate bolt‑on M&A to access validated chemistries or distribution networks.
- Embed regulatory support in commercial offers: Offer customers validation packs, method transfer support and documentation aligned to EPA and ISO standards as part of a premium service bundle.
How to apply this intelligence in Q1–Q4 2026
Start by exporting the report’s scenario model and supplier scorecards into your procurement and R&D planning cycles. Use the M&A screening tool to shortlist targets for diligence, then run sensitivity tests against the model’s regulatory shock scenarios. For commercial teams, adopt the buyer personas and procurement trigger maps to resegment accounts and reprice bundles for higher attach rates.
PW Consulting’s full study contains the underlying datasets, segmented demand vectors, validated assumptions and downloadable models. We intentionally keep the headline analysis and practical recommendations here while gating the granular segmentation tables and downloadable Excel models to the full deliverable to preserve commercial value and drive informed engagement.
For executives looking to move from insight to action in 2026, this study is both a roadmap and a toolkit: it shows where demand will reliably grow, where product differentiation matters, and which supplier strategies are likely to win. Contact PW Consulting to obtain the full report and the interactive market model to inform your 2026 planning cycle.
For detailed analysis of this topic, please visit the official page: Solid Phase Extraction (SPE) Consumables (Solid Phase Extraction SPE Consumables) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Marble Market Hits USD 23.5B in 2025, Set for 4.61% CAGR — PW Consulting
By pmarketresearch, 2026-07-13
Marble Market 2026: A Strategic Preview for Leaders and Investors
Executive snapshot
The global marble market has moved from a niche commodity into a strategic input for architects, developers, and premium manufacturers. Using 2025 as a base year, our analysis shows the market at approximately USD 23.5 Billion, having experienced steady expansion through 2020–2025 and set to continue growth through the 2026–2032 forecast horizon. Under the baseline outlook the market grows at a compound annual growth rate of roughly 4.61%, reaching an anticipated market size in the early 2030s that is materially larger than today. For 2026 decision-makers this context is not just background: it defines the opportunity window, the timing of capital allocation, and the competitive urgency that should shape strategy-setting in the year ahead.
Marble Market
Why this report matters for 2026 strategic decisions
-
Timing and scale of investment: With predictable, mid-single-digit CAGR dynamics, executives must reconcile longer lead-time investments (quarry development, downstream processing capacity, automation) with cyclical demand. Our research clarifies when incremental capacity is likely to be absorbed and where margin expansion is most attainable.
Marble Market -
Supply-chain risk becomes a differentiator: Raw material extraction and processing costs fluctuated materially in 2025. The companies that succeed in 2026 will be those that translate supply resilience into guaranteed lead times and predictable cost curves—especially for premium architectural projects where time and quality command price.
Marble Market -
Regulatory and trade policy create both headwinds and arbitrage: Recent tariff reclassifications and evolving construction product standards mean sourcing strategies must be re-evaluated now. Our analysis highlights where compliance overhead and duty exposure move the break-even of import vs. local sourcing decisions.
-
Product and service differentiation is intensifying: Premium finishes, custom installations, and integrated offering bundles (stone + installation + digital visualization) are driving higher per-project value. Companies that reconfigure sales, marketing, and manufacturing to capture these segments will see outsized returns.
-
Consolidation and competitive positioning: Market concentration is meaningful but incomplete—the top-tier players capture a material share but leave room for focused challengers. The next 18 months will be decisive for M&A and strategic partnerships.
What the full study delivers (operationally actionable content)
-
Robust market sizing and trend models anchored to 2020–2025 historicals and a 2026–2032 forecast framework (methodology, assumptions, and sensitivity ranges included).
-
Tariff and regulatory impact matrices: scenario-driven estimates of duty changes, classification risk, and compliance cost for cross-border flows—built for finance and legal teams to model near-term P&L impacts.
-
Supplier and quarry scorecards: operational KPIs, quality profiles, throughput constraints and upgrade pathways (presented in an anonymized benchmarking format suited for procurement negotiations).
-
Route-to-market playbooks by product archetype: premium architectural, mid-market surfacing, and engineered/synthetic alternatives—covering go-to-market tactics, recommended commercial terms, and digital sales enablement.
-
Capex prioritization and ROI calculators that embed extraction costs, processing automation, and logistics scenarios so owners can compare brownfield upgrades versus greenfield options.
-
Risk and opportunity heatmaps: raw-material price stress tests, supply interruption mapping, and demand-shock scenarios with operational mitigations and contingency checklists.
-
M&A readiness and integration checklist for acquirers and targets: valuation heuristics, cultural integration flags, and quick-win synergies for bolt-on quarry or downstream processing acquisitions.
Competitive landscape — who matters and why
The competitive field combines long-established quarry owners, vertically integrated processors, and regional specialists. Several firms consistently surface as strategic reference points for buyers, specifiers, and acquirers:
-
Levantina y Asociados de Minerales, S.A. (Alicante, Spain) — renowned for quarrying and large-format slab collections and for recent creative product launches aimed at high-impact installations.
-
Antolini Luigi & C. S.p.A. (Italy) — a premium processor with a strong position in architectural and decorative stone, often driving trends in surface design and finishing techniques.
-
Polycor Inc. (Quebec, Canada) — vertically integrated through quarrying and distribution, with a reputation in façade and monumental stone applications.
-
Mid-sized and regional specialists (including several European and Mediterranean quarry operators) — these players are critical to niche supply, high-quality blocks, and flexible processing for bespoke projects.
Recent product and marketing moves—such as major collection launches and trade-show debuts—underscore a shift toward experiential marketing and higher-margin finished products. Our competitive chapter includes strategic positioning maps, capability matrices, and acquisition targets by strategic intent (scale, premium access, or regional fill-in).
Market dynamics to watch into 2026
-
Raw materials and processing costs: 2025 saw notable volatility driven by extraction and energy costs. Buyers and processors must rebuild cost models with forward curves; our report provides scenario-based unit-cost decks and break-even thresholds for pricing strategies.
-
Trade policy and classification updates: Recent revisions to tariff classifications affect landed costs for slab imports. Procurement teams should incorporate these policy shifts into sourcing decisions and contractual terms to avoid margin erosion.
-
Standards and compliance in construction markets: Evolving product marking and performance declarations in major construction markets increase the administrative and testing burden for exporters. The study maps the compliance steps and likely timelines for adoption.
-
Geopolitical sourcing shifts: Tariff policies and supply-chain geopolitics in major markets continue to re-route flows and create short-term opportunities for locally positioned suppliers or those with multi-origin sourcing strategies.
Strategic playbook for 2026 (prioritized actions)
-
Short-term (next 6–12 months): Stabilize supply through multi-sourcing contracts, institute tariff pass-through clauses where possible, and pilot digital sales tools (visualizers, AR) to accelerate specification conversion in high-value projects.
-
Medium-term (12–36 months): Invest selectively in finishing automation and value-added services (edge work, bespoke cutting, integrated installation services) to capture margin from premium segments. Consider targeted tuck-ins to secure feedstock or specialized processing capability.
-
Long-term (36+ months): Reassess geographic footprint with an eye to resilience and duty optimization. Build sustainability narratives tied to measurable extraction and processing improvements—these will be increasingly decisive in public and institutional projects.
Scenario thinking — three plausible 2026 environments
-
Baseline: Continued steady growth consistent with the multi-year trend and our central forecast; tactical supply and compliance moves protect margins and allow incremental share gains.
-
Downside: Trade frictions or a regional construction slowdown compress demand and lengthen inventory cycles; the response should prioritize cash preservation, flexible sourcing, and conversion of high-cost fixed assets.
-
Upside: Strong premium-building demand and rapid adoption of integrated surface solutions accelerate growth; winners will be those that scale premium collections and secure high-quality feedstock.
How to use this preview
This introduction is designed to give C-suite leaders, corporate development teams, procurement heads, and private equity sponsors a clear sense of what is at stake for 2026. It demonstrates the strategic levers—sourcing, compliance, product, and M&A—that will decide winners. If you are preparing budgets, revising sourcing policies, evaluating acquisition targets, or designing product roadmaps for 2026, the full Marble Market study provides the granular, transaction-ready data and tools to operationalize these strategic choices.
Next steps
If you need scenario-tailored modeling (customized to your cost base or footprint), supplier diligence templates, or a go-to-market playbook adapted to your product mix, PW Consulting can deliver a bespoke engagement. Our full report contains the detailed segmentation, regional and application breakdowns, supplier scorecards, and tariff-by-route analyses that underpin the strategic recommendations summarized here—accessing that material is the most efficient way to convert insight into 2026 action.
For detailed analysis of this topic, please visit the official page: Marble Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Winter Tire Market 2026 — Strategic Imperatives for Leaders
As the global automotive ecosystem recalibrates for a decarbonizing, digitizing, and regulation-intense decade, winter tires have emerged as a strategic axis for original equipment manufacturers (OEMs), aftermarket distributors, fleet operators, and investors. PW Consulting’s Winter Tire Market study (base year 2025; forecast period 2026–2032) synthesizes five years of historical dynamics (2020–2025) and projects the market trajectory under alternative scenarios. The headline: the market has grown steadily from an estimated USD 163.15 Million in 2020 to USD 215.0 Million in 2025 and is projected to reach approximately USD 322.43 Million by 2032 at a compound annual growth rate (CAGR) of 5.96% (all values in USD Million). This briefing highlights the strategic value of that analysis for corporate decision-making in 2026 while deliberately reserving the granular segment tables and proprietary assumptions for subscribers to the full report.
Winter Tire Market
Why this study matters for 2026 decisions
-
Macro momentum creates optionality — but not uniform opportunity. A sub-6% CAGR combined with structural tailwinds (stricter winter tyre regulations in multiple markets, electrification, and growing consumer safety consciousness) creates a predictable growth corridor for disciplined players. Strategic decisions made in 2026 — product investment, capacity reallocation, and channel expansion — will materially affect market share trajectories through 2032.
Winter Tire Market -
Concentration and competitive pressure are real. The market exhibits moderate concentration (CR3 ≈ 47.6%; CR5 ≈ 61.2%), meaning the leading producers retain meaningful pricing power and distribution pull. New entrants must plan for differentiated value propositions or niche specialization, while incumbents need to defend margins against commoditization and raw-material volatility.
Winter Tire Market -
Regulatory change accelerates demand and raises compliance costs. Recent and near-term rules across Europe and North America — from Alpine snowflake certification mandates to seasonal requirements in Québec and targeted heavy-vehicle obligations in the Nordics — convert regulatory compliance into a product development and go-to-market priority for 2026.
-
Supply-side risk is elevated. Primary inputs — natural and synthetic rubber, carbon black, and steel — remain exposed to commodity cycles and logistics disruptions. Procurement and inventory strategies implemented in 2026 will be a major determinant of 2027–2029 margin performance.
What the full report delivers (practical, executable content)
-
Forward-looking market model (2026–2032) with scenario runs: baseline, constrained-supply, regulation-driven upside, and EV-penetration acceleration. Each scenario includes demand drivers, sensitivity to winter-season severity, and channel mix implications.
-
Go-to-market playbooks for OEM partnerships, aftermarket retail networks, and fleet channels — including pricing levers, promotion timing, and seasonal inventory strategies.
-
Supply-chain risk matrix and procurement playbook: hedging strategies, alternative-sourcing options, and a capex-phased approach for flexible manufacturing capacity.
-
Regulatory compliance and certification roadmap, tying regional legal changes to product development timelines and testing milestones (3PMSF and equivalent qualifications).
-
Competitive benchmark and capability-gap analysis of leading suppliers, with strategic options (defend, differentiate, divest) mapped against profitability and market-share trade-offs.
-
M&A and partnership screening framework tuned to achieve scale in critical geographies, secure proprietary low-temperature compound expertise, or add digital capabilities (sales platforms, subscription services).
-
A set of board-ready investment cases and decision trees to stress-test capital allocation between R&D (compound chemistry, stud technology), manufacturing capacity, and acquisition premium thresholds.
Competitive landscape — what to watch in 2026
Leading firms continue to invest in technology differentiation, certification, and brand-led positioning. Several dynamics will reshape competitive advantage during 2026:
-
Product innovation is bifurcating into high-performance, low-rolling-resistance solutions for electrified vehicles and intelligent stud technologies for extreme climates. Examples include Bridgestone’s January 2026 launch of Blizzak IcePeak — positioned as a flagship winter compound leveraging ENLITEN™ technology — and Nokian Tyres’ March 2026 rollout of the Hakkapeliitta 01 range featuring On-Demand Grip stud technology. These product moves underline two tactical imperatives: accelerate certification and align commercialization timing to seasonal buying cycles.
-
Incumbent brand strength remains a moat, particularly in markets where channel relationships and fleet contracts determine volumetric flows. However, premiumization creates room for differentiated margin capture if tied to demonstrable EV performance or validated safety metrics.
-
Cross-company snapshot: Michelin and Continental sustain premium, engineering-led portfolios; Bridgestone and Goodyear balance OE and aftermarket scale; Nokian continues to lead in extreme-cold innovation; Pirelli leverages performance and luxury positioning. Each plays a different strategic game — from certification-first to brand-led margin extraction.
Regulatory and raw-material dynamics shaping 2026 strategies
-
Regulation is now a demand driver. A wave of policy actions — mandatory winter-tire windows, stricter marking requirements (Alpine snowflake/3PMSF), and targeted heavy-vehicle obligations — are shortening certification lead times and amplifying the commercial importance of compliant SKUs.
-
Commodity exposure demands proactive procurement. Natural rubber, synthetic rubber, carbon black, and steel remain primary input risks. Strategic responses include long-term off-take agreements, localized compounding centers to reduce freight exposure, and selective inventory buffering aligned with seasonality curves.
-
Circularity can be a two-fold opportunity: cost mitigation through reclaimed rubber and a premium brand narrative in regulated markets with strict tyre disposal rules. Embedding a recycling/retreading pipeline into 2026 plans reduces feedstock dependency and supports sustainability claims that resonate with both regulators and fleet customers.
2026 Strategic Playbook — actions that separate winners from laggards
-
Fast-track certifications that map to hard regulatory dates. Ensure new SKUs meet 3PMSF and regional winter mandates before the autumn buying window; missed certifications result in lost shelf and fleet opportunities that are hard to recover within a season.
-
Prioritize EV-specific winter compounds and constructions. Low rolling resistance, thermal management, and load capacity for heavier EVs must be core to R&D roadmaps — not an afterthought.
-
Implement a two-tier procurement hedge: medium-term off-takes for key elastomers and flexible short-term exposure for additives. Combine supplier partnerships with strategic stockpiles timed to pre-season build-up.
-
Adopt modular manufacturing footprints. Invest selectively in flexible lines capable of switching between studded and studless constructions, and consider nearshoring to high-demand winter markets to reduce lead times and logistics carbon footprint.
-
Monetize services: subscription models, mobile fitting, and predictive replacement alerts for fleets create recurring revenue streams and higher lifetime value while smoothing seasonality.
-
Use M&A selectively to buy capabilities rather than volume: acquiring compounding expertise, testing facilities, or digital retail platforms can accelerate time-to-market and defend margin profiles.
For investment committees and executive teams
Decision-makers must reconcile the moderate-but-steady market growth profile (CAGR ~5.96% over 2026–2032) with asymmetric risks on raw-materials, regulation, and product obsolescence in the EV era. Capital allocation should be prioritized to:
-
Protect market access through certification and channel commitments ahead of regulatory deadlines.
-
Defend margins via procurement sophistication and selective vertical integration in compounding and recycling.
-
Capture premium segments by aligning R&D to EV-specific performance metrics and seasonal reliability claims.
Conclusion — the next 12 months matter
The winter tire market in 2026 sits at the intersection of steady demand growth and rapidly shifting competitive, regulatory, and input-cost dynamics. Firms that move early on certification, supply resilience, EV product fit, and service-led monetization will secure disproportionate returns as the market advances toward the projected USD 322.43 Million horizon by 2032.
PW Consulting’s full Winter Tire Market report contains the detailed regional and application breakdowns, channel economics, scenario model files, and investable M&A target lists referenced above. To access the complete analysis, proprietary segment tables, and the decision-support tools that underpin these recommendations, visit our report page.
For detailed analysis of this topic, please visit the official page: Winter Tire Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Aquaponics Market: Strategic Intelligence for 2026 Decision‑Makers
As companies plan capital allocation and strategic pivots for 2026, aquaponics is shifting from an experimental niche to a commercially viable node within controlled‑environment agriculture. PW Consulting’s latest Aquaponics Market study — anchored on 2025 as the base year and projecting through 2032 — quantifies a clear growth trajectory: the global market expanded from roughly USD 95.2 million in 2020 to about USD 142.5 million in 2025, and our models place it on a near‑double path to approximately USD 272.7 million by 2032. That expansion is underpinned by a compounded annual growth rate of 9.87% over the forecast interval, a pace that creates definable windows for capex deployment, vertical integration, and technology partnerships.
Aquaponics Market
Why this research matters for decisions you will make in 2026
-
Timing capital expenditure: With a predictable growth profile and accelerating commercial deployments, the report identifies where early movers can capture margin before commoditization pressures increase.
Aquaponics Market -
Choosing go‑to‑market models: Whether you are a technology supplier, integrator, or produce distributor, the research isolates business models that scale profitably versus pilots that stall.
Aquaponics Market -
Risk calibration for financing: Lenders and corporate development teams need quantified scenarios for revenue ramp and payback timing; our forecast scenarios provide those templates tied to operational KPIs.
-
Regulatory and compliance playbook: Rapid changes in urban food policy and licencing are reshaping site feasibility. The study translates these dynamics into practical checklist items for market entry.
Signal synthesis: the data‑driven themes that will determine winners
-
Commercialisation is accelerating. The market’s near‑double growth from 2025 to 2032 is not just a headline — it reflects increasing farm scale, institutional capital, and adoption of professional service models (design, construction, O&M).
-
Technology is a margin lever. Automation and robotics integration have already demonstrably improved operations — reducing fish mortality events by about 35% and improving feed‑conversion ratios by roughly 12–15% in documented commercial deployments. Firms that embed automation and closed‑loop monitoring see faster path to profitability.
-
Component commoditization is enabling low‑cost smart systems. The adoption of inexpensive microcontrollers and food‑grade control materials is lowering entry barriers for modular product lines, expanding the addressable market at lower ticket sizes and enabling education and home segments to scale.
-
Policy and institutional endorsement matters. Urban food security initiatives and licensing frameworks are making aquaponics projects bankable in select jurisdictions — a trend highlighted by recent approvals under high‑profile urban food programs. These policy signals are prime inputs when prioritising pilot locations.
-
Market structure: fragmented but consolidating. Industry concentration metrics indicate a market that remains fragmented, with distinct opportunities for the leading integrators to scale through strategic M&A, channel partnerships, and standardisation of service offerings.
What’s inside the PW Consulting Aquaponics Market study (practical deliverables)
-
Market sizing and scenario forecasts (base 2025, forecast 2026–2032) with bottom‑up and top‑down validation frameworks suitable for investor diligence.
-
Commercial playbooks that translate market math into executable pilot‑to‑scale roadmaps: capex budgeting templates, O&M cost buckets, labour models and revenue sensitivity calculators.
-
Technology adoption map: comparative assessment of system architectures, automation modules, sensor stacks and supplier ecosystems, plus guidance on interoperability and retrofit strategies.
-
Regulatory and permitting checklist tailored to urban and peri‑urban deployments, synthesising global licensing precedents and compliance milestones.
-
Customer segmentation and value‑proposition matrices for verticals (commercial produce, education, small‑scale household systems and research deployments) — designed to inform pricing and channel strategies without exposing proprietary segment-level figures in this overview.
-
Operational case studies and CAPEX/OPEX anonymised models from commercial deployments that illustrate realistic payback curves under different yield and pricing scenarios.
-
Supplier and partner directory with capability profiles to accelerate procurement and vendor selection.
Competitive landscape — how to read provider strengths in 2026
The aquaponics value chain is populated by a mix of specialised system designers, component suppliers, turnkey builders and farm operators. Our competitive analysis highlights firms across those roles and synthesises strategic positioning you can act on:
-
Nelson and Pade, Inc.: Strength in packaged system design and education services, with offerings that prioritise turnkey clarity and operator training for small to mid‑scale integrations.
-
Pentair Aquatic Eco‑Systems, Inc.: A component and systems supplier focused on the biofiltration, aeration and mechanical systems that scale to large recirculating aquaculture and commercial aquaponics projects.
-
The Aquaponic Source: Modular system manufacturer and education provider with strong channel reach for community, school and entry‑level commercial customers.
-
ECF Farmsystems GmbH: European turnkey integrator that brings farm design, construction and operational know‑how for commercial sustainable produce producers.
-
Greenscale: Example of an operator‑led model operating integrated indoor facilities; recent facility launches demonstrate near‑term scalability pathways for vertically integrated producers.
-
Gothic Arch Greenhouses: Platform and greenhouse specialist enabling year‑round integration of aquaponics and hydroponics at the structure level.
-
Back to the Roots & AquaSprouts: Focused on education and consumer markets with plug‑and‑play kits that expand public awareness and create grassroots demand.
Recent industry developments underscore these shifts: high‑profile conference workshops are elevating aquaponics as a sustainability and regulatory compliance tool for controlled environment agriculture; commercial operators are expanding capacity and adding integrated leafy greens lines; and indoor farm launches highlight the viability of tilapia‑plus‑greens models. Collectively, these signs point to increasing institutionalisation of the sector.
Strategic moves to prioritise in 2026 (executive checklist)
-
Invest selectively in automation that links sensor data to feed, oxygenation and water quality controls — performance improvements here materially alter margin profiles.
-
Adopt a modular pilot‑to‑scale approach: validate operating recipes and local licensing in one facility, then replicate using standardised prefabricated modules to compress time to scale.
-
Forge supplier partnerships rather than transactional procurement: long‑term service agreements for biofilters, monitoring platforms and spare parts reduce uptime risk and improve financing prospects.
-
Blend product and service revenue streams: training, maintenance subscriptions and farm data analytics create higher lifetime value than equipment alone.
-
Use regulatory wins as leverage: secure local approvals early and use licensed operations to demonstrate food‑safety credentials to retailers and foodservice customers.
-
Track a concise set of KPIs: yield per unit area, feed‑conversion ratio, stocking survival, energy cost per kg produced, and uptime — these tell you whether you have a scalable economic model.
How PW Consulting’s study helps you act now
Our report provides the analytical scaffolding decision‑makers need in 2026: validated market sizing, scenario stress‑tests keyed to regulatory and technology shocks, and execution tools that translate forecast inputs into balance‑sheet outcomes. We deliberately surface the actionable signals — growth drivers, unit economics improvements, and provider capabilities — while preserving the competitive segmentation detail for the full study to support client diligence and competitor benchmarking.
If your team is evaluating expansion, investing in aquaponics technology, preparing an acquisition bid, or designing a pilot‑to‑scale roll‑out, this research gives you the templates and scenario evidence to move from hypothesis to funded plan. For the full dataset, segmented forecasts, and vendor scorecards, the complete report is available through PW Consulting — and our analysts stand ready to build a bespoke diligence package aligned to your strategic priorities.
In an industry where operational know‑how and timely regulatory access matter as much as yield curves, the next 18–24 months will determine who captures the profitable segments of the aquaponics market. Use the evidence, scenario tools and playbooks in this study to make those decisions with confidence.
For detailed analysis of this topic, please visit the official page: Aquaponics Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tahini Market Strategic Brief — Why 2026 Demands a New Playbook
As PW Consulting’s Senior Strategy Advisor and Head Industry Analyst, I present a focused industry introduction to our full Tahini Market research — designed to shape boardroom decisions in 2026. This brief synthesizes the macro trajectory, competitive dynamics, and near-term operational risks that will determine winners and losers over the next planning cycle. It deliberately demonstrates methodological rigor while reserving granular segment and regional datasets for the full report, ensuring decision-makers see both the contours of opportunity and the need to consult the complete intelligence package before committing capital.
Tahini Market
Market at a Glance: Trajectory and Interpretation
Using 2025 as the analytical base, the global tahini market reached USD 150.6 Million and has printed steady historical growth across 2020–2025. Our forecast horizon (2026–2032) is modeled at a compound annual growth rate (CAGR) of 5.38%, projecting the market toward a materially larger addressable pool by the end of the forecast window. These headline metrics reflect a market that is maturing: expanding beyond ethnic and specialty channels into mainstream retail, foodservice, and innovation-led occasions.
Tahini Market
Two implications follow for executive teams planning in 2026. First, the base market size and mid-single-digit CAGR validate continued investment — particularly where brands can convert health, convenience, and flavor trends into repeat purchase. Second, the pace of growth is not uniform across business models: premium, organic, and convenience-oriented offerings are outpacing legacy commodity lines in terms of margin expansion and channel velocity. The full report quantifies these different growth vectors and presents scenario-based P&L impacts; this brief highlights the strategic takeaways.
Tahini Market
Why Growth Is Happening — Demand Drivers
- Dietary trends: plant-based diets and clean-label demand continue to elevate sesame-based ingredients as both nutritional and functional components in consumer formulations.
- Premiumization and format innovation: consumer willingness to pay a premium for single-origin, artisanal, organic, and flavored tahini has enabled brands to command higher shelf prices and margin.
- Retail and channel diversification: growth in e-commerce, private label entry, and foodservice applications (restaurant hummus programs, sauces, dressings) is broadening usage occasions.
- Productization of taste: squeeze formats, flavored lines, and ready-to-use formulations are converting intermittent buyers into frequent users by simplifying application.
Supply-Side Realities and Risk Vectors
Growth is running up against several supply-side constraints. Sesame seed availability and pricing are exposed to adverse weather and geopolitical disruptions in key producer regions, driving raw material cost volatility. These pressures have already translated into price swings and procurement stresses for manufacturers. At the same time, food-safety incidents have materially impacted regulatory posture in certain markets; for example, tahini has been designated a higher-risk food category in some jurisdictions following contamination events, prompting tighter import controls and lab-testing requirements.
Operational leaders should treat these dynamics as permanent features, not episodic blips. The necessary responses include strategic sourcing, hedging and long-term supplier agreements, higher-spec quality assurance processes (including certifications and traceability investments), and an explicit recall and crisis-response playbook embedded in supply contracts and insurance arrangements.
Competitive Structure: Fragmented, But Consolidation-Ready
Market concentration remains modest: the three largest players account for a minority share, and the top five likewise leave ample market represented by regional specialists and artisan brands. This fragmentation creates a dual landscape: established importers and distributors defend scale in mainstream channels, while nimble premium and organic specialists drive product and format innovation.
- Krinos Foods — A long-standing importer and distributor with deep supermarket and ethnic-channel reach. Their strengths are scale distribution and category placement; their playbook is distribution-led expansion into mainstream aisles.
- Soom Foods — A premium, founder- and women-owned brand that has successfully monetized flavor innovation and convenience formats. Recent product launches continue to underscore the commercial payoff of format-led product development.
- Mighty Sesame Co. — Focused on organic, roasted hulled tahini for plant-based and natural channels. Their channel focus and certified claims speak to a growing consumer cohort prioritizing certified organic and functional ingredients.
- Seed + Mill — Artisanal, female-owned player with a strong premium kitchen-staple positioning, capturing foodservice and culinary influencer channels.
- KROTAJ Tahini Manufactures PLC — Represents upstream, origin-focused capacity, exporting quality tahini produced on-ground in producing countries and pursuing certification pathways to access global markets.
Recent developments illustrate both opportunity and risk: a high-profile flavored squeeze launch by an established premium brand accelerated category awareness in 2026, while multiple recalls in the prior two years have tightened regulatory scrutiny and elevated the cost of compliance for all market participants.
What the Full Report Contains — Practical, Executable Intelligence
Our full Tahini Market study is designed to be operational from day one. Highlights include:
- Comprehensive market sizing and seven-year forecasts with scenario modeling (base, upside, and downside) aligned to raw-material price shocks and channel migration.
- Demand-driver matrices segmented by product type, format, and channel — with elasticity profiles to model promo depth and private-label entry impacts.
- Supplier and origin risk assessment, including a ranked supplier scorecard and recommendations for diversified sourcing and contract structures.
- Regulatory and quality playbook: checklist for third-party certifications, testing frequency, and recall-resilience best practices drawn from recent incident post-mortems.
- Competitive heatmaps and M&A target shortlists with valuation heuristics and earn-out frameworks tailored to consolidation candidates.
- Commercial go-to-market toolkits for product launches, pricing ladders, and trade promotional plans designed to accelerate velocity while protecting margins.
- Financial impact templates and KPI dashboards for board reporting and investor diligence.
Note: consistent with the “trailer” principle of this brief, granular regional and application-level splits are intentionally reserved for the full report to ensure readers consult the primary dataset and interactive spreadsheets prior to making allocation decisions.
Strategic Imperatives for 2026
- Invest in upstream resilience. Secure diversified suppliers, evaluate origin hedges, and develop supplier partnerships that include quality incentives and shared risk mechanisms.
- Differentiate through format and flavor. Squeezable formats and flavored tahinis accelerate household penetration; but they require augmented shelf-life testing and SKU rationalization to avoid margin drag.
- Codify food-safety excellence. Build multi-layered QA: batch testing, cold-chain verification where applicable, certification programs, and verifiable traceability to reduce regulatory friction and recall risk.
- Channel choreography. Mix direct-to-consumer premium strategies with scaled private-label and foodservice partnerships to balance margin and velocity. Use e-commerce data to iterate on SKU assortment faster than legacy retail cycles.
- Pursue targeted consolidation. Given current fragmentation and modest top-three concentration, opportunistic M&A for capacity, certification, or channel access is viable — but must be underpinned by rigorous integration plans focused on quality harmonization.
- Operationalize scenario planning. Embed sensitivity to sesame seed pricing into three-year budgets; stress-test gross margin under plausible disruption scenarios and maintain contingency liquidity.
How PW Consulting Can Accelerate Your 2026 Agenda
Our clients use this study to transform uncertainty into actionable plans. We pair the research with bespoke deliverables: a tailored sourcing playbook, an M&A diligence pack, and a go-to-market sprint to commercialize one or two high-impact SKUs within six months. For organizations looking to move from strategy to execution, we offer a workshop that converts the report’s scenarios into board-ready capital and operational plans.
Closing: The Cost of Inaction
The tahini market presents a classic mid-cycle strategic choice in 2026: move early to capture wallet share through innovation and supply resilience, or risk margin erosion and regulatory setbacks as late entrants react to rising costs and tighter import controls. The headline numbers — an established market base in 2025 and a mid-single-digit CAGR over the forecast period — indicate substantive, sustainable opportunity. But those returns will accrue to companies that integrate commercial creativity with disciplined risk management.
For executives ready to convert this intelligence into prioritized actions, the full report contains the segmented datasets, supplier lists, financial models, and playbooks necessary to operationalize strategy. Contact PW Consulting for access to the complete research and to schedule a 90-minute strategic briefing tailored to your organization’s risk profile and growth ambitions.
For detailed analysis of this topic, please visit the official page: Tahini Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Security Door Market to Reach USD 344.8M by 2032 at 6.98% CAGR
By pmarketresearch, 2026-07-13
Security Door Market — 2026 Strategic Primer
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present a focused, practitioner-oriented overview of the Security Door Market designed to inform leadership decisions in 2026. This briefing demonstrates the analytical depth underpinning our full market study while deliberately withholding granular segment-level datapoints — a purposeful “trailer” to prompt access to the primary report for executable intelligence.
Security Door Market
Market at a Glance
Using 2025 as the base year and tracing performance from 2020 through 2025, our model shows a market that has steadily expanded through cycles of demand and supply-side adjustment. The global market grew from the low‑hundreds of USD million in 2020 to a stronger position by the 2025 base year, and our forecast through 2032 projects continued expansion at a compound annual growth rate (CAGR) of approximately 6.98% over the 2026–2032 horizon. By 2032 the market is expected to be materially larger than the 2025 base, underscoring persistent opportunity for suppliers, integrators and institutional purchasers.
Security Door Market
Market concentration remains relatively low: the top three and top five players account for only a modest share of global revenues, indicating a fragmented landscape with room for consolidation and differentiation. That structure changes the calculus for strategic moves — scale benefits are real but accessible through targeted M&A, distribution partnerships and channel-play strategies rather than purely organic national roll-ups.
Security Door Market
Why this study matters for 2026 decisions
- Capital allocation: Investors and corporate development teams can use the topline trajectory and concentration profile to calibrate trophy acquisitions versus bolt-on buys aimed at niche capabilities (e.g., force-resistant systems, integrated access-control hardware).
- Product strategy: Manufacturers and OEMs will face higher returns on R&D investments focused on compliance-led design, modularity and integrated electronics as standards and end-user expectations evolve.
- Procurement and risk: Facilities and property managers will need to re-assess supplier risk and lifecycle costs given intensifying regulatory and testing requirements for locks, hardware and fire/security interfaces.
- Channel playbooks: Distributors and installers can exploit fragmentation by offering bundled services (installation + warranty + remote monitoring) to professionalize the retrofit market.
Key dynamics shaping 2026
- Regulatory tightening: The regulatory environment tightened meaningfully entering 2026. New mandatory testing for locks and hardware (notably recent UL updates) increases the compliance bar for new product introductions. These changes alter certification timelines and raise the cost of entry for niche manufacturers while advantaging suppliers with in-house testing and certification experience.
- Security + safety convergence: Fire safety, access control and data-protection obligations are now jointly shaping product specifications. Solutions that successfully balance forced-entry resistance with fire-rating and electronic access integration will capture disproportionate share of large institutional tenders.
- Product innovation vectors: Expect continued emphasis on force-resistant steel systems, modular door frames for rapid field retrofits, and smart-hardware integration (secure firmware, remote audit trails). Physical robustness remains table stakes; differentiation increasingly comes through system integration and lifecycle services.
- Channel and procurement shifts: New-build demand remains important, but retrofit and HOA/association markets are growing faster in some regions. Value is migrating toward providers who can offer turn-key solutions and warranty-backed installation networks.
- Events and market signaling: Industry shows and product collaborations throughout 2025–mid‑2026 have accelerated brand visibility and buyer education — an important lead indicator for adoption cycles.
Competitive landscape — what matters to 2026 strategic plans
The market includes a mix of specialist fabricators, regional manufacturers and companies focused on niche verticals (detention facilities, HOAs, residential bespoke doors). Below is a synthesized view of representative players and the strategic implications they reveal.
- Latham's Steel Doors (UK) — A specialist in high‑security steel residential and commercial doors, increasingly visible through product collaborations and event marketing. Their recent public demonstrations of a celebrity‑endorsed, high-profile product highlight how branding and experiential marketing can accelerate premium segment demand. Strategic take: high-margin differentiation via performance marketing and demonstration-led sales.
- Secure House (UK) — In-house manufacture of bespoke high-security doors and associated products positions them to control quality and certification pathways. Strategic take: vertical integration supports faster compliance adaptation and premium bespoke pricing.
- Security Doors Factory (UK) — Focused on locally manufactured pivot doors and security windows, demonstrating the strength of “Made in” value propositions in certain commercial and residential niches. Strategic take: local manufacturing + customization is a durable defense against low-cost imports.
- Steel Shield Security Doors and More (US) — A regional custom steel door player targeting residential and HOA markets, showing how geographic focus and channel intimacy can produce defensible niches. Strategic take: regional specialists can dominate retrofit channels and community associations with targeted service models.
- Titan Steel Door (US) — Supplies force‑resistant doors and frames for detention and secure facilities; an example of vertical specialization into safety‑critical institutional segments. Strategic take: serving regulated institutions requires deep compliance expertise and long sales cycles but yields durable contracts.
- Larson Doors, Titan Security, Defender Door & Window (US) — These firms represent a range from storm/security storm doors to premium screen doors and entry protection. Collectively they show how adjacent home-protection categories can be a growth runway for core security door manufacturers through product line extensions and channel partnerships.
Recent market events — from high-profile product unveilings at major security shows to trade fair exhibits focused on fire-rated and access-controlled systems — are amplifying buyer awareness. These events also accelerate competitive benchmarking; companies that fail to show product-roadmap compliance risk losing specification slots in large projects.
What our full PW Consulting report contains (practical, actionable deliverables)
The complete study provides a set of deliverables tailored to support strategic decision-making in 2026:
- Topline market sizing: historical (2020–2025), base year detail (2025) and long-range forecasts (2026–2032) with scenario sensitivity around macroeconomic and regulatory shocks.
- Comprehensive segmentation (by product architecture, application, and region) with interactive tables and time‑series — note: subsegment datapoints are not disclosed in this primer.
- Competitive profiles and a benchmarking matrix: product capability, certification status, channel footprint and go‑to‑market DNA for leading and challenger firms.
- Regulatory and standards matrix: pulse on recent UL updates and their programmatic impact on certification pipelines, test-lab capacity and time-to-market for new designs.
- Strategic playbooks: M&A screening criteria, three-tier channel strategies, price-to-win models for large tenders, and a procurement checklist for lifecycle total-cost-of-ownership (TCO) decisions.
- Scenario planning and stress tests: what 3%–10% demand shocks, supply chain disruption, or accelerated regulation look like to portfolio returns.
How to use this intelligence in 2026 — an execution roadmap
- First 90 days: Re-run supplier shortlists against the report’s compliance matrix; prioritize suppliers with validated UL experience for near-term tenders. Initiate pilot retrofit projects with suppliers offering modular installation kits to shorten implementation risk.
- 6–12 months: If pursuing growth, begin diligence on 1–2 bolt-ons that add certification capacity or channel reach. For product teams, accelerate firmware‑secure designs and align new SKUs to the updated UL test timelines to avoid rework.
- 12–36 months: Scale integrated service offerings (installation + ongoing diagnostics) and explore subscription revenue models for monitoring/maintenance. Pursue consolidation plays that aggregate regional installers to create national distribution platforms.
Final perspective
The Security Door Market in 2026 presents a classic opportunity set for disciplined operators: steady topline growth backed by technology-led differentiation and an evolving regulatory environment that favors suppliers who invest early in compliance and integration. Fragmentation means strategic moves — whether through targeted M&A, channel optimization or product innovation — can unlock outsized returns. Yet, realizing these returns depends on granular, segment-level intelligence and validated competitor benchmarking, which this primer intentionally omits to preserve its role as a gateway.
For boards, corporate development teams, product leaders and procurement heads seeking the specific segmentation metrics, benchmarking tables and playbooks needed to act in 2026, our full Security Door Market report provides the data, models and decision templates. Reach out to PW Consulting or visit our report page to access the complete study and our customized advisory offerings.
For detailed analysis of this topic, please visit the official page: Security Door Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com