

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Same-Day Delivery to Reach USD 55.22B by 2032, Growing at a 20.96% CAGR — PW Consulting Insight

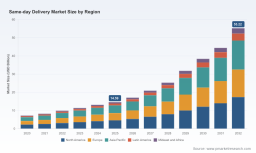
Same‑day Delivery Market: Strategic Imperatives for 2026 — A PW Consulting Preview
Executive snapshot
The same‑day delivery sector has moved from a competitive differentiator to a core operating requirement for retail, grocery, healthcare, and B2B value chains. PW Consulting’s latest market study (base year 2025) shows the market accelerating at a compound annual growth rate of 20.96% through our 2026–2032 forecast horizon. After roughly doubling in size from 2020 to 2025, total market revenue in 2025 stood at USD 14.59 Billion and — under our central scenario — is projected to exceed USD 55 Billion by 2032. That pace creates both strategic urgency and lucrative opportunity for organizations crafting their 2026 resource allocations.
Same-day Delivery Market
Why this study matters to decisions you will make in 2026
-
Timing: With consumer expectations and enterprise capability converging, 2026 is a pivotal year for committing capital and operational models. Quick moves now capture outsized market share while late entrants face higher customer acquisition costs and steeper margins pressure.
Same-day Delivery Market -
Risk management: Regulatory changes and labor re‑pricing are crystallizing. Our analysis synthesizes outcomes across alternative labor regimes and crowdsourced hybrid models, enabling CFOs and COOs to stress‑test capital and operating budgets against plausible 2026 policy shifts.
Same-day Delivery Market -
Vendor strategy: The market remains relatively unconcentrated by global incumbents (top‑three players account for a minority share of global volumes). This fragmentation means differentiated partnership strategies and local scale plays can be decisive — especially where last‑mile margins vary dramatically.
Market dynamics shaping 2026 strategy
-
Demand elasticity and consumer willingness to pay: Our consumer modelling shows a persistent premium for immediacy — a majority of buyers expect same‑day options and a meaningful subset will pay extra for faster fulfilment. Pricing architecture that captures that premium without eroding conversion will be a top strategic lever for 2026.
-
Network topology evolution: We identify a clear shift toward hybridization — conversion of rural stations into micro‑hubs, increased use of ship‑from‑store, and wider deployment of micro‑fulfillment centers. These changes reduce door‑to‑door times but require capital, cross‑functional redesign, and new inventory policies.
-
Workforce and regulatory friction: Local ordinances and renewed scrutiny of gig employment models are changing the cost calculus of crowdsourced fleets. Operators that secure compliant contracts, invest in driver safety/certification, and build flexible staffing models will preserve margin and service quality.
-
Service differentiation: The space is expanding beyond groceries and food into apparel, electronics, urgent B2B parts and healthcare deliveries. This product mix diversity demands tailored handling, routing, and SLA frameworks — and differentiates winners from commodity carriers.
Competitive landscape — who is shaping same‑day today
The sector features a mix of global integrators, national retailers with captive networks, and platform‑based crowdsourced players. Key market actors include Amazon, FedEx, UPS (including the Roadie platform), Walmart (and Sam’s Club), Target, DoorDash, Instacart, Shipt, and Roadie — each pursuing distinct strategies that together map an evolving competitive topology.
-
Amazon continues to scale depth and density, converting local stations into hybrid hubs to broaden reach and shorten fulfilment windows — a move that materially expands viable same‑day catchments for Prime members in smaller population centers.
-
Traditional carriers (FedEx, UPS) are layering time‑definite same‑day products and integrating crowdsourced capacity to serve ad‑hoc surges and special SKUs, balancing speed with cost control.
-
National retailers (Walmart, Target and Sam’s Club) are leveraging store networks for inventory proximity and experimenting with sub‑hour delivery in dense corridors, making store operations a critical point of strategic investment.
-
Platform players (DoorDash, Instacart, Shipt, Roadie) are extending beyond food into retail fulfilment, offering low‑friction retail partnerships and on‑demand capacity that reduce time‑to‑market for brands seeking same‑day presence.
Notable 2026 developments that influenced our analysis include Amazon’s push into thousands of smaller towns via hybrid hubs (Feb 2026), FedEx’s new time‑definite SameDay Local product (Mar 2026), Sam’s Club debuting 1‑hour delivery (Mar 2026), Target expanding next‑day reach (May 2026), and DoorDash widening retail partnerships (Apr 2026). These moves illustrate two intersecting trends: geographic densification of same‑day supply and product category expansion into mainstream retail.
What PW Consulting’s report contains (practical, executable intelligence)
-
Robust market sizing and scenarios — top‑down and bottom‑up approaches calibrated to 2020–2025 realized flows, with sensitivity analyses across three adoption trajectories through 2032.
-
Segment economics and cost‑to‑serve models — modular spreadsheets that allow you to toggle labour regimes, vehicle mixes, average order values, and fulfilment radii to produce bespoke unit economics.
-
Network design playbook — site selection criteria for micro‑fulfilment and hybrid hub conversion, inventory allocation heuristics, and a phased rollout template that minimizes service disruption.
-
Vendor and partnership matrix — evaluation criteria and scoring for carriers, platform partners, and technology vendors (including integration complexity, SLA performance, commercial terms, and scalability).
-
Regulatory and labour impact module — scenario outputs that quantify margin sensitivity to wage changes, certification costs, and gig‑work policy permutations.
-
Operational KPIs and 90‑day pilot templates — defined metrics (cost per order, same‑day attach rate, AOV lift, on‑time SLA, driver utilization) and a sprint plan to test hypotheses with minimal capital outlay.
-
Investor and board‑ready slide pack — concise recommendations, upside/downside cases, and trigger points for escalation or additional investment.
Actionable recommendations for 2026 (for CEOs, COOs, CPOs, and Heads of Logistics)
-
Decide your value capture model: define whether same‑day is an acquisition channel, a margin‑enhancing product, or a loss‑leader. This choice drives pricing, inventory policy, and whether to build or partner.
-
Pilot fast, scale selectively: run 12‑week pilots that couple store‑based fulfilment with dynamic pricing experiments; use our cost‑to‑serve tool to set success thresholds before committing capex.
-
Design for regulatory resilience: model wage and certification shocks into your unit economics and prefer contractual flex (e.g., variable pay components, scalable contractor pools) where feasible.
-
Leverage hybrid capacity: convert select rural or underutilized facilities into hybrid hubs to broaden same‑day reach without a full greenfield build.
-
Monetize service tiers: introduce transparent service tiers (free/standard, paid accelerated, premium guaranteed windows) and A/B test to identify optimal price elasticity.
-
Operationalize data flows: invest in last‑mile orchestration, real‑time capacity signals, and predictive ETA engines to compress failed delivery rates and reduce re‑delivers — the largest hidden cost center in same‑day operations.
How to read the signals — a short checklist for 2026 investment decisions
-
Is your current service level delivering a measurable revenue premium (AOV lift or conversion)? If not, recalibrate pricing or target product lines where immediacy truly matters.
-
Can you run with a partner to test customer acceptance without capex? If yes, run a controlled cohort test to establish baseline economics.
-
Have you stress‑tested your model against a wage‑upside and regulatory compliance costs? Use scenario outputs to set go/no‑go investment gates.
-
Do you have an exit or scale trigger? Establish measurable KPIs (cost per order, attach rate, margin contribution) that automatically trigger scale‑up or wind‑down.
Why PW Consulting’s preview — and what we intentionally withhold
This preview is designed to communicate the strategic contours and practical implications of a rapidly expanding same‑day market so executives can begin to prioritize 2026 decisions. Consistent with our “preview” approach, we deliberately omit the granular split tables and proprietary segment breakouts (regional percentages, per‑channel revenue slices, and detailed vendor share snapshots) from this public summary. Those detailed segmentations and our interactive financial models are available in the full report and the report portal, where clients can access downloadable tools and run customized scenarios against their internal assumptions.
Next steps
-
For immediate decision support in 2026, request PW Consulting’s executive briefing and the interactive cost‑to‑serve model. These resources will allow your team to run the exact scenarios your CFO needs for Budget 2026 and to set pragmatic pilot targets for H1 2026.
-
If you are evaluating build vs. partner options, schedule a workshop with our network design and vendor selection specialists to translate market signals into a 12‑24 month implementation roadmap.
Same‑day delivery is no longer an experiment — it is an axis along which market share, customer lifetime value, and operational excellence will be contested in 2026. PW Consulting’s full study provides the empirical foundation and the executable tools to ensure that your organization’s investments are timed, sized, and structured to win. For complete segment analyses, vendor share tables, and our downloadable scenario models, please visit the full report page or contact your PW Consulting representative.
For detailed analysis of this topic, please visit the official page: Same-day Delivery Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com