

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Mancozeb Market — USD 1,675M in 2025; 4.55% CAGR to 2032

Mancozeb Market — Strategic Preview for 2026 Decision-Making
Executive snapshot
As companies set budgets, procurement strategies and portfolio priorities for 2026, the global mancozeb market is entering a phase in which regulatory friction, concentrated supplier power and steady demand growth will jointly shape commercial outcomes. Our PW Consulting study (base year 2025) synthesizes a seven-year forecast horizon (2026–2032) and a five‑year historical window (2020–2025) to give leadership teams the scenario intelligence required to act with conviction. Key macro facts that frame the thinking in this preview: the market is measured in USD Million, registered a recovery and growth trajectory through 2020–2025, and our modeled compound annual growth rate for the forecast window is 4.55%.
Mancozeb Market
Market trajectory: what the topline shows
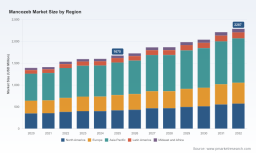
Using consistent USD-million accounting, the market size expanded from the low‑1,400s in 2020 to about 1,675 in 2025 (base year) and is projected to reach roughly 2,287 by 2032 under the central case. The 4.55% CAGR that underpins our forecast reflects a balance of persistent crop protection demand, substitution dynamics where regulatory constraints bite, and episodic supply dislocations that create short-term price volatility.
Mancozeb Market
- Recovery and resilience: Historical volumes and values show the market regained momentum after global agricultural disruptions in the early 2020s, stabilising into a mid-single-digit growth profile by 2025.
- Durable demand drivers: Mancozeb continues to be embedded in disease‑management programs for high‑value crops, which underpins baseline demand even where use is restricted by regulation.
- Price and supply sensitivity: Periodic supply tightness—driven by feedstock availability and regulatory-driven export flows—creates asymmetric price responses that favor nimble producers and well‑positioned buyers.
Competitive landscape and implications
The market exhibits moderate concentration: the top three players account for a meaningful but not dominant share, and the top five push the concentration higher. This structure influences negotiation dynamics, margin capture and the pace of consolidation.
Mancozeb Market
- Concentration metrics: CR3 and CR5 measures indicate a market where leading manufacturers exert pricing and distribution influence, but meaningful room remains for regional specialists and challenger players.
- Strategic moves to watch: Recent deal flow and tactical pricing actions have already altered the competitive map. One major player completed a notable acquisition of a solo mancozeb business in 2024, consolidating a legacy brand and access to proprietary formulation technologies. That same player executed a targeted price adjustment in 2025 in response to tighter supply and demand realignment, illustrating how ownership moves and commercial policy quickly translate to market pricing.
- Profiles at a glance: Legacy formulators and technical-grade producers span established multinationals and regional champions. Competitive positioning now hinges on brand portfolios, formulation IP, downstream channel reach and the ability to manage regulatory exposure across jurisdictions.
Regulatory and trade risk — a core strategic variable
Regulatory dynamics are the single largest non‑demand variable in our scenarios. Mancozeb has been the subject of enduring regulatory scrutiny: it was banned for use in certain markets in 2020 due to reproductive toxicity designations, even while production and export activity continue to be notified and tracked. Parallel registration reviews and risk mitigations in other major jurisdictions add layers of complexity that alter both legal market access and reputational calculus for corporates.
- Dual reality of bans vs. exports: In some regulatory regimes, domestic use is prohibited but production and exports continue under notified frameworks. That dichotomy creates cross‑border arbitrage opportunities and compliance obligations for producers and trading houses.
- Ongoing reviews: Classification as a toxicant for reproduction and as an endocrine disruptor has prompted registration and mitigation discussions in certain major markets, potentially tightening use-patterns or requiring label and application restrictions.
- Operational consequence: Companies must overlay regulatory timelines on supply contracts, insurance exposures and customer segmentation to avoid stranded inventory, compliance breaches or reputational damage.
Practical implications for 2026 corporate strategy
For executive teams deciding where to allocate R&D, capex, procurement and commercial investment in 2026, the PW Consulting view delivers three practical priorities:
- Hedge for regulatory and supply volatility: Negotiate flexible supply contracts that incorporate regulatory‑event triggers, and maintain dual‑sourced supplier relationships for critical technical grades. Tactical inventory buffers calibrated by probabilistic regulatory scenarios are more cost‑efficient than one‑size safety stock policies.
- Reassess go‑to‑market segmentation: Differentiate customer segments by regulatory exposure and willingness to pay for compliant, branded formulations versus commoditized technical supply. That segmentation guides sales compensation, distribution investments and account management intensity.
- Make M&A and partnership decisions with a regulatory overlay: Acquisition targets should be evaluated not only on their volumes or geographic footprints, but also on the regulatory risk embedded in their end‑market exposure and product registrations. Technology or formulation assets that reduce application rates or improve environmental profiles increase optionality.
Competitive scenarios and likely market moves
We model three plausible competitive scenarios for 2026–2030, each with distinct strategic implications for market participants:
- Consolidation with premiumization: Continued M&A among established producers and brand owners results in higher price discipline and premiumization of differentiated formulations. Winners invest in supply chain control and secure feedstock agreements.
- Regulatory fragmentation: Increasing disparity in national regulations forces a bifurcated market—commoditized technical exports flow through tolerant trade channels while constrained domestic markets favor alternative chemistries and integrated pest management solutions.
- Innovation‑led substitution: Accelerated adoption of alternative active ingredients and non‑chemical controls reduces long‑term volumes for legacy fungicides, but creates niches for value‑added formulations and digital agronomy services around disease forecasting and optimized application.
What PW Consulting’s full report equips you to do
The full Mancozeb Market research report is designed as an operational playbook for commercial and corporate strategy teams. It goes beyond narrative to supply analytical tools you can deploy immediately:
- Market sizing and scenario engine: Granular forecast models (to 2032) with demand drivers, elasticity assumptions and alternative regulatory scenarios — model-ready for internal stress testing.
- Supply chain and supplier maps: Verified manufacturer, toll-producer and distribution footprints with capacity overlays and points of single-source risk.
- Pricing and cost models: TPM for raw materials, landed cost calculators, and price‑sensitivity matrices that integrate recent benchmark actions and probable near‑term moves.
- Regulatory exposure grid: Jurisdictional timeline, export‑notification exposure, and compliance impact scoring to prioritize markets and customer types.
- Commercial playbooks: Channel prioritization, value proposition frames for branded vs. generic offerings, and segmented go‑to‑market approaches by customer risk profile.
- M&A and partnership frameworks: Due‑diligence checklists tailored to mancozeb assets, valuation adjustments for regulatory risk, and integration checklists for acquired formulation IP.
How to use the report in your 2026 planning cycle
Leaders should integrate our findings into three planning horizons:
- Short term (0–12 months): Implement purchasing flex clauses, reprice key accounts using the provided price elasticity tools, and prioritise inventory located in low‑regulatory‑risk corridors.
- Medium term (12–36 months): Rebalance product portfolios toward compliant formulations and invest in registration strategies or formulation innovations that lengthen the product lifecycle in higher‑value markets.
- Long term (36+ months): Reassess capital allocation to favour firms and assets that reduce dependence on a single active ingredient through diversification, service layers, or acquisition of complementary technologies.
Final note — the “trailer” approach
The analysis above is intended to demonstrate the depth and practical orientation of PW Consulting’s work: rigorous macro sizing, scenario-enabled forecasts, and direct playbooks for procurement, commercial and M&A decision-makers. To preserve the commercial utility of the full intelligence set and encourage evidence‑based action, we have intentionally summarized directional findings here while reserving detailed segmentation datasets, country‑level exposure tables and the full scenario engine for the complete report.
For executives preparing 2026 budgets and strategic roadmaps, this is the moment to convert awareness into actionable positioning. Access the full Mancozeb Market report for the detailed tables, downloadable models and step‑by‑step implementation guides that will let your team operationalize the scenarios and capture advantage where it emerges.
For detailed analysis of this topic, please visit the official page: Mancozeb Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com