

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Security Door Market to Reach USD 344.8M by 2032 at 6.98% CAGR

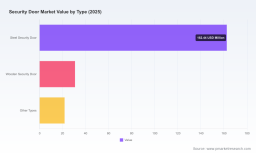
Security Door Market — 2026 Strategic Primer
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present a focused, practitioner-oriented overview of the Security Door Market designed to inform leadership decisions in 2026. This briefing demonstrates the analytical depth underpinning our full market study while deliberately withholding granular segment-level datapoints — a purposeful “trailer” to prompt access to the primary report for executable intelligence.
Security Door Market
Market at a Glance
Using 2025 as the base year and tracing performance from 2020 through 2025, our model shows a market that has steadily expanded through cycles of demand and supply-side adjustment. The global market grew from the low‑hundreds of USD million in 2020 to a stronger position by the 2025 base year, and our forecast through 2032 projects continued expansion at a compound annual growth rate (CAGR) of approximately 6.98% over the 2026–2032 horizon. By 2032 the market is expected to be materially larger than the 2025 base, underscoring persistent opportunity for suppliers, integrators and institutional purchasers.
Security Door Market
Market concentration remains relatively low: the top three and top five players account for only a modest share of global revenues, indicating a fragmented landscape with room for consolidation and differentiation. That structure changes the calculus for strategic moves — scale benefits are real but accessible through targeted M&A, distribution partnerships and channel-play strategies rather than purely organic national roll-ups.
Security Door Market
Why this study matters for 2026 decisions
- Capital allocation: Investors and corporate development teams can use the topline trajectory and concentration profile to calibrate trophy acquisitions versus bolt-on buys aimed at niche capabilities (e.g., force-resistant systems, integrated access-control hardware).
- Product strategy: Manufacturers and OEMs will face higher returns on R&D investments focused on compliance-led design, modularity and integrated electronics as standards and end-user expectations evolve.
- Procurement and risk: Facilities and property managers will need to re-assess supplier risk and lifecycle costs given intensifying regulatory and testing requirements for locks, hardware and fire/security interfaces.
- Channel playbooks: Distributors and installers can exploit fragmentation by offering bundled services (installation + warranty + remote monitoring) to professionalize the retrofit market.
Key dynamics shaping 2026
- Regulatory tightening: The regulatory environment tightened meaningfully entering 2026. New mandatory testing for locks and hardware (notably recent UL updates) increases the compliance bar for new product introductions. These changes alter certification timelines and raise the cost of entry for niche manufacturers while advantaging suppliers with in-house testing and certification experience.
- Security + safety convergence: Fire safety, access control and data-protection obligations are now jointly shaping product specifications. Solutions that successfully balance forced-entry resistance with fire-rating and electronic access integration will capture disproportionate share of large institutional tenders.
- Product innovation vectors: Expect continued emphasis on force-resistant steel systems, modular door frames for rapid field retrofits, and smart-hardware integration (secure firmware, remote audit trails). Physical robustness remains table stakes; differentiation increasingly comes through system integration and lifecycle services.
- Channel and procurement shifts: New-build demand remains important, but retrofit and HOA/association markets are growing faster in some regions. Value is migrating toward providers who can offer turn-key solutions and warranty-backed installation networks.
- Events and market signaling: Industry shows and product collaborations throughout 2025–mid‑2026 have accelerated brand visibility and buyer education — an important lead indicator for adoption cycles.
Competitive landscape — what matters to 2026 strategic plans
The market includes a mix of specialist fabricators, regional manufacturers and companies focused on niche verticals (detention facilities, HOAs, residential bespoke doors). Below is a synthesized view of representative players and the strategic implications they reveal.
- Latham's Steel Doors (UK) — A specialist in high‑security steel residential and commercial doors, increasingly visible through product collaborations and event marketing. Their recent public demonstrations of a celebrity‑endorsed, high-profile product highlight how branding and experiential marketing can accelerate premium segment demand. Strategic take: high-margin differentiation via performance marketing and demonstration-led sales.
- Secure House (UK) — In-house manufacture of bespoke high-security doors and associated products positions them to control quality and certification pathways. Strategic take: vertical integration supports faster compliance adaptation and premium bespoke pricing.
- Security Doors Factory (UK) — Focused on locally manufactured pivot doors and security windows, demonstrating the strength of “Made in” value propositions in certain commercial and residential niches. Strategic take: local manufacturing + customization is a durable defense against low-cost imports.
- Steel Shield Security Doors and More (US) — A regional custom steel door player targeting residential and HOA markets, showing how geographic focus and channel intimacy can produce defensible niches. Strategic take: regional specialists can dominate retrofit channels and community associations with targeted service models.
- Titan Steel Door (US) — Supplies force‑resistant doors and frames for detention and secure facilities; an example of vertical specialization into safety‑critical institutional segments. Strategic take: serving regulated institutions requires deep compliance expertise and long sales cycles but yields durable contracts.
- Larson Doors, Titan Security, Defender Door & Window (US) — These firms represent a range from storm/security storm doors to premium screen doors and entry protection. Collectively they show how adjacent home-protection categories can be a growth runway for core security door manufacturers through product line extensions and channel partnerships.
Recent market events — from high-profile product unveilings at major security shows to trade fair exhibits focused on fire-rated and access-controlled systems — are amplifying buyer awareness. These events also accelerate competitive benchmarking; companies that fail to show product-roadmap compliance risk losing specification slots in large projects.
What our full PW Consulting report contains (practical, actionable deliverables)
The complete study provides a set of deliverables tailored to support strategic decision-making in 2026:
- Topline market sizing: historical (2020–2025), base year detail (2025) and long-range forecasts (2026–2032) with scenario sensitivity around macroeconomic and regulatory shocks.
- Comprehensive segmentation (by product architecture, application, and region) with interactive tables and time‑series — note: subsegment datapoints are not disclosed in this primer.
- Competitive profiles and a benchmarking matrix: product capability, certification status, channel footprint and go‑to‑market DNA for leading and challenger firms.
- Regulatory and standards matrix: pulse on recent UL updates and their programmatic impact on certification pipelines, test-lab capacity and time-to-market for new designs.
- Strategic playbooks: M&A screening criteria, three-tier channel strategies, price-to-win models for large tenders, and a procurement checklist for lifecycle total-cost-of-ownership (TCO) decisions.
- Scenario planning and stress tests: what 3%–10% demand shocks, supply chain disruption, or accelerated regulation look like to portfolio returns.
How to use this intelligence in 2026 — an execution roadmap
- First 90 days: Re-run supplier shortlists against the report’s compliance matrix; prioritize suppliers with validated UL experience for near-term tenders. Initiate pilot retrofit projects with suppliers offering modular installation kits to shorten implementation risk.
- 6–12 months: If pursuing growth, begin diligence on 1–2 bolt-ons that add certification capacity or channel reach. For product teams, accelerate firmware‑secure designs and align new SKUs to the updated UL test timelines to avoid rework.
- 12–36 months: Scale integrated service offerings (installation + ongoing diagnostics) and explore subscription revenue models for monitoring/maintenance. Pursue consolidation plays that aggregate regional installers to create national distribution platforms.
Final perspective
The Security Door Market in 2026 presents a classic opportunity set for disciplined operators: steady topline growth backed by technology-led differentiation and an evolving regulatory environment that favors suppliers who invest early in compliance and integration. Fragmentation means strategic moves — whether through targeted M&A, channel optimization or product innovation — can unlock outsized returns. Yet, realizing these returns depends on granular, segment-level intelligence and validated competitor benchmarking, which this primer intentionally omits to preserve its role as a gateway.
For boards, corporate development teams, product leaders and procurement heads seeking the specific segmentation metrics, benchmarking tables and playbooks needed to act in 2026, our full Security Door Market report provides the data, models and decision templates. Reach out to PW Consulting or visit our report page to access the complete study and our customized advisory offerings.
For detailed analysis of this topic, please visit the official page: Security Door Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com