

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Marble Market Hits USD 23.5B in 2025, Set for 4.61% CAGR — PW Consulting

Marble Market 2026: A Strategic Preview for Leaders and Investors
Executive snapshot
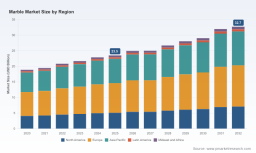
The global marble market has moved from a niche commodity into a strategic input for architects, developers, and premium manufacturers. Using 2025 as a base year, our analysis shows the market at approximately USD 23.5 Billion, having experienced steady expansion through 2020–2025 and set to continue growth through the 2026–2032 forecast horizon. Under the baseline outlook the market grows at a compound annual growth rate of roughly 4.61%, reaching an anticipated market size in the early 2030s that is materially larger than today. For 2026 decision-makers this context is not just background: it defines the opportunity window, the timing of capital allocation, and the competitive urgency that should shape strategy-setting in the year ahead.
Marble Market
Why this report matters for 2026 strategic decisions
-
Timing and scale of investment: With predictable, mid-single-digit CAGR dynamics, executives must reconcile longer lead-time investments (quarry development, downstream processing capacity, automation) with cyclical demand. Our research clarifies when incremental capacity is likely to be absorbed and where margin expansion is most attainable.
Marble Market -
Supply-chain risk becomes a differentiator: Raw material extraction and processing costs fluctuated materially in 2025. The companies that succeed in 2026 will be those that translate supply resilience into guaranteed lead times and predictable cost curves—especially for premium architectural projects where time and quality command price.
Marble Market -
Regulatory and trade policy create both headwinds and arbitrage: Recent tariff reclassifications and evolving construction product standards mean sourcing strategies must be re-evaluated now. Our analysis highlights where compliance overhead and duty exposure move the break-even of import vs. local sourcing decisions.
-
Product and service differentiation is intensifying: Premium finishes, custom installations, and integrated offering bundles (stone + installation + digital visualization) are driving higher per-project value. Companies that reconfigure sales, marketing, and manufacturing to capture these segments will see outsized returns.
-
Consolidation and competitive positioning: Market concentration is meaningful but incomplete—the top-tier players capture a material share but leave room for focused challengers. The next 18 months will be decisive for M&A and strategic partnerships.
What the full study delivers (operationally actionable content)
-
Robust market sizing and trend models anchored to 2020–2025 historicals and a 2026–2032 forecast framework (methodology, assumptions, and sensitivity ranges included).
-
Tariff and regulatory impact matrices: scenario-driven estimates of duty changes, classification risk, and compliance cost for cross-border flows—built for finance and legal teams to model near-term P&L impacts.
-
Supplier and quarry scorecards: operational KPIs, quality profiles, throughput constraints and upgrade pathways (presented in an anonymized benchmarking format suited for procurement negotiations).
-
Route-to-market playbooks by product archetype: premium architectural, mid-market surfacing, and engineered/synthetic alternatives—covering go-to-market tactics, recommended commercial terms, and digital sales enablement.
-
Capex prioritization and ROI calculators that embed extraction costs, processing automation, and logistics scenarios so owners can compare brownfield upgrades versus greenfield options.
-
Risk and opportunity heatmaps: raw-material price stress tests, supply interruption mapping, and demand-shock scenarios with operational mitigations and contingency checklists.
-
M&A readiness and integration checklist for acquirers and targets: valuation heuristics, cultural integration flags, and quick-win synergies for bolt-on quarry or downstream processing acquisitions.
Competitive landscape — who matters and why
The competitive field combines long-established quarry owners, vertically integrated processors, and regional specialists. Several firms consistently surface as strategic reference points for buyers, specifiers, and acquirers:
-
Levantina y Asociados de Minerales, S.A. (Alicante, Spain) — renowned for quarrying and large-format slab collections and for recent creative product launches aimed at high-impact installations.
-
Antolini Luigi & C. S.p.A. (Italy) — a premium processor with a strong position in architectural and decorative stone, often driving trends in surface design and finishing techniques.
-
Polycor Inc. (Quebec, Canada) — vertically integrated through quarrying and distribution, with a reputation in façade and monumental stone applications.
-
Mid-sized and regional specialists (including several European and Mediterranean quarry operators) — these players are critical to niche supply, high-quality blocks, and flexible processing for bespoke projects.
Recent product and marketing moves—such as major collection launches and trade-show debuts—underscore a shift toward experiential marketing and higher-margin finished products. Our competitive chapter includes strategic positioning maps, capability matrices, and acquisition targets by strategic intent (scale, premium access, or regional fill-in).
Market dynamics to watch into 2026
-
Raw materials and processing costs: 2025 saw notable volatility driven by extraction and energy costs. Buyers and processors must rebuild cost models with forward curves; our report provides scenario-based unit-cost decks and break-even thresholds for pricing strategies.
-
Trade policy and classification updates: Recent revisions to tariff classifications affect landed costs for slab imports. Procurement teams should incorporate these policy shifts into sourcing decisions and contractual terms to avoid margin erosion.
-
Standards and compliance in construction markets: Evolving product marking and performance declarations in major construction markets increase the administrative and testing burden for exporters. The study maps the compliance steps and likely timelines for adoption.
-
Geopolitical sourcing shifts: Tariff policies and supply-chain geopolitics in major markets continue to re-route flows and create short-term opportunities for locally positioned suppliers or those with multi-origin sourcing strategies.
Strategic playbook for 2026 (prioritized actions)
-
Short-term (next 6–12 months): Stabilize supply through multi-sourcing contracts, institute tariff pass-through clauses where possible, and pilot digital sales tools (visualizers, AR) to accelerate specification conversion in high-value projects.
-
Medium-term (12–36 months): Invest selectively in finishing automation and value-added services (edge work, bespoke cutting, integrated installation services) to capture margin from premium segments. Consider targeted tuck-ins to secure feedstock or specialized processing capability.
-
Long-term (36+ months): Reassess geographic footprint with an eye to resilience and duty optimization. Build sustainability narratives tied to measurable extraction and processing improvements—these will be increasingly decisive in public and institutional projects.
Scenario thinking — three plausible 2026 environments
-
Baseline: Continued steady growth consistent with the multi-year trend and our central forecast; tactical supply and compliance moves protect margins and allow incremental share gains.
-
Downside: Trade frictions or a regional construction slowdown compress demand and lengthen inventory cycles; the response should prioritize cash preservation, flexible sourcing, and conversion of high-cost fixed assets.
-
Upside: Strong premium-building demand and rapid adoption of integrated surface solutions accelerate growth; winners will be those that scale premium collections and secure high-quality feedstock.
How to use this preview
This introduction is designed to give C-suite leaders, corporate development teams, procurement heads, and private equity sponsors a clear sense of what is at stake for 2026. It demonstrates the strategic levers—sourcing, compliance, product, and M&A—that will decide winners. If you are preparing budgets, revising sourcing policies, evaluating acquisition targets, or designing product roadmaps for 2026, the full Marble Market study provides the granular, transaction-ready data and tools to operationalize these strategic choices.
Next steps
If you need scenario-tailored modeling (customized to your cost base or footprint), supplier diligence templates, or a go-to-market playbook adapted to your product mix, PW Consulting can deliver a bespoke engagement. Our full report contains the detailed segmentation, regional and application breakdowns, supplier scorecards, and tariff-by-route analyses that underpin the strategic recommendations summarized here—accessing that material is the most efficient way to convert insight into 2026 action.
For detailed analysis of this topic, please visit the official page: Marble Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com