

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting: 4-HBA Market Eyes 5.2% CAGR (2026–2032) Amid Rising Coatings Demand
By pmarketresearch, 2026-07-13
4-Hydroxybutyl Acrylate (4-HBA) Market — Strategic Primer for 2026 Decision-Makers
As corporate strategies recalibrate for a more complex 2026, 4-Hydroxybutyl Acrylate (4-HBA) is emerging from a niche specialty intermediate into a segment demanding board-level attention. This primer of PW Consulting’s forthcoming 4-HBA Market study synthesizes the high-value strategic signals that industrial leaders, procurement chiefs, and M&A teams must internalize now. It deliberately surfaces proprietary insights and the analytical framing that drive decisions — while reserving granular tables, regional and application-level splits, and scenario-by-scenario financials for the full report.
4-HBA (4-Hydroxybutyl Acrylate) Market
Market snapshot: trajectory and scale
-
Timeframe & scope: Base year 2025 with historical coverage 2020–2025 and an in-depth forecast from 2026–2032.
4-HBA (4-Hydroxybutyl Acrylate) Market -
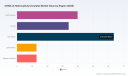
Current scale and momentum: The global 4-HBA market expanded from USD 110.5 Million in 2020 to USD 163.15 Million in 2025, reflecting steady demand across specialty coatings, adhesives, polymer synthesis and UV-curable systems.
4-HBA (4-Hydroxybutyl Acrylate) Market -
Growth outlook: Our model projects a compound annual growth rate (CAGR) of approximately 5.2% over the forecast window, taking the market from roughly USD 174.19 Million in 2026 toward an estimated USD 232.45 Million by 2032.
-
Concentration profile: Market concentration is meaningfully high — the top three suppliers account for roughly 80% of market share, and the top five about 85% — creating a landscape where supplier strategy and capacity decisions materially influence pricing and availability.
Why this matters in 2026 — three strategic themes
-
Supply risk and input sensitivity: Production of 4-HBA is tightly coupled to petrochemical feedstocks (notably acrylic acid and 1,4-butanediol). Volatility in these upstream markets transmits quickly into cost and lead-time risk for downstream formulators. Procurement strategies that ignore feedstock hedging and multi-sourcing are exposed.
-
Regulatory certainty as a commercial enabler: 4-HBA’s registration and compliance with jurisdictions such as REACH and TSCA reduces legal and go-to-market friction for large-scale buyers. In practice, this compliance profile shortens approval cycles for cross-border supply and limits regulatory tail-risk for manufacturers expanding into new geographies.
-
Concentrated competitive dynamics: High CR3/CR5 metrics mean capacity expansions or contract changes from a single incumbent can reprice the market. That dynamic elevates the importance of early-warning market intelligence and targeted engagement with incumbents.
What the PW Consulting 4-HBA study delivers (practical, decision-ready elements)
-
Demand architecture and use-case economics — bottom-up demand models by end-use category, elasticity matrices, and application-level margin levers for formulators.
-
Supply-side scorecards — plant-level capacity, utilization benchmarks, lead-time ladders, and capex timelines that highlight where shortages will first appear under accelerating demand scenarios.
-
Price and cost modeling — input-driven cost-builds (feedstock pass-through, utility and logistics drivers), short-cycle pricing simulations, and contract negotiation playbooks for procurement teams.
-
Regulatory and compliance playbook — jurisdiction-by-jurisdiction requirements summary, timelines for approvals, and a compliance risk matrix tied to product registration frameworks (including REACH and TSCA consistency checks).
-
Risk and scenario tools — three forward scenarios (baseline, accelerated adoption, and supply-constrained) with P&L and NPV impact views for manufacturers, formulators, and distributors.
-
M&A and partnership pipeline — target identification and valuation heuristics for bolt-ons, JVs, and tolling arrangements designed to secure feedstock access or accelerate market entry.
-
Actionable implementation templates — supplier scorecards, contract clause libraries for capacity reservation, and a 100-day tactical plan for new entrants.
Competitive landscape — key players to track
At the center of the market are several established chemical incumbents whose strategic moves will shape the medium-term dynamics. Our report contains a detailed benchmarking of each firm’s capacities, strategic intent, and integration route, summarized here as directional context.
-
BASF SE (Ludwigshafen, Germany) — A broad acrylic monomers portfolio with established scale capabilities in specialty monomers, including offerings that cover 4-HBA. BASF’s global distribution network and vertical integration make its capacity and pricing signals a market metronome. ( https://chemicals.basf.com)
-
Osaka Organic Chemical Industry Ltd. (Osaka, Japan) — Known for hydroxyalkyl acrylates, including 4-HBA, Osaka Organic competes on product breadth and technical support for formulators, with particular strength in regulated markets due to sustained registrations and compliance investments. ( https://www.ooc.co.jp)
-
Mitsubishi Chemical Corporation (Tokyo, Japan) — Produces 4-HBA under product lines that emphasize specialty chemical performance and global compliance. Mitsubishi’s position should be watched for capacity allocation and strategic partnerships within Asia and beyond. ( https://www.m-chemical.co.jp)
These incumbent positions help explain the elevated CR3/CR5 statistics noted above; their capital intensity and integration along acrylic value chains mean supply shifts take time — hence the premium on forward contracting and capacity intelligence.
Supply chain, raw materials and cost levers
-
Upstream dependency: 4-HBA production requires petrochemical intermediates such as acrylic acid and 1,4-butanediol. This link introduces commodity price exposure and feedstock allocation trade-offs across adjacent acrylic monomer streams.
-
Logistics and plant geography: Freight cost differentials and regional feedstock availability create structural advantages for manufacturers proximate to integrated acrylic production. Our supply maps identify choke points and redundancy gaps at the plant and corridor level.
-
Capacity elasticity: Because new capacity for specialty monomers demands sizeable capex and regulatory lead times, near-term supply responsiveness is limited — favoring offtake agreements, tolling arrangements, and co-investment as practical hedges.
Regulatory landscape — compliance as competitive advantage
-
International registrations: 4-HBA is registered under major frameworks such as REACH in Europe and TSCA in the USA; many producers also maintain listings across ENCS, IECSC, and ECL registries. These compliance footprints lower barriers to selling into regulated industries like automotive coatings and industrial adhesives.
-
Regulatory monitoring: For purchasers, supplier compliance status is a primary procurement criterion. Our compliance tracker flags renewal windows, dossier gaps, and jurisdiction-specific labeling or testing requirements that can materially affect time-to-market.
Strategic implications and recommended moves for 2026
-
For manufacturers: Prioritize capacity flexibility and feedstock contracts. Scenario stress tests in our report show that selectively investing in modular retrofit capacity or securing long-term feedstock contracts can yield outsized margin protection when the market tightens.
-
For formulators and brand owners: Transition from spot sourcing to strategic partnerships. Contract terms should move beyond price to include quality-to-spec guarantees, technical support, and joint development clauses to de-risk product launches relying on 4-HBA.
-
For procurement leaders: Implement a two-track strategy — tactical spot engagement for short-cycle needs while accelerating negotiations for multi-year supply agreements with capacity reservation and formula-linked pricing.
-
For M&A and corporate development: Target smaller, high-quality producers with regulatory-complete dossiers or assets that provide geographic arbitrage; tolling agreements and JV structures can be faster and capital-efficient alternatives to outright acquisition.
-
For R&D and product innovation teams: Exploit 4-HBA’s functionality in UV-curable and high-performance coatings — our demand model identifies where substitution economics and regulatory tailwinds create white-space for differentiated formulations.
Scenario thinking and risk mitigation
PW Consulting’s model provides three scenarios to stress-test capital allocation: (1) Baseline — continuation of current trends with 5.2% CAGR; (2) Upside — accelerated adoption in UV-curable and specialty adhesive markets; (3) Constrained — feedstock-driven capacity bottlenecks. Each scenario is translated into P&L and cash-flow impacts for buyers and sellers, enabling decision-makers to quantify downside exposure and prioritize mitigation actions such as strategic stock, multi-sourcing, and upstream integration.
How to use this primer — next steps
-
Immediate action: Use the supplied high-level signals to stress-test 2026 procurement budgets and Q1 supplier engagement plans.
-
Near term: Request the full PW Consulting 4-HBA Market report for the granular tables, regional and application splits, supplier-level capacities, pricing curves, and downloadable Excel models that support transaction-level decisions.
-
Engagement options: We offer deep-dive workshops, custom scenario runs, and supplier negotiation support tailored to your exposure across the value chain.
In sum, 4-HBA is at an inflection where regulatory clarity, upstream feedstock dynamics, and concentrated supplier structures converge to make strategic intelligence indispensable. PW Consulting’s full report converts the headline trajectory — from USD 110.5 Million in 2020 to USD 163.15 Million in 2025 and a forecasted rise toward USD 232.45 Million by 2032 at a 5.2% CAGR — into executable decisions for procurement, production, and M&A. For the granular splits, plant-level maps, and supplier scorecards that operationalize these insights, visit our full study page and schedule a briefing with our industry team.
For detailed analysis of this topic, please visit the official page: 4-HBA (4-Hydroxybutyl Acrylate) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Decorative HPL Market Eyes 5.5% CAGR to USD 18.04 Billion by 2032
By pmarketresearch, 2026-07-13
Decorative High-pressure Laminates (HPL) Market — Strategic Briefing for 2026 Decisions
Executive summary
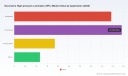
As companies map growth and resilience plans for 2026, the decorative High-pressure Laminates (HPL) sector presents a clear, mid-cycle expansion opportunity underpinned by steady demand and structural change. Our PW Consulting market study — anchored on a 2025 base year and a seven-year forecast horizon to 2032 — projects the global decorative HPL market to expand at a compound annual growth rate (CAGR) of approximately 5.5%. From a commercial standpoint, the market reached a meaningful scale in 2025 and is projected to grow further through 2032, driven by product innovation, substitution dynamics in interior finishes, and regulatory-driven reformulation in supply chains.
Decorative High-pressure Laminates (HPL) Market
Why this study matters to executive teams in 2026
-
Timing for investment: The combination of predictable growth and evolving regulatory thresholds creates windows for capacity upgrades, product repositioning, and selective M&A that can lock in margin expansion before raw material normalization.
Decorative High-pressure Laminates (HPL) Market -
Portfolio resilience: Manufacturers and distributors must reconcile short-term feedstock volatility with long-term demand trends — the report translates those tensions into actionable product- and channel-level playbooks.
Decorative High-pressure Laminates (HPL) Market -
Regulatory preparedness: New emissions limits and certification expectations are not hypothetical — they affect formulations, capital equipment, and route-to-market approvals. Firms that internalize compliance costs and leverage early certification as a commercial differentiator will capture premium placement in spec-driven segments.
High-level market trajectory (what we reveal)
Using five years of historical data (2020–2025) and our scenario-driven modelling through 2032, PW Consulting identifies a structurally growing market. The baseline forecast reflects steady construction and refurbishment activity, continued product migration into higher-value niche grades, and an incremental premium for sustainability-certified laminates. While we intentionally withhold granular regional/application breakdowns here to preserve the executive value of the full report, readers should note the market is neither hyper-fragmented nor monopolized — concentration metrics indicate leading suppliers maintain material commercial influence, but meaningful space exists for regional specialists and innovative entrants.
Key demand and supply dynamics shaping 2026 strategy
-
Substitution and specification shifts: End-users continue to move away from raw timber and lower-performing decorative alternatives in key commercial and residential specifications, boosting the appeal of higher-durability HPL grades. This creates opportunities for premiumization, differentiated finishes, and value-added surface systems.
-
Raw material pressure and formulation choices: Melamine-formaldehyde systems account for the dominant share of resin usage in decorative HPL manufacturing. Recent feedstock volatility — including a supply disruption episode in India linked to methanol-driven formaldehyde price spikes — underscores the need for strategic resin sourcing, hedging strategies, and R&D into low-emission variants.
-
Regulatory tightening as a market force: From the U.S. regulatory environment to forthcoming EU directives, emission standards and low-VOC expectations are recalibrating production norms. Notably, new EU REACH limits coming into effect in 2026 will impose a stricter formaldehyde emissions ceiling for wood-based products, while U.S. frameworks similarly compel adoption of low-emission melamine-formaldehyde variants. These rules will reprice compliance and accelerate reformulation for manufacturers that supply specification-sensitive channels.
-
Sustainability and certification premiums: Buyers — particularly architects, institutional purchasers, and major retailers — are applying certification filters with increased weight. Recent manufacturer certifications and biobased labeling efforts demonstrate the commercial upside to proactive sustainability programs.
Competitive landscape — what to watch (we reveal strategic posture, not confidential metrics)
The decorative HPL industry is anchored by recognizable global brands with diversified portfolios across residential, commercial, and specialty applications. The competitive fabric features legacy laminators with extensive design libraries, European premium innovators, and nimble regional champions. Competitive strength is driven by design capability, distribution reach, sustainability credentials, and the ability to support specification-driven projects.
-
Formica Group — A long-established leader that combines brand recognition with R&D scale. Recent moves to secure bio-based product labeling illustrate a dual focus on sustainability and specification advantage for interiors projects seeking certified materials.
-
Wilsonart LLC — Known for a broad surfaces portfolio and accelerating sustainable product lines. Wilsonart’s recent launch of extended design ranges underscores a go-to-market strategy that pairs aesthetic breadth with low-emission options.
-
EGGER Group — A European player emphasizing multi-layer abrasion resistance and furniture-sector integration; its product approach favors system sales with board and surface combinations.
-
Greenlam Industries — A major global supplier with a strong presence in Asia and an aggressive new-market product roll-out cadence. Regional catalog refreshes demonstrate a strategy to capture architectural trends and local specification needs.
-
Fundermax and Trespa — Specialists that target high-performance and exterior architectural niches; their product leadership is often linked to differentiated material properties such as hygiene, UV resistance, and facade suitability.
-
Pfleiderer, Abet Laminati, Arpa Industriale, Panolam — European and U.S. firms complement the landscape with design-forward and certification-led offerings that appeal to premium buyers and project specifiers.
Recent company-level developments illustrate where competitive advantage is being pursued: certification and biobased labeling, expanded design collections, new texture and woodgrain launches, and localized product introductions targeting growth corridors. These tactical moves are signals: specification-driven markets will increasingly reward certified, differentiated designs backed by reliable supply chains.
What the PW Consulting report delivers (practical content for 2026 action)
Our full study is structured to convert market intelligence into executable decisions. Core deliverables include:
-
Market sizing and base-case/alternative scenario forecasts (2026–2032) with sensitivity to raw material swings and regulatory shocks.
-
Segment-level insights (by grade, application, and region) mapped to distribution channels and procurement cycles — note: detailed segment tables are available in the full report.
-
Competitive benchmarking with capability matrices, recent strategic moves, and supplier SWOTs tuned to tactical responses for price, innovation, and sustainability competition.
-
Supply-chain mapping and risk heatmaps highlighting resin exposure, substitute pathways, and mitigation levers (e.g., alternative chemistries, vertical integration, or contractual hedges).
-
Regulatory impact assessment, including cost-to-compliance modelling for new emission thresholds and certification roadmaps that translate compliance into commercial differentiation.
-
Commercial and product playbooks: SKU rationalization guidance, premiumization pathways, channel strategies (distribution vs. direct spec sales), and pricing elasticity models.
-
M&A and partnership screening framework highlighting target archetypes, valuation considerations under feedstock volatility, and integration checklists focused on technology and certification assets.
-
Implementation timelines and a one-year quick-win plan for 2026 that includes low-cost certification moves, targeted design launches, and tactical inventory positioning to weather feedstock cycles.
Strategic recommendations for 2026
-
Prioritize compliance-led product repositioning: Treat upcoming regulatory thresholds as a product-management opportunity, not just a cost. Fast-tracked certification and transparent emissions data will unlock specification channels.
-
Diversify resin sourcing and invest in formulation R&D to reduce exposure to single-feedstock price shocks. Where feasible, evaluate partnerships with resin suppliers to secure preferential terms or co-develop low-emission systems.
-
Leverage design and sustainability credentials to pursue premiumization in institutional and commercial projects. Designers and architects are early adopters of certified materials; align marketing and specification support accordingly.
-
Use targeted M&A to acquire capability (e.g., compact HPL, specialty exterior grades, or certification-focused technologies) rather than scale alone — given the current concentration dynamics, capability gaps are a faster route to differentiation.
-
Prepare inventory and pricing playbooks for intermittent feedstock disruption: scenario-test margin sensitivity and agree on contingency pricing clauses with key customers in long-lead spec markets.
Conclusion and next steps
The decorative HPL market entering 2026 is predictable enough to plan against, yet dynamic enough that early strategic moves will matter. Our study equips executives with the foresight to balance near-term operational resilience with longer-term brand and product-led differentiation. For procurement leaders, R&D chiefs, and corporate strategists, the decision levers this year will determine who converts regulatory and raw material headwinds into durable commercial advantage.
Accessing the full intelligence
This briefing intentionally foregrounds the strategic implications while holding back detailed segment tables, regional splits, and granular pricing scenarios that constitute the core proprietary value of the full PW Consulting report. To obtain the complete dataset, segment-level forecasts, and executable playbooks for 2026–2032, please consult our report landing page or contact our advisory team to schedule a bespoke briefing tailored to your company’s priorities.
For detailed analysis of this topic, please visit the official page: Decorative High-pressure Laminates (HPL) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: 1,2‑Pentanediol Market to Grow at 6.5% CAGR (2026–2032)
By pmarketresearch, 2026-07-13
Strategic Outlook — 1,2-Pentanediol Market: A 2026 Decision Brief
Executive snapshot
As companies calibrate capital allocation and commercial strategies for 2026, 1,2-pentanediol (pentylene glycol) is emerging as a strategic intermediate that links shifts in personal care formulation, sustainability mandates, and petrochemical feedstock volatility. Our PW Consulting study — anchored on a 2025 base year, a 2020–2025 historical review, and a 2026–2032 forecast horizon — synthesizes market economics, supplier dynamics, regulatory friction points, and technology pathways to create an operationally useful roadmap for decision makers.
1,2-Pentanediol Market
Key macro takeaways you need immediately: the market has grown steadily from the early 2020s into mid-decade and, under our base forecast trajectory, is set to continue expanding through 2032 at a compound annual growth rate aligned with mid-single digits. That trajectory translates into meaningful scale expansion for incumbents and new entrants alike, while also increasing the economic incentives for vertical integration and feedstock innovation.
1,2-Pentanediol Market
Why 2026 is a strategic inflection
-
Convergence of demand drivers: Growth in personal care formulations, renewed R&D in pharmaceutical excipients and pesticide intermediates, and incremental uptake in industrial applications are collectively broadening the total addressable market.
1,2-Pentanediol Market -
Sustainability as a differentiator: Biobased and upcycled feedstock routes have shifted from marketing plus to commercial necessity for a set of premium buyers; buyers are increasingly willing to pay for certified, lower-carbon inputs.
-
Supply-side complexity: Price and availability of traditional petrochemical feedstocks have become more volatile due to regional geopolitical events, feedstock export constraints, and shifts in naphtha/LPG/natural gas markets — increasing the value of diversified sources and regional footprint resilience.
-
Regulatory tightening: A complex regulatory landscape across cosmetic, pharmaceutical and food-contact pathways is creating longer supplier qualification cycles and raising the bar for documentation, testing, and certification.
Market trajectory (what the numbers say)
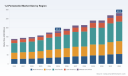
Our historical reconstruction (2020–2025) demonstrates steady recovery and expansion through mid-decade, reflecting both volume growth and premiumization in specific applications. Using 2025 as the base year, the report models multiple forecast scenarios across 2026–2032. Under the central case, the market grows at a mid-single-digit CAGR to reach materially higher scale by 2032. These aggregated dynamics mask pockets of accelerated growth — and pockets of cyclicality — that are explored in the full study via scenario banding and sensitivity testing.
Key strategic implications for 2026 planning
-
Procurement & commercial protection: Buyers should reassess contract tenors and indexation clauses. The combination of feedstock volatility and regional supply interruptions raises the value of blended procurement strategies: longer-term agreements for core volumes, combined with flexible spot exposure for opportunistic sourcing.
-
Capacity investment decisions: For manufacturers and private-equity owners, the question is not simply whether to add capacity, but where (geography & grade) and which technology route to prioritize. Biobased production lines command a price premium in some customer segments, but they also require distinct feedstock certifications and longer qualification timelines.
-
Product & portfolio strategy: C-suite teams should identify which grades and formulations will capture the sustainability and performance premiums over the next two to four years. Cosmetic-grade and specialty derivatives tied to lower-carbon feedstocks are structurally advantaged with certain global buyers, but industrial applications remain cost-sensitive and exposed to petrochemical price swings.
-
M&A and alliance playbook: The market’s structural maturation favors bolt-on acquisitions that provide feedstock security, regional market access, or specialized downstream capabilities (e.g., formulation services for personal care). Joint development agreements and tolling partnerships are an efficient way to de-risk new biobased routes without committing full capex.
-
Regulatory & quality assurance: Expect extended supplier qualification timelines. Firms entering or scaling in this market must invest in regulatory dossiers, third-party testing, and traceability systems to meet customer and jurisdictional requirements.
Competitive landscape — players to watch
The supplier map is a mix of specialized regional producers and global ingredient houses that are moving up the value chain. A few differentiated strategic plays emerge from recent corporate activity and public disclosures:
-
Large ingredient houses that pair marketing reach with dedicated biobased production units are using that capability to accelerate adoption among multinational personal care brands. Dual-site manufacturing and demonstrable upcycling credentials are serving both reliability and sustainability narratives.
-
Specialized chemical manufacturers in Asia continue to anchor cost-competitive supply and quick fulfillment for industrial users, while also investing in regional biobased capacity to capture higher-margin cosmetic demand.
-
Technology differentiation is increasingly commercial: product provenance (e.g., upcycled sugarcane bagasse) and vertically integrated feedstock pathways are shortening supplier selection lists for premium customers.
Recent notable developments include the commissioning of additional biobased production capacity by a major ingredient supplier in Europe, modeled on an existing U.S. site, and industry recognition for sustainability credentials that emphasize upcycled agricultural residues. These moves signal a strategy shift from pilot-scale sustainability proofs to full commercial roll-outs — and they will materially alter supplier selection dynamics for multinational buyers.
Risk map — what keeps CEOs and procurement chiefs awake
-
Feedstock and price volatility: Exposure to n-pentene and other petrochemical-derived inputs creates margin vulnerability for producers and price risk for buyers during geopolitical disruptions.
-
Certification bottlenecks: Sourcing biobased or upcycled feedstocks requires validated chains of custody; delays in certification slow customer qualification and limit near-term market share gains.
-
Regulatory heterogeneity: Diverging rules across cosmetic, pharmaceutical and agrochemical jurisdictions require bespoke compliance strategies, increasing time-to-market.
-
Concentration effects: While a small set of suppliers offers scale and branded biobased grades, regional suppliers retain influence in cost-sensitive segments. This creates a two-speed market where premium and commodity pathways coexist.
What our PW Consulting report delivers — the practical toolkit
This study is designed as an actionable playbook for executives who must make capital, sourcing or go-to-market decisions in 2026. Key deliverables include:
-
Scenario-based demand and price models for 2026–2032, with sensitivity to feedstock price paths and regulatory outcomes.
-
Supply-side intelligence: vetted supplier profiles, capacity maps, and qualitative assessments of operational resilience and feedstock security.
-
Commercial tools: supplier scorecards, contract clause templates (tenor, indexation, force majeure), and a bidding framework for RFP design.
-
Investment decision frameworks: unit-economics templates for greenfield vs. brownfield investments, and an M&A screening matrix that prioritizes feedstock access, technology fit, and customer overlap.
-
Regulatory playbook: jurisdiction-level compliance checklists, expected qualification timelines, and testing/validation roadmaps for cosmetic and pharmaceutical applications.
-
Risk management artifacts: hedging strategies, procurement levers, and a supply-disruption response playbook aligned to board-level crisis scenarios.
To preserve commercial value for subscribers and prospective buyers, the report intentionally positions headline macro trajectories and strategic implications in this brief while retaining the full, granular segmentation tables, supplier-level financials, and proprietary demand models in the full deliverable.
How to use the analysis in 2026 decision cycles
-
Board and Investment Committees — use the scenario models to stress-test capex proposals and to define go/no-go thresholds tied to feedstock price and certification timelines.
-
Commercial & Procurement — reframe supplier negotiations around blended supply strategies and include sustainability credentials in commercially weighted scorecards.
-
R&D and Product Teams — prioritize formulation work that leverages biobased grades where margin uplift is validated; accelerate customer trials with dual-sourced samples to shorten qualification windows.
-
M&A teams — prioritize targets that provide immediate feedstock security or accelerate biobased manufacturing scale without long permitting lead times.
-
Risk & Compliance — build a compliance calendar mapped to customer qualification lead times and regulatory milestones to avoid lost sales from protracted approvals.
Final perspective — an operational judgment
The 1,2-pentanediol market in 2026 is less about an either/or between petrochemical and biobased supply and more about orchestration: producers, buyers and investors who align feedstock strategy, regulatory preparedness, and customer qualification timelines will capture the lion’s share of near-term upside. The market’s growth path creates both opportunity and complexity — rewarding those who use granular supplier intelligence, scenario planning, and disciplined procurement playbooks.
PW Consulting’s full 1,2-Pentanediol Market report provides the data, models, and executable templates that procurement leads, strategy teams, and corporate development groups need to convert this strategic moment into measurable value. For access to the proprietary segmentation, supplier-level forecasts, and the decision-ready toolkits referenced above, consult the full report page or contact your PW Consulting representative.
For detailed analysis of this topic, please visit the official page: 1,2-Pentanediol Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Hydrogen Sulfide Removal Market — USD 2,290M in 2025, 5.5% CAGR to 2032
By pmarketresearch, 2026-07-13
Hydrogen Sulfide Removal Market — Strategic Outlook to 2032 (PW Consulting Preview)
Hydrogen sulfide (H2S) remains one of the most persistent operational, environmental and regulatory challenges across gas processing, produced-water handling, biogas upgrading and downstream refining. PW Consulting’s new market study — built on a 2025 base year with a historical review covering 2020–2025 and a detailed forecast to 2032 — quantifies the sector’s trajectory and translates it into decision-grade recommendations for executives planning capital allocation, technology selection and M&A priorities in 2026.
Hydrogen Sulfide Removal Market
Why the 2026 decision window is decisive
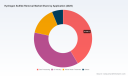
2026 is a strategic inflection point. Our analysis shows the global H2S removal market expanding at a steady compound annual growth rate (CAGR) of 5.5% across the 2026–2032 forecast horizon. On a macro scale, the addressable market rises materially from the 2025 base to reach the low‑thousands of USD Million by 2032, driven by a mix of regulatory tightening, upstream production chemistry, and growth in distributed biogas and wastewater projects.
Hydrogen Sulfide Removal Market
For boardrooms preparing 3‑ to 7‑year investment plans, the implications are clear: near‑term choices on technology platforms, service models and field validation will disproportionately determine competitive positioning across the decade.
Hydrogen Sulfide Removal Market
Market dynamics and growth drivers
- Regulatory tightening and exposure risk: Recent regulatory activity — including U.S. EPA NESHAP limits for fuel gas, OSHA ceiling and peak exposure limits, and sub‑10 ppm discharge expectations under major industrial emissions frameworks — is raising the cost of noncompliance and elevating demand for robust H2S control solutions. Local advisory thresholds for community monitoring in some jurisdictions further increase reputational and permitting risk for operators.
- Energy mix transition and feedstock diversity: Growth in biogas, landfill gas and produced water treatment projects expands the range of source streams with variable H2S loads. Distributed applications favor compact, low‑waste solutions and providers that can package media, controls and service into an operational contract.
- Cost of ownership focus: Buyers are shifting emphasis from capex alone to total cost of ownership — chemistry consumption, media life, waste generation and onsite service frequency. This trend is accelerating adoption of regenerative systems and solutions that minimize solid waste streams.
- Decentralization and modular deployment: Remote gas and onsite wastewater facilities require modular systems with predictable performance. Standardized skid packages, pre‑commissioning and remote monitoring are now procurement expectations in many project tenders.
- Technology convergence and digitalization: Sensors, process analytics and IIoT-enabled service models are enabling performance‑based contracts and predictive maintenance, placing a premium on vendors that combine chemical or adsorbent IP with data services.
Regulatory guardrails shaping procurement and risk
- U.S. EPA NESHAP: fuel gas systems constrained to specified ppm levels for H2S.
- OSHA: a 20 ppm ceiling (with higher short‑term peak limits) for worker exposure that drives the need for reliable scrubbing in personnel access areas.
- Cross‑jurisdictional expectations: both North American and European industrial emissions frameworks are enforcing sub‑10 ppm discharge thresholds in many permitting cases, raising the bar for end‑of‑pipe solutions.
- Local advisory standards for community monitoring are increasingly influencing project siting and operational controls in urban‑adjacent facilities.
Technology and commercial dynamics — what distinguishes winners
The H2S removal market remains technologically varied. Commercial differentiation arises along three dimensions: chemistry/media approach (liquid redox, triazine scavengers, iron‑based adsorbents, mixed metal oxides), lifecycle waste profile (regenerative vs non‑regenerative), and service/digital overlay.
- Regenerative systems: These solutions offer lower recurring media cost and reduced solid waste but typically require greater process integration and O&M capability. They are attractive for high‑volume streams where media regeneration economics pay back.
- Non‑regenerative/scavenger approaches: Simpler to deploy and attractive for small or intermittent streams, but buyers must account for recurring chemical purchases and waste handling constraints.
- Adsorbents and mixed metal oxides: Robust in high‑throughput gas units; lifecycle and replacement cadence are key procurement variables.
- Service and data: The fastest‑growing commercial models pair chemistry or media with service contracts and remote performance guarantees. These reduce operator staffing exposure and shift lifecycle risk to vendors.
PW Consulting’s analysis highlights that commercial outcomes are determined less by a single “best” technology and more by fit‑for‑service: fluid composition, duty cycle, regulatory load‑out, waste handling constraints, and the buyer’s appetite for operational outsourcing.
Competitive landscape — capabilities to map to strategy
The H2S removal vendor set spans specialist chemists, integrated oilfield service firms, and system integrators. Market concentration is modest: the top three suppliers account for roughly a quarter of market revenue, and the top five for about thirty percent, indicating a fragmented field with room for consolidation and niche dominance.
- Merichem Technologies (Houston): Deep experience in liquid redox (LO‑CAT), proprietary adsorbents and engineered vessel systems for gas, biogas and petrochemical streams. Recent field evidence in 2026 shows a commercial step‑change: a June 2026 field trial in a major Permian play reportedly delivered sustained >99% removal from separator gas with no solid waste — a variant that directly addresses lifecycle disposal pressures.
- SLB / Schlumberger (Houston): Brings iron oxide and mixed metal oxide adsorbent portfolios, plus global field service capability. As an oilfield service incumbent, SLB offers scale for large upstream rollouts and integrated production chemistries.
- Streamline Innovations (USA): Focused on liquid redox variants optimized for produced water and high‑H2S streams. A March 2026 case study documented multi‑million‑dollar monthly chemical savings at a high‑H2S produced water facility—evidence of substantial OPEX impact when systems are matched correctly to field conditions.
- FirstKlaz Technologies (USA): Specialist in triazine scavengers, FeO adsorbents and Claus recovery interfaces — a profile that suits operators seeking turnkey sulfur recovery integration.
- Unison Solutions (Dubuque) & MV Technologies (USA): Niche leaders in biogas and landfill gas media, offering iron‑based and carbon systems designed for decentralized, wastewater and agricultural applications.
Across providers, competitive advantage is driven by demonstrable lifecycle economics, warranties tied to performance, and the ability to scale pilot results to multi‑site deployments.
Recent development highlights that shift competitive dynamics
- June 2026 — Merichem announces field trial success for a new ECOTREAT process achieving sustained >99% H2S removal from separator gas without generating solid waste; the vendor is moving to commercial rollout.
- March 2026 — Streamline Innovations publishes a case study showing its ThunderOx system delivered significant chemical OPEX savings at a high‑H2S produced water operation, validating the business case for liquid redox in comparable sites.
What PW Consulting’s full report delivers — operationally actionable insight
This preview is intentionally high‑level. The full PW Consulting study provides the granular, executable intelligence that procurement, operations and corporate development teams need to act in 2026:
- Market sizing and scenario models: base‑case and sensitivity runs across conservative, modal and aggressive adoption pathways (2026–2032), with downloadable model files for in‑house stress testing.
- Vendor benchmark matrix: technology, lifecycle cost modeling, demonstrated field performance, service footprints and contract archetypes to build shortlists matched to buyer archetypes.
- Commercial playbooks: procurement specs, RFP templates, trial design guides and standard KPIs for pilot validation that de‑risk rollouts and shorten procurement cycles.
- Regulatory and permitting matrix: cross‑jurisdictional thresholds, monitoring requirements and compliance timelines that affect both capex sizing and operational O&M regimes.
- M&A and partnership lens: target screening criteria, valuation multiples observed in recent deals, integration risks and recommended diligence checklists for chemistry, IP and service contracts.
- Case studies and unit‑level economics: anonymized, audited project examples that surface true OPEX drivers, replacement cadence and waste handling costs underpinning payback calculations.
How to use this preview to frame your 2026 agenda
- Immediate actions for operators: prioritize pilot programs for high‑exposure streams where regulatory thresholds or worker safety create the highest near‑term risk; require vendors to model total lifecycle cost and to accept contracted performance guarantees.
- For vendors and investors: evaluate technologies not only on removal efficiency but on waste profile, serviceability and data productization; consider consolidation targets where distributive service networks can be leveraged to scale digital, performance‑based contracts.
- For corporate development teams: use 2026 to validate assumptions on media lifespan and operational intensity; close small strategic acquisitions that fill geography or service gaps before competitors scale integrated offerings.
Next steps — where the full findings add value
This preview signals where the market is moving and why 2026 planning cycles should integrate H2S removal strategy into capex, OPEX and compliance programs. The full PW Consulting report provides the data tables, segmentation breakdowns, vendor scorecards and model files you will need to translate this strategic view into executable projects. Detailed regional and application splits, technology adoption curves by use case, and vendor market shares are reserved for the full report — essential inputs for procurement specification, pilot budgeting and M&A underwriting.
Contact PW Consulting to access the complete study, the interactive forecast model and our advisory services to convert the forecast into a 2026‑ready roadmap for your organization.
For detailed analysis of this topic, please visit the official page: Hydrogen Sulfide Removal Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: DVB Market to reach USD 1,305.85 Million by 2032 at 5.67% CAGR
By pmarketresearch, 2026-07-13
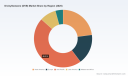
Divinylbenzene (DVB) Market — Strategic Outlook for 2026 Decision-Making
Introduction
As companies refine their 2026 investment plans, procurement strategies, and product roadmaps, a pragmatic, forward-looking view of the divinylbenzene (DVB) market is indispensable. This briefing, drawn from PW Consulting’s comprehensive DVB Market study (base year 2025, forecast 2026–2032), highlights the strategic value of that research for executive decision-makers. It illustrates the actionable intelligence contained in the full report while intentionally withholding granular segment figures — a “trailer” designed to demonstrate analytic depth and to guide you to the full dataset and tactical tools.
Divinylbenzene (DVB) Market
Executive snapshot: the market in context
DVB is a mature specialty monomer used primarily as a cross‑linker in ion‑exchange and chromatographic media, in adhesives and coatings, and across a range of engineered polymer applications. From 2020 to 2025 the industry expanded steadily from roughly USD 674 million to USD 888 million (revenue unit: Million USD, base year 2025). Our modelling indicates continued expansion through the forecast window, reaching an estimated market size in excess of USD 1.3 billion by 2032 under a central-case compound annual growth rate (CAGR) of 5.67% for 2026–2032.
Divinylbenzene (DVB) Market
Concentration metrics point to a moderate level of market consolidation: the top three suppliers account for just under half of market sales while the top five capture roughly two thirds. These dynamics create a market where regional supply security, product quality tiers (standard vs. high‑purity grades), and supplier relationships drive commercial outcomes.
Divinylbenzene (DVB) Market
Why DVB decisions matter in 2026
-
Cross‑linking chemistry remains foundational for water treatment resins, biopharmaceutical chromatography media, and a set of high‑value specialty plastics. Small shifts in DVB quality or availability can cascade into downtime, qualification delays, or margin compression for resin manufacturers and their downstream customers.
-
Regulatory and sustainability pressure is rising: manufacturers face more stringent handling, emissions, and disposal requirements that affect operating costs and capital choices. These considerations are becoming core to make/buy and location decisions.
-
Feedstock volatility — particularly styrene and ethylbenzene — introduces cost variability that directly affects producer margins and can quickly reshape competitive advantage between integrated petrochemical players and specialized producers of high‑purity grades.
What the PW Consulting DVB report delivers — practical, transaction‑ready intelligence
The full study is built for leaders who must translate market intelligence into executable actions. Key deliverables include:
-
Transparent market sizing and demand‑model architecture (2020–2025 historicals, 2026–2032 forecast) with scenario toggles and sensitivity analytics;
-
Price and margin modeling that links crude/petrochemical feedstock scenarios to producer-level EBITDA under alternate pass‑through regimes;
-
End‑use demand maps (resins, chromatographic media, coatings, elastomers) with adoption curves and technology‑substitution risk scoring;
-
Supply side diagnostics: plant‑level capacity, utilization benchmarks, impurity‑control capabilities (critical for chromatography and biopharma grades), and de‑bottlenecking potential;
-
Regulatory & compliance playbook (REACH, TSCA, food‑contact rules, emissions controls) showing cost impacts, timeline risks, and certification requirements;
-
Competitive benchmarking and supplier scorecards including technical capability, geographic footprint, and commercial terms;
-
Deal and investment tools: transaction valuation templates, capex decision trees, NPV/IRR scenarios for brownfield vs greenfield expansions, and negotiation playbooks for long‑term off‑take agreements;
-
Risk heatmaps and an early‑warning indicator set operators can monitor weekly to quarterly.
To preserve commercial value for our clients, this high‑level brief intentionally omits the granular split tables and region/application shares available in the full report.
Competitive dynamics — who matters and why
The DVB supply landscape is shaped by a mix of regional chemical incumbents and specialty monomer specialists. Strategic moves over 2024–2025 show the market bifurcating between scale/integration advantages and specialist premium offerings:
-
Specialty producers with advanced purification capability have moved to secure upstream feedstock and to certify product quality for biopharma chromatography — an attractive, higher‑margin end market. Examples include recent capacity and purification upgrades by firms focused on tighter impurity control to serve premium resin manufacturers.
-
Integrated chemical groups are leveraging broader petrochemical value chains to maintain cost advantages at standard purity points, while selectively investing to supply industrial water‑treatment and coatings segments.
-
Regional players and acquisitions have reshaped North American supply security: recent asset transfers and consolidations were executed to preserve local availability for water‑treatment and specialty coatings customers.
These strategic movements have immediate implications for sourcing risk and pricing volatility: buyers reliant on a narrow set of suppliers for high‑purity grades face different risks than purchasers of standard grades where integrated producers can balance feedstock swings across larger portfolios.
Supply chain, feedstock risk and regulatory tailwinds
-
Feedstock linkage — DVB production is dependent on upstream benzene derivatives (notably ethylbenzene and styrene). Price swings in crude and naphtha translate into variable production economics for DVB makers and require active hedging or contractual pass‑through mechanisms for downstream customers.
-
Regulatory pressure is accelerating: REACH and TSCA impose handling and waste‑management obligations that increase compliance costs for producers; food‑contact rules require specific approvals for styrene/DVB systems used in certain bead products; and recent policy discussions around taxable listings may raise manufacturing or product costs in selected jurisdictions starting early 2026.
-
Environmental limits on aromatics emissions are shaping location and technology choices for capacity expansions — permitting risk is now a material input to capital planning and cycle time estimates.
Strategic considerations for 2026 plans — practical next steps
Below are the high‑impact strategic questions executives should answer in 2026, supported by the analyses included in the full PW Consulting study.
-
Supply security vs cost: Should you pursue long‑term off‑take contracts with specialist suppliers (premium for high‑purity) vs spot purchases from integrated producers? Use scenario NPV to compare cost of inventory, service level, and qualification risk for biotech customers.
-
Capex posture: Is de‑bottlenecking or selective debottleneck investment preferable to greenfield expansion? Our capex decision tree helps prioritize brownfield projects where permitting timelines and regulatory risk are lower.
-
Product strategy: Where to position portfolio — pursue certification and premium pricing for chromatography/biopharma grades, or double down on scale for commodity resin markets? The answer depends on your technical capability, access to feedstock, and tolerance for extended qualification cycles.
-
Commercial & pricing: Shift from cost‑plus to value‑based pricing in segments that prize low impurity and traceability. Negotiate clauses that allow feedstock cost pass‑throughs but cap downside risk in extended low‑price environments.
-
M&A and partnerships: Target bolt‑ons that add purification IP, analytical capability, or regional supply nodes rather than low‑value capacity. Recent asset transfers show premium for assets that secure local supply and IP.
-
Compliance & ESG: Build a regulatory roadmap and allocate contingency capital for emissions controls and handling upgrades — noncompliance could be more costly than proactive investment.
-
Monitoring & KPIs: Establish a compact dashboard (weekly feedstock price delta, supplier fill rate, grade‑specific inventory coverage, time‑to‑qualify for new grades, permit lead times).
How PW Consulting’s DVB study supports your 2026 decisions
The full report equips executives with the withheld granular segmentation by region, type, and application (available in the paid study), plus transaction‑ready tools that convert market intelligence into board‑level recommendations:
-
Supplier scorecards and comparative total cost of ownership (TCO) models;
-
Scenario‑based pricing and margin models that translate petrochemical price paths into producer and buyer economics;
-
Regulatory timelines aligned to capital planning, with cost estimates and mitigation options;
-
Deal playbooks for long‑term offtake contracts, JV structures, and acquisition target screening.
We intentionally present this executive trailer without the full regional and application splits: those datasets and the supporting spreadsheets are central to the licensed report and to bespoke advisory work targeted at specific investment or procurement choices.
Conclusion — the strategic value in 2026
For decision‑makers, DVB is more than a commodity monomer: it is a strategic lever in resin and specialty polymer value chains. Between feedstock volatility, rising regulatory costs, and an evolving competitive landscape, 2026 will be a year where the right mix of supplier strategy, selective investment, and product positioning creates outsized competitive advantage. PW Consulting’s DVB Market study transforms that complexity into operational choices — mapping which decisions move the needle and offering the analytic tools to execute them. To access the full segmentation tables, financial models, and supplier scorecards necessary for transaction‑level decisions, visit our report page or contact PW Consulting’s strategy team for a tailored briefing.
For detailed analysis of this topic, please visit the official page: Divinylbenzene (DVB) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Vinylidene Chloride Market Poised for 4.8% CAGR Through 2032
By pmarketresearch, 2026-07-13
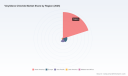
Vinylidene Chloride Market — Strategic Briefing for 2026 Decisions
Executive snapshot
As companies plan capital allocation and product strategy for 2026, understanding the vinylidene chloride (VDC) market’s macro trajectory and operational headwinds is essential. Our analysis at PW Consulting shows a market that has steadily expanded through 2020–2025 and is projected to continue growing across the 2026–2032 forecast window at a compound annual growth rate (CAGR) of approximately 4.8%. Using 2025 as the analytical base year, the market sits at roughly USD 250 Million (revenue unit: Million), and our forecast projects progressive growth through 2032 in nominal terms.
Vinylidene Chloride Market
Why this matters to executive decision-makers in 2026
-
Portfolio prioritization: Vinylidene chloride feeds high-barrier polymers, coatings and specialty intermediates. Even moderate annual growth can alter the ROI timeline for new capacity and downstream product launches.
Vinylidene Chloride Market -
Supply-chain resilience: The molecule’s production is sensitive to chlorinated feedstock dynamics and environmental compliance costs, making supplier selection and vertical integration decisions consequential.
Vinylidene Chloride Market -
Regulatory and operational risk: Stringent worker safety rules and environmental controls in major jurisdictions are driving capital expenditure and process redesigns that affect unit economics.
Market trajectory: the macro numbers you can’t ignore
Between 2020 and 2025 the market recorded steady growth, with a notable acceleration in the mid-decade years that left the sector poised for a multi-year recovery and expansion phase. From a base of about USD 195 Million in 2020, the market reached roughly USD 250 Million in 2025. Our 2026–2032 forecast—anchored to the 2025 base year—assumes a 4.8% CAGR, cumulatively compounding to materially higher nominal market value by 2032. This growth is underpinned by continuing demand for high-barrier packaging solutions and select industrial applications that require VDC-based chemistries.
Key market dynamics shaping 2026 strategy
-
Raw material and feedstock volatility: Regional swings in ethylene and ethylene dichloride pricing have a first-order effect on production cost for VDC. For example, supply tightness in North America drove a pronounced rise in certain feedstocks in late 2025, while Asia experienced price softening earlier in 2025 due to inventory build-up and dampened demand. These divergent trends create arbitrage opportunities but also raise the bar on risk management for buyers and producers.
-
Regulatory tightening and compliance CAPEX: Environmental regulation of chlorinated hydrocarbons and tightened occupational exposure limits (notably under U.S. OSHA frameworks) are increasing operating and compliance costs. Firms that proactively invest in lower-emission processes, monitoring systems and worker protection protocols will reduce regulatory tail risk but must balance that CAPEX against near-term margin pressure.
-
End-market shifts and product substitution risk: The dominant applications for VDC—high-barrier polymer systems and specialty intermediates—face substitution pressure from alternative barrier technologies and formulation innovations. Understanding where VDC offers an enduring technical advantage (e.g., ultra-high barrier film requirements, certain pharmaceutical packaging) is a prerequisite to defensible investment.
-
Inventory and demand cyclicality: The market’s short-cycle inventory behavior in key manufacturing hubs induces pricing volatility. Tactical procurement strategies and agile tolling/contracting models can protect margins during demand troughs and enable rapid upside capture in recoveries.
Competitive landscape — who matters and why
The VDC industry is a mix of global majors and regional specialist producers. Market presence is concentrated enough that actions by a few large firms can materially influence supply balances and pricing. Broadly, top producers combine scale production assets, downstream integration into PVDC and coatings, and geographic footprints that span mature and emerging demand centers. Examples of prominent players include:
-
Dow Inc. (United States) — Integrated production footprint with recent capacity moves aimed at meeting rising demand for high-performance polymers. (Source: Dow recent development, Jan 2026)
-
Kureha Corporation (Japan) — Specialist in PVDC resins and high-barrier film solutions, leveraging proprietary resin technologies for premium packaging applications.
-
Asahi Kasei Corporation (Japan) — Focused on emulsion polymerization routes and applications that span medical and packaging coatings.
-
Solvay S.A. (Belgium) — Strong in pharmaceutical-grade barriers and coating systems, with an active stance on regulatory compliance and sustainability in chlorinated chemistries.
-
Chinese producers (several regional firms) — Provide capacity for bulk PVDC intermediates and emulsions that serve fast-moving consumer goods and industrial markets in Asia.
These producers display differentiated strategies: some compete on scale and integration, others on niche resin science or customer intimacy in specialized applications. Importantly, capacity expansions by a major player (the January 2026 expansion by Dow in Texas) show how a single investment can influence regional supply balances and pricing dynamics across the chain.
What the full PW Consulting report delivers — operationally focused
Our full market study moves beyond high-level narrative to provide practical decision support for 2026 planning cycles. Key deliverables include:
-
A validated market-sizing model (base year 2025) with scenario-driven forecasts across 2026–2032. The model is built for sensitivity testing against feedstock costs, regulatory scenarios, and demand shocks.
-
Risk-adjusted investment appraisal templates that translate forecast volatility into NPV and payback ranges for greenfield and brownfield options.
-
Supply-chain stress tests and procurement playbooks that specify hedging, tolling and strategic inventory hedges for both buyers and sellers.
-
Commercial playbooks for downstream differentiation, identifying where VDC-based solutions deliver defensible value versus competing barrier technologies.
-
A competitive intelligence dossier on leading producers, with capability maps, recent capacity moves, and likely strategic responses under alternative demand scenarios.
Note: to preserve commercial sensitivity and to drive actionable engagements, this introductory briefing intentionally omits the granular regional and application-level allocation tables that appear in the full report. Those tables are available in the complete deliverable and are essential for transaction-level decisions.
Strategic implications and recommended actions for 2026
-
Re-evaluate capacity timing vs. demand certainty: With a mid-single-digit CAGR projected for the medium term, aggressive greenfield commitments should be stress-tested under downside scenarios. Consider phased or modular capacity options and tolling partnerships to retain optionality.
-
Lock in feedstock advantage where possible: Vertical integration or long-term feedstock contracts can insulate margins from the feedstock swings observed across regions. Pricing arbitrage in 2025–2026 illustrates how regional feedstock moves can flip competitiveness.
-
Prioritize regulatory-forward investments: Early investment in emissions control and worker safety systems reduces regulatory disruption risk and preserves access to premium customers (e.g., pharmaceutical packaging buyers demanding stringent compliance).
-
Differentiate through formulation and value-added services: Suppliers that pair VDC supply with polymer science, coating expertise, or application engineering will command superior commercial terms compared with undifferentiated commodity supply.
-
Adopt dynamic contracting models: Use a mix of short and medium-term contracts, indexation clauses linked to feedstock costs, and performance-based tolling to manage volatility exposure.
How to use this intelligence in the C-suite and for investor committees
For CEOs and CFOs, the focus is on calibrating capital deployment to a market that is growing, but exposed to feedstock and regulatory variability. For commercial leaders, the task is to sharpen value propositions where VDC’s barrier properties are non-substitutable. For procurement and operations, instituting flexible contracting and investing in compliance provides downside protection.
Closing — what we recommend next
Vinylidene chloride is not a mass-commodity where scale alone wins; it is a specialty intermediate whose market outcomes are determined by feedstock economics, regulatory posture, and downstream performance differentiation. PW Consulting’s full report contains the granular, transaction-ready data tables, regional and application breakdowns, and scenario models required to make 2026-capex and commercial decisions with confidence. This briefing reveals the strategic contours; the full study provides the operational map.
To unlock the complete dataset, scenario models, and supplier-level assessments that underpin these executive recommendations, request the full PW Consulting Vinylidene Chloride Market report and accompanying decision toolkits.
For detailed analysis of this topic, please visit the official page: Vinylidene Chloride Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
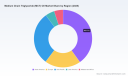
Medium Chain Triglyceride (MCT) Oil: A 2026 Strategic Brief for Commercial Leaders
As PW Consulting’s lead industry analyst, I present a high‑signal briefing for commercial leaders preparing strategic moves in 2026 across nutrition, pharmaceutical, personal care and specialty chemical value chains. This piece distills the practical implications of our full MCT Oil Market study — which benchmarks historical performance (2020–2025), validates near‑term supply dynamics and provides a 2026–2032 forecast — into the decisions that matter next year. The full report contains the granular segmentation, price models and supplier scorecards you will need to execute with confidence; this article is a focused trailer intended to surface critical strategy levers while preserving the proprietary split data that drive operational choices.
Medium Chain Triglyceride (MCT) Oil Market
Market at a Glance: What the Top‑Line Means for 2026
The MCT oil market has expanded materially through the early 2020s, reaching an estimated USD 890 million in 2025 following consistent year‑over‑year growth. Our forecast models — rooted in demand drivers across supplements, food & beverage formulation, topical and pharmaceutical applications — project sustained expansion at a compound annual growth rate (CAGR) of roughly 8.5% over the 2026–2032 horizon, reaching approximately USD 1.56 billion by 2032. That trajectory is neither speculative nor uniform: it is the aggregate expression of evolving ingredient preferences, regulatory tightening on raw material origins, and differentiated commercialisation pace by end‑market.
Medium Chain Triglyceride (MCT) Oil Market
Two immediate strategic implications for 2026:
Medium Chain Triglyceride (MCT) Oil Market
- Scale and speed matter: companies that can align procurement, certification and manufacturing scale by H2 2026 will capture disproportionate share of incremental demand.
- Margin arbitrage will shift toward differentiated products (pharma‑grade, organic, powder formats and verified sustainable sources), creating a premium segment that rewards investment in quality controls and traceability.
What the Full Study Delivers — Practical Outputs for Executives
Our full PW Consulting MCT study is built to convert market intelligence into executable programs. Highlights of the operational deliverables included:
- Demand and revenue forecasting engine (2026–2032) with scenario toggles for substitution rates, end‑market penetration and regulatory shock.
- Supply‑chain heatmaps and tiered supplier risk scoring that combine raw material origin, manufacturing technology (esterification vs. direct distillation), certification profile (RSPO, organic, GMP) and logistics constraints.
- Price elasticity and pass‑through models to set commercial pricing and promo strategies across channel and formulation types.
- CapEx/Opex templates for brownfield/greenfield MCT capacity expansion and contract manufacturing options with NPV and payback analysis under multiple demand cases.
- A regulatory matrix mapping USP/BP/EP pharmacopeia requirements, import controls, and emerging sustainability disclosure regimes relevant to 2026 product claims.
- Competitive playbooks and M&A target shortlists, including valuation heuristics and integration checklists for bolt‑on acquisitions of specialty oil processors.
These elements are designed to be portable into 2026 planning cycles: procurement S&OP, product roadmaps, and board presentations.
Competitive Landscape: Strategic Profiles and Tactical Takeaways
The MCT ecosystem blends global chemical majors, oleochemical specialists, and focused specialty oil producers. Market concentration metrics show a moderately fragmented structure, with top players holding substantial but not dominant combined shares — a dynamic that supports both scale plays and nimble differentiation.
- Abitec Corporation (Columbus, Ohio) — Strength: deep expertise in functional lipids and niche formulations. Strategic takeaway: an attractive partner for co‑development of value‑added ingredients where formulation expertise and small‑batch flexibility are required.
- BASF SE (Ludwigshafen) — Strength: global supply chain, regulatory depth and scale R&D. Strategic takeaway: best positioned for large customers seeking product stewardship and integrated ingredient platforms; expect competitive pricing on standard grades but less flexibility on bespoke supply terms.
- Croda International Plc (Warrington) — Strength: high‑purity, pharma/dermal MCT products and brand recognition in specialty markets. Strategic takeaway: premium positioning makes Croda a go‑to for topical and pharmaceutical customers prioritizing purity and regulatory traceability.
- IOI Oleo GmbH (Wittenberge) — Strength: European production and established brands via esterification/distillation expertise. Strategic takeaway: strong contender for regional food and supplement OEMs; watch for capacity moves to manage European sustainability scrutiny.
- Musim Mas Holdings (Singapore) — Strength: integrated palm oil value chain and sustainability initiatives. Strategic takeaway: rapid re‑certification and product updates signal focus on premium sustainable supply to retain access to sensitive markets.
- Bioriginal Food & Science (Saskatoon) — Strength: flexible formats (bulk, organic, powder) and supplier for functional food makers. Strategic takeaway: valuable as a contract supplier for brands seeking formulation innovation or organic claims.
- Natura Aeropack (Philippines) — Strength: coconut‑derived focus with multiple certifications (ISO, US‑FDA, Kosher, Halal). Strategic takeaway: efficient route to compliant coconut MCT for global supplement channels; regional logistics considerations apply.
- Stepan Company (Northfield, Illinois) — Strength: branded caprylic/capric triglyceride product line and allergen‑free positioning. Strategic takeaway: likely first choice for food‑grade and bio‑based applications where allergen and label risk are critical.
Recent market developments to watch in 2026:
- Musim Mas updated product catalogues in 2025 with enhanced sustainability credentials — a signal of rising buyer expectations for verified supply chains.
- Wilmar’s Southeast Asia production site development (in partnership with Nisshin OilliO) underscores regional supply optimisation trends; buyers should reassess lead‑times and landed cost assumptions in 2026.
- Lonza’s 2025 launch of pharmaceutical‑grade MCT formulations intensifies competition in the drug‑delivery segment and raises the bar on pharmacopeia compliance for new entrants.
Structural Dynamics Shaping 2026 Strategy
Several structural forces will materially affect 2026 decisioning:
- Raw material provenance: Palm kernel and coconut oils remain the primary feedstocks. The source mix drives both ESG exposure and cost volatility — a central procurement variable for 2026 contracts.
- Certification & regulation: RSPO, GMP/ISO and pharmacopeia standards (USP/BP/EP) are gating factors for many commercial pathways. Certification lead‑times often exceed 6–12 months and should be factored into product launch timelines.
- Manufacturing complexity & labor: Specialized distillation and esterification require skilled operators and automated controls, leading to higher operational labor intensity and capex per tonne vs. commodity oils.
- Geopolitics & market access: Export restrictions and sustainability policies in certain markets create demand displacement and create arbitrage opportunities for compliant producers in other regions.
Actionable 2026 Playbook — Priorities for CEOs and Commercial Heads
Translate market momentum into durable advantage with a focused set of moves to execute in 2026:
- Lock certified supply now: Negotiate multi‑year offtake or strategic alliances with suppliers that hold the certifications your end‑market customers will insist upon in 2026. Factor in onboarding lead times for new certs.
- Differentiate beyond commodity grades: Invest in productization (pharma‑grade, microencapsulated powder formats, organic or traceable origin labels) to capture margin expansion as base market commoditisation intensifies.
- Reassess footprint and logistics: Model alternative sourcing scenarios (e.g., Southeast Asia expanded capacity vs. regional European supply) to optimise landed cost and reduce single‑point risks.
- Embed regulatory and ESG guardrails: Start 2026 projects with a regulatory matrix and sustainability due diligence as compulsory gates in the product development lifecycle.
- Pursue targeted M&A or JV play: Consider bolt‑on acquisitions for technical distillation expertise or to secure certified feedstock. Use our M&A scorecard in the full report to prioritise targets by integration risk and payback horizon.
- Price & promotion discipline: Implement price models that capture formulation uplift and account for certification premiums; avoid race‑to‑the‑bottom tactics in high‑growth segments.
- Operationalise scenario planning: Run stress tests for raw material shocks, regulatory closures, and rapid demand surges using the report’s scenario engine to validate capacity and working capital plans.
Why This Matters for 2026 Decisions
The combination of strong top‑line growth (the market expanding to an expected USD ~1.56 billion by 2032 at ~8.5% CAGR), shifting buyer preferences toward certified and specialty grades, and evolving regulatory pressure means that 2026 will be a year of bifurcation: organisations that move early to secure compliant, transparent supply and to productise MCT into higher‑value formats will lock in sustainable margins; those that treat MCT as a commodity risk margin compression and supply outages.
Our study is intentionally operational: it not only forecasts demand but provides the analytic scaffolding — supplier maps, price pass‑through mechanics, certification timelines and acquisition heuristics — to convert the forecast into executable plans over the 2026 planning cycle.
Next Steps — How to Access the Full Intelligence
This article is a strategic trailer. The full PW Consulting MCT Oil Market report contains the granular segmentation tables, regional and application slices, supplier scorecards and a downloadable financial model that underpin the recommendations above. For procurement RFPs, product development roadmaps, or M&A diligence in 2026, that level of granularity is required.
Contact our team to arrange an executive briefing, obtain the full dataset and license the forecast engine — we’ll walk you through bespoke scenarios tuned to your supply, customer and regulatory footprint so you can finalise a 2026 playbook with confidence.
For detailed analysis of this topic, please visit the official page: Medium Chain Triglyceride (MCT) Oil Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Swimming Pool Treatment Chemicals Market to Grow at 4.7% CAGR (2026-2032)
By pmarketresearch, 2026-07-13
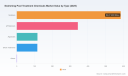
Swimming Pool Treatment Chemicals Market — Strategic Preview for 2026 Decision-Makers
PW Consulting’s latest market study (base year 2025; forecast period 2026–2032) offers a focused, decision-grade synthesis of the Swimming Pool Treatment Chemicals market. At a macro level this sector has expanded from roughly USD 1,000 Million in 2020 to an estimated USD 1,162.17 Million in 2025, and is projected to grow to about USD 1,602.86 Million by 2032 — a compound annual growth rate (CAGR) of 4.7% across the forecast window. This preview highlights the strategic implications of those trends for corporate planning in 2026 while intentionally withholding detailed subsegment tables and region/application splits to encourage access to our full intelligence package.
Swimming Pool Treatment Chemicals Market
Why this study matters for 2026 corporate strategy
-
Timing and prioritization: The market’s steady mid-single-digit CAGR signals predictable top-line expansion, but uneven cost and regulatory shocks make timing of capex, procurement, and pricing moves decisive in 2026. Companies that align investment cadence to the market’s growth slope — rather than to short-lived seasonal spikes — will preserve margins and capture share.
Swimming Pool Treatment Chemicals Market -
Risk-adjusted sourcing: Raw material volatility and tariff-driven input-cost inflation require playbooks for hedging and supplier diversification. The report translates headline market growth into practical procurement risk metrics executives can use at Q2–Q3 2026 planning cycles.
Swimming Pool Treatment Chemicals Market -
Portfolio and channel optimization: As demand shifts between end-use profiles (e.g., residential vs. commercial) and as sustainability-focused products gain traction, manufacturers and distributors must re-weight SKUs and commercial tactics. Our study converts aggregate growth into actionable portfolio scenarios for premiumization, value-line retention, and channel mix adjustments.
Key dynamics shaping 2026 outcomes
-
Trade and tariff shocks: Multiple tariff actions announced or in force through 2025 have altered the cost base for imported raw materials and finished chemicals. These measures materially affect procurement economics and have driven tactical behaviors (e.g., advance buying, inventory build) by large distributors. Expect continued short-term dislocations and higher working-capital needs into 2026.
-
Raw material tightness and formulation economics: Specific intermediates used in pool chemistry experienced supply tightening and price pressure in late 2025. Even modest percentage increases in key inputs can compress margins for producers that cannot redesign formulations or achieve cost pass-throughs rapidly.
-
Sustainability and formulation innovation: Leading suppliers are introducing biodegradable and efficiency-enhancing platforms that reduce active-ingredient consumption. These technology moves will reframe product differentiation over the next 18–36 months and create new margin pools for early adopters.
-
Channel behavior and inventory strategies: Distributors and reseller networks have been actively managing inventories to hedge against vendor cost increases and seasonal demand. Expect continued emphasis on inventory-to-sales management, dynamic pricing levers, and promotional cadence adjustments throughout 2026.
Competitive landscape — a pragmatic synthesis
The market exhibits moderate concentration: the top three and top five players control a meaningful but not dominant share, indicating room for both scale-driven leaders and specialized challengers. The competitive set includes integrated chemical manufacturers, specialized pool-chem producers, and broad-based distributors. Each category has different strategic imperatives.
-
Integrated chemical manufacturers (e.g., firms with broad specialty-chemical portfolios) can capture margin via upstream integration, formulation intellectual property, and cross-selling into adjacent water-treatment markets. Their investment priorities often center on R&D for formulation efficiency and regulatory compliance.
-
Specialized pool-chem producers focus on brand equity, product reliability, and targeted product innovation (e.g., biodegradable lines). They are most sensitive to raw-material cost swings and need flexible sourcing strategies to protect margins.
-
Distributors and supply-chain specialists play a critical role in market access and service delivery. Recent behavior among these players — including inventory accumulation ahead of vendor price increases — signals aggressive margin-protection tactics and the strategic use of stock as a competitive lever.
Representative companies illustrate these strategic archetypes. Large consumer-chemical brands are introducing sustainability-focused product lines to capture eco-conscious end-users. Global specialty-chemical players are deploying technology platforms to reduce active-chlorine consumption. Distributors are optimizing logistics and pricing to offset rising input costs. Each of these moves re-orders opportunities across the value chain.
Recent, high-impact developments you should factor into 2026 planning
-
Inventory-led defensive tactics by distributors — including advance purchasing to offset supplier price increases — have already affected working capital and gross margin profiles in late 2025 and early 2026.
-
New product introductions focused on biodegradability and formulation efficiency are accelerating the premiumization of parts of the portfolio and creating new marketing and certification requirements.
-
Regulatory rulings and tariff schedules enacted through 2025 create an elevated baseline for input costs; companies that do not model multi-scenario tariff impacts in 2026 will underprice risk in procurement and contracts.
What the PW Consulting report delivers (practical, actionable content)
-
Robust macro forecast and scenarios: multi-horizon revenue projections (2026–2032) under base, upside, and downside cases calibrated to tariff, raw-material, and adoption risk factors.
-
Procurement and margin playbooks: supplier scorecards, hedging strategies, and short/medium-term working-capital recommendations tailored to manufacturer and distributor profiles.
-
Product and R&D prioritization matrices: a decision framework that ranks formulation and sustainability investments by ROI, technical feasibility, and regulatory risk.
-
Go-to-market and pricing playbooks: actionable approaches for premiumization, trade promotions, dynamic pricing, and channel-specific assortment optimization.
-
Competitive dossiers: strategic profiles of major players, mapped capabilities, recent moves, and potential M&A or partnership targets. (Note: detailed subsegment shares, per-region application splits, and line-item pricing are reserved for the full report.)
-
Regulatory and raw-material trackers: near-real-time monitoring templates for tariff schedules, trade rulings, and critical-input price swings to feed into quarterly planning cycles.
Recommended decision actions for 2026 (executive checklist)
-
Reconcile portfolio against margin corridors: identify SKUs that are margin-sensitive to input-cost swings and prioritize reformulation or price protection strategies for those items.
-
Adopt a dual-track procurement strategy: combine near-term forward buying on key inputs with medium-term supplier diversification and local-sourcing pilots to reduce tariff exposure.
-
Accelerate sustainability-led differentiation where it aligns with premium channel economics; fast followers risk margin compression as early movers capture brand advantage.
-
Deploy dynamic pricing playbooks in commercial channels to preserve margins during input-cost cycles, while protecting acceptance in residential retail through value communication.
-
Embed scenario-based tariff modelling into quarterly financial forecasts — update product-level price elasticity assumptions and pass-through timelines.
-
Explore distribution partnerships and inventory-financing solutions to manage working-capital strain induced by strategic pre-purchasing behavior in the channel.
How PW Consulting can accelerate your 2026 execution
Our full report pairs the macro intelligence above with granular, transaction-ready analysis: subsegment performance tables, region-and-application breakouts, supplier-by-supplier risk scores, and customized scenario models you can plug into budgeting and procurement systems. For teams evaluating M&A targets or planning product launches in 2026, we offer tailored workshops, unit-cost modelling, and go-to-market sprint support.
This preview demonstrates the kind of strategic depth PW Consulting provides while preserving the most commercially sensitive subsegment detail for subscribers. To convert the macro momentum into defensible, actionable plans in 2026, senior teams should prioritize accessing the full report and arranging a strategy alignment session with our industry specialists.
For detailed analysis of this topic, please visit the official page: Swimming Pool Treatment Chemicals Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com