

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Decorative HPL Market Eyes 5.5% CAGR to USD 18.04 Billion by 2032

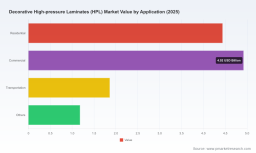
Decorative High-pressure Laminates (HPL) Market — Strategic Briefing for 2026 Decisions
Executive summary
As companies map growth and resilience plans for 2026, the decorative High-pressure Laminates (HPL) sector presents a clear, mid-cycle expansion opportunity underpinned by steady demand and structural change. Our PW Consulting market study — anchored on a 2025 base year and a seven-year forecast horizon to 2032 — projects the global decorative HPL market to expand at a compound annual growth rate (CAGR) of approximately 5.5%. From a commercial standpoint, the market reached a meaningful scale in 2025 and is projected to grow further through 2032, driven by product innovation, substitution dynamics in interior finishes, and regulatory-driven reformulation in supply chains.
Decorative High-pressure Laminates (HPL) Market
Why this study matters to executive teams in 2026
-
Timing for investment: The combination of predictable growth and evolving regulatory thresholds creates windows for capacity upgrades, product repositioning, and selective M&A that can lock in margin expansion before raw material normalization.
Decorative High-pressure Laminates (HPL) Market -
Portfolio resilience: Manufacturers and distributors must reconcile short-term feedstock volatility with long-term demand trends — the report translates those tensions into actionable product- and channel-level playbooks.
Decorative High-pressure Laminates (HPL) Market -
Regulatory preparedness: New emissions limits and certification expectations are not hypothetical — they affect formulations, capital equipment, and route-to-market approvals. Firms that internalize compliance costs and leverage early certification as a commercial differentiator will capture premium placement in spec-driven segments.
High-level market trajectory (what we reveal)
Using five years of historical data (2020–2025) and our scenario-driven modelling through 2032, PW Consulting identifies a structurally growing market. The baseline forecast reflects steady construction and refurbishment activity, continued product migration into higher-value niche grades, and an incremental premium for sustainability-certified laminates. While we intentionally withhold granular regional/application breakdowns here to preserve the executive value of the full report, readers should note the market is neither hyper-fragmented nor monopolized — concentration metrics indicate leading suppliers maintain material commercial influence, but meaningful space exists for regional specialists and innovative entrants.
Key demand and supply dynamics shaping 2026 strategy
-
Substitution and specification shifts: End-users continue to move away from raw timber and lower-performing decorative alternatives in key commercial and residential specifications, boosting the appeal of higher-durability HPL grades. This creates opportunities for premiumization, differentiated finishes, and value-added surface systems.
-
Raw material pressure and formulation choices: Melamine-formaldehyde systems account for the dominant share of resin usage in decorative HPL manufacturing. Recent feedstock volatility — including a supply disruption episode in India linked to methanol-driven formaldehyde price spikes — underscores the need for strategic resin sourcing, hedging strategies, and R&D into low-emission variants.
-
Regulatory tightening as a market force: From the U.S. regulatory environment to forthcoming EU directives, emission standards and low-VOC expectations are recalibrating production norms. Notably, new EU REACH limits coming into effect in 2026 will impose a stricter formaldehyde emissions ceiling for wood-based products, while U.S. frameworks similarly compel adoption of low-emission melamine-formaldehyde variants. These rules will reprice compliance and accelerate reformulation for manufacturers that supply specification-sensitive channels.
-
Sustainability and certification premiums: Buyers — particularly architects, institutional purchasers, and major retailers — are applying certification filters with increased weight. Recent manufacturer certifications and biobased labeling efforts demonstrate the commercial upside to proactive sustainability programs.
Competitive landscape — what to watch (we reveal strategic posture, not confidential metrics)
The decorative HPL industry is anchored by recognizable global brands with diversified portfolios across residential, commercial, and specialty applications. The competitive fabric features legacy laminators with extensive design libraries, European premium innovators, and nimble regional champions. Competitive strength is driven by design capability, distribution reach, sustainability credentials, and the ability to support specification-driven projects.
-
Formica Group — A long-established leader that combines brand recognition with R&D scale. Recent moves to secure bio-based product labeling illustrate a dual focus on sustainability and specification advantage for interiors projects seeking certified materials.
-
Wilsonart LLC — Known for a broad surfaces portfolio and accelerating sustainable product lines. Wilsonart’s recent launch of extended design ranges underscores a go-to-market strategy that pairs aesthetic breadth with low-emission options.
-
EGGER Group — A European player emphasizing multi-layer abrasion resistance and furniture-sector integration; its product approach favors system sales with board and surface combinations.
-
Greenlam Industries — A major global supplier with a strong presence in Asia and an aggressive new-market product roll-out cadence. Regional catalog refreshes demonstrate a strategy to capture architectural trends and local specification needs.
-
Fundermax and Trespa — Specialists that target high-performance and exterior architectural niches; their product leadership is often linked to differentiated material properties such as hygiene, UV resistance, and facade suitability.
-
Pfleiderer, Abet Laminati, Arpa Industriale, Panolam — European and U.S. firms complement the landscape with design-forward and certification-led offerings that appeal to premium buyers and project specifiers.
Recent company-level developments illustrate where competitive advantage is being pursued: certification and biobased labeling, expanded design collections, new texture and woodgrain launches, and localized product introductions targeting growth corridors. These tactical moves are signals: specification-driven markets will increasingly reward certified, differentiated designs backed by reliable supply chains.
What the PW Consulting report delivers (practical content for 2026 action)
Our full study is structured to convert market intelligence into executable decisions. Core deliverables include:
-
Market sizing and base-case/alternative scenario forecasts (2026–2032) with sensitivity to raw material swings and regulatory shocks.
-
Segment-level insights (by grade, application, and region) mapped to distribution channels and procurement cycles — note: detailed segment tables are available in the full report.
-
Competitive benchmarking with capability matrices, recent strategic moves, and supplier SWOTs tuned to tactical responses for price, innovation, and sustainability competition.
-
Supply-chain mapping and risk heatmaps highlighting resin exposure, substitute pathways, and mitigation levers (e.g., alternative chemistries, vertical integration, or contractual hedges).
-
Regulatory impact assessment, including cost-to-compliance modelling for new emission thresholds and certification roadmaps that translate compliance into commercial differentiation.
-
Commercial and product playbooks: SKU rationalization guidance, premiumization pathways, channel strategies (distribution vs. direct spec sales), and pricing elasticity models.
-
M&A and partnership screening framework highlighting target archetypes, valuation considerations under feedstock volatility, and integration checklists focused on technology and certification assets.
-
Implementation timelines and a one-year quick-win plan for 2026 that includes low-cost certification moves, targeted design launches, and tactical inventory positioning to weather feedstock cycles.
Strategic recommendations for 2026
-
Prioritize compliance-led product repositioning: Treat upcoming regulatory thresholds as a product-management opportunity, not just a cost. Fast-tracked certification and transparent emissions data will unlock specification channels.
-
Diversify resin sourcing and invest in formulation R&D to reduce exposure to single-feedstock price shocks. Where feasible, evaluate partnerships with resin suppliers to secure preferential terms or co-develop low-emission systems.
-
Leverage design and sustainability credentials to pursue premiumization in institutional and commercial projects. Designers and architects are early adopters of certified materials; align marketing and specification support accordingly.
-
Use targeted M&A to acquire capability (e.g., compact HPL, specialty exterior grades, or certification-focused technologies) rather than scale alone — given the current concentration dynamics, capability gaps are a faster route to differentiation.
-
Prepare inventory and pricing playbooks for intermittent feedstock disruption: scenario-test margin sensitivity and agree on contingency pricing clauses with key customers in long-lead spec markets.
Conclusion and next steps
The decorative HPL market entering 2026 is predictable enough to plan against, yet dynamic enough that early strategic moves will matter. Our study equips executives with the foresight to balance near-term operational resilience with longer-term brand and product-led differentiation. For procurement leaders, R&D chiefs, and corporate strategists, the decision levers this year will determine who converts regulatory and raw material headwinds into durable commercial advantage.
Accessing the full intelligence
This briefing intentionally foregrounds the strategic implications while holding back detailed segment tables, regional splits, and granular pricing scenarios that constitute the core proprietary value of the full PW Consulting report. To obtain the complete dataset, segment-level forecasts, and executable playbooks for 2026–2032, please consult our report landing page or contact our advisory team to schedule a bespoke briefing tailored to your company’s priorities.
For detailed analysis of this topic, please visit the official page: Decorative High-pressure Laminates (HPL) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com