

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Hydrogen Sulfide Removal Market — USD 2,290M in 2025, 5.5% CAGR to 2032

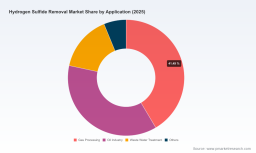
Hydrogen Sulfide Removal Market — Strategic Outlook to 2032 (PW Consulting Preview)
Hydrogen sulfide (H2S) remains one of the most persistent operational, environmental and regulatory challenges across gas processing, produced-water handling, biogas upgrading and downstream refining. PW Consulting’s new market study — built on a 2025 base year with a historical review covering 2020–2025 and a detailed forecast to 2032 — quantifies the sector’s trajectory and translates it into decision-grade recommendations for executives planning capital allocation, technology selection and M&A priorities in 2026.
Hydrogen Sulfide Removal Market
Why the 2026 decision window is decisive
2026 is a strategic inflection point. Our analysis shows the global H2S removal market expanding at a steady compound annual growth rate (CAGR) of 5.5% across the 2026–2032 forecast horizon. On a macro scale, the addressable market rises materially from the 2025 base to reach the low‑thousands of USD Million by 2032, driven by a mix of regulatory tightening, upstream production chemistry, and growth in distributed biogas and wastewater projects.
Hydrogen Sulfide Removal Market
For boardrooms preparing 3‑ to 7‑year investment plans, the implications are clear: near‑term choices on technology platforms, service models and field validation will disproportionately determine competitive positioning across the decade.
Hydrogen Sulfide Removal Market
Market dynamics and growth drivers
- Regulatory tightening and exposure risk: Recent regulatory activity — including U.S. EPA NESHAP limits for fuel gas, OSHA ceiling and peak exposure limits, and sub‑10 ppm discharge expectations under major industrial emissions frameworks — is raising the cost of noncompliance and elevating demand for robust H2S control solutions. Local advisory thresholds for community monitoring in some jurisdictions further increase reputational and permitting risk for operators.
- Energy mix transition and feedstock diversity: Growth in biogas, landfill gas and produced water treatment projects expands the range of source streams with variable H2S loads. Distributed applications favor compact, low‑waste solutions and providers that can package media, controls and service into an operational contract.
- Cost of ownership focus: Buyers are shifting emphasis from capex alone to total cost of ownership — chemistry consumption, media life, waste generation and onsite service frequency. This trend is accelerating adoption of regenerative systems and solutions that minimize solid waste streams.
- Decentralization and modular deployment: Remote gas and onsite wastewater facilities require modular systems with predictable performance. Standardized skid packages, pre‑commissioning and remote monitoring are now procurement expectations in many project tenders.
- Technology convergence and digitalization: Sensors, process analytics and IIoT-enabled service models are enabling performance‑based contracts and predictive maintenance, placing a premium on vendors that combine chemical or adsorbent IP with data services.
Regulatory guardrails shaping procurement and risk
- U.S. EPA NESHAP: fuel gas systems constrained to specified ppm levels for H2S.
- OSHA: a 20 ppm ceiling (with higher short‑term peak limits) for worker exposure that drives the need for reliable scrubbing in personnel access areas.
- Cross‑jurisdictional expectations: both North American and European industrial emissions frameworks are enforcing sub‑10 ppm discharge thresholds in many permitting cases, raising the bar for end‑of‑pipe solutions.
- Local advisory standards for community monitoring are increasingly influencing project siting and operational controls in urban‑adjacent facilities.
Technology and commercial dynamics — what distinguishes winners
The H2S removal market remains technologically varied. Commercial differentiation arises along three dimensions: chemistry/media approach (liquid redox, triazine scavengers, iron‑based adsorbents, mixed metal oxides), lifecycle waste profile (regenerative vs non‑regenerative), and service/digital overlay.
- Regenerative systems: These solutions offer lower recurring media cost and reduced solid waste but typically require greater process integration and O&M capability. They are attractive for high‑volume streams where media regeneration economics pay back.
- Non‑regenerative/scavenger approaches: Simpler to deploy and attractive for small or intermittent streams, but buyers must account for recurring chemical purchases and waste handling constraints.
- Adsorbents and mixed metal oxides: Robust in high‑throughput gas units; lifecycle and replacement cadence are key procurement variables.
- Service and data: The fastest‑growing commercial models pair chemistry or media with service contracts and remote performance guarantees. These reduce operator staffing exposure and shift lifecycle risk to vendors.
PW Consulting’s analysis highlights that commercial outcomes are determined less by a single “best” technology and more by fit‑for‑service: fluid composition, duty cycle, regulatory load‑out, waste handling constraints, and the buyer’s appetite for operational outsourcing.
Competitive landscape — capabilities to map to strategy
The H2S removal vendor set spans specialist chemists, integrated oilfield service firms, and system integrators. Market concentration is modest: the top three suppliers account for roughly a quarter of market revenue, and the top five for about thirty percent, indicating a fragmented field with room for consolidation and niche dominance.
- Merichem Technologies (Houston): Deep experience in liquid redox (LO‑CAT), proprietary adsorbents and engineered vessel systems for gas, biogas and petrochemical streams. Recent field evidence in 2026 shows a commercial step‑change: a June 2026 field trial in a major Permian play reportedly delivered sustained >99% removal from separator gas with no solid waste — a variant that directly addresses lifecycle disposal pressures.
- SLB / Schlumberger (Houston): Brings iron oxide and mixed metal oxide adsorbent portfolios, plus global field service capability. As an oilfield service incumbent, SLB offers scale for large upstream rollouts and integrated production chemistries.
- Streamline Innovations (USA): Focused on liquid redox variants optimized for produced water and high‑H2S streams. A March 2026 case study documented multi‑million‑dollar monthly chemical savings at a high‑H2S produced water facility—evidence of substantial OPEX impact when systems are matched correctly to field conditions.
- FirstKlaz Technologies (USA): Specialist in triazine scavengers, FeO adsorbents and Claus recovery interfaces — a profile that suits operators seeking turnkey sulfur recovery integration.
- Unison Solutions (Dubuque) & MV Technologies (USA): Niche leaders in biogas and landfill gas media, offering iron‑based and carbon systems designed for decentralized, wastewater and agricultural applications.
Across providers, competitive advantage is driven by demonstrable lifecycle economics, warranties tied to performance, and the ability to scale pilot results to multi‑site deployments.
Recent development highlights that shift competitive dynamics
- June 2026 — Merichem announces field trial success for a new ECOTREAT process achieving sustained >99% H2S removal from separator gas without generating solid waste; the vendor is moving to commercial rollout.
- March 2026 — Streamline Innovations publishes a case study showing its ThunderOx system delivered significant chemical OPEX savings at a high‑H2S produced water operation, validating the business case for liquid redox in comparable sites.
What PW Consulting’s full report delivers — operationally actionable insight
This preview is intentionally high‑level. The full PW Consulting study provides the granular, executable intelligence that procurement, operations and corporate development teams need to act in 2026:
- Market sizing and scenario models: base‑case and sensitivity runs across conservative, modal and aggressive adoption pathways (2026–2032), with downloadable model files for in‑house stress testing.
- Vendor benchmark matrix: technology, lifecycle cost modeling, demonstrated field performance, service footprints and contract archetypes to build shortlists matched to buyer archetypes.
- Commercial playbooks: procurement specs, RFP templates, trial design guides and standard KPIs for pilot validation that de‑risk rollouts and shorten procurement cycles.
- Regulatory and permitting matrix: cross‑jurisdictional thresholds, monitoring requirements and compliance timelines that affect both capex sizing and operational O&M regimes.
- M&A and partnership lens: target screening criteria, valuation multiples observed in recent deals, integration risks and recommended diligence checklists for chemistry, IP and service contracts.
- Case studies and unit‑level economics: anonymized, audited project examples that surface true OPEX drivers, replacement cadence and waste handling costs underpinning payback calculations.
How to use this preview to frame your 2026 agenda
- Immediate actions for operators: prioritize pilot programs for high‑exposure streams where regulatory thresholds or worker safety create the highest near‑term risk; require vendors to model total lifecycle cost and to accept contracted performance guarantees.
- For vendors and investors: evaluate technologies not only on removal efficiency but on waste profile, serviceability and data productization; consider consolidation targets where distributive service networks can be leveraged to scale digital, performance‑based contracts.
- For corporate development teams: use 2026 to validate assumptions on media lifespan and operational intensity; close small strategic acquisitions that fill geography or service gaps before competitors scale integrated offerings.
Next steps — where the full findings add value
This preview signals where the market is moving and why 2026 planning cycles should integrate H2S removal strategy into capex, OPEX and compliance programs. The full PW Consulting report provides the data tables, segmentation breakdowns, vendor scorecards and model files you will need to translate this strategic view into executable projects. Detailed regional and application splits, technology adoption curves by use case, and vendor market shares are reserved for the full report — essential inputs for procurement specification, pilot budgeting and M&A underwriting.
Contact PW Consulting to access the complete study, the interactive forecast model and our advisory services to convert the forecast into a 2026‑ready roadmap for your organization.
For detailed analysis of this topic, please visit the official page: Hydrogen Sulfide Removal Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com