

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Swimming Pool Treatment Chemicals Market to Grow at 4.7% CAGR (2026-2032)

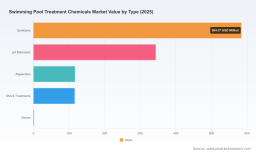
Swimming Pool Treatment Chemicals Market — Strategic Preview for 2026 Decision-Makers
PW Consulting’s latest market study (base year 2025; forecast period 2026–2032) offers a focused, decision-grade synthesis of the Swimming Pool Treatment Chemicals market. At a macro level this sector has expanded from roughly USD 1,000 Million in 2020 to an estimated USD 1,162.17 Million in 2025, and is projected to grow to about USD 1,602.86 Million by 2032 — a compound annual growth rate (CAGR) of 4.7% across the forecast window. This preview highlights the strategic implications of those trends for corporate planning in 2026 while intentionally withholding detailed subsegment tables and region/application splits to encourage access to our full intelligence package.
Swimming Pool Treatment Chemicals Market
Why this study matters for 2026 corporate strategy
-
Timing and prioritization: The market’s steady mid-single-digit CAGR signals predictable top-line expansion, but uneven cost and regulatory shocks make timing of capex, procurement, and pricing moves decisive in 2026. Companies that align investment cadence to the market’s growth slope — rather than to short-lived seasonal spikes — will preserve margins and capture share.
Swimming Pool Treatment Chemicals Market -
Risk-adjusted sourcing: Raw material volatility and tariff-driven input-cost inflation require playbooks for hedging and supplier diversification. The report translates headline market growth into practical procurement risk metrics executives can use at Q2–Q3 2026 planning cycles.
Swimming Pool Treatment Chemicals Market -
Portfolio and channel optimization: As demand shifts between end-use profiles (e.g., residential vs. commercial) and as sustainability-focused products gain traction, manufacturers and distributors must re-weight SKUs and commercial tactics. Our study converts aggregate growth into actionable portfolio scenarios for premiumization, value-line retention, and channel mix adjustments.
Key dynamics shaping 2026 outcomes
-
Trade and tariff shocks: Multiple tariff actions announced or in force through 2025 have altered the cost base for imported raw materials and finished chemicals. These measures materially affect procurement economics and have driven tactical behaviors (e.g., advance buying, inventory build) by large distributors. Expect continued short-term dislocations and higher working-capital needs into 2026.
-
Raw material tightness and formulation economics: Specific intermediates used in pool chemistry experienced supply tightening and price pressure in late 2025. Even modest percentage increases in key inputs can compress margins for producers that cannot redesign formulations or achieve cost pass-throughs rapidly.
-
Sustainability and formulation innovation: Leading suppliers are introducing biodegradable and efficiency-enhancing platforms that reduce active-ingredient consumption. These technology moves will reframe product differentiation over the next 18–36 months and create new margin pools for early adopters.
-
Channel behavior and inventory strategies: Distributors and reseller networks have been actively managing inventories to hedge against vendor cost increases and seasonal demand. Expect continued emphasis on inventory-to-sales management, dynamic pricing levers, and promotional cadence adjustments throughout 2026.
Competitive landscape — a pragmatic synthesis
The market exhibits moderate concentration: the top three and top five players control a meaningful but not dominant share, indicating room for both scale-driven leaders and specialized challengers. The competitive set includes integrated chemical manufacturers, specialized pool-chem producers, and broad-based distributors. Each category has different strategic imperatives.
-
Integrated chemical manufacturers (e.g., firms with broad specialty-chemical portfolios) can capture margin via upstream integration, formulation intellectual property, and cross-selling into adjacent water-treatment markets. Their investment priorities often center on R&D for formulation efficiency and regulatory compliance.
-
Specialized pool-chem producers focus on brand equity, product reliability, and targeted product innovation (e.g., biodegradable lines). They are most sensitive to raw-material cost swings and need flexible sourcing strategies to protect margins.
-
Distributors and supply-chain specialists play a critical role in market access and service delivery. Recent behavior among these players — including inventory accumulation ahead of vendor price increases — signals aggressive margin-protection tactics and the strategic use of stock as a competitive lever.
Representative companies illustrate these strategic archetypes. Large consumer-chemical brands are introducing sustainability-focused product lines to capture eco-conscious end-users. Global specialty-chemical players are deploying technology platforms to reduce active-chlorine consumption. Distributors are optimizing logistics and pricing to offset rising input costs. Each of these moves re-orders opportunities across the value chain.
Recent, high-impact developments you should factor into 2026 planning
-
Inventory-led defensive tactics by distributors — including advance purchasing to offset supplier price increases — have already affected working capital and gross margin profiles in late 2025 and early 2026.
-
New product introductions focused on biodegradability and formulation efficiency are accelerating the premiumization of parts of the portfolio and creating new marketing and certification requirements.
-
Regulatory rulings and tariff schedules enacted through 2025 create an elevated baseline for input costs; companies that do not model multi-scenario tariff impacts in 2026 will underprice risk in procurement and contracts.
What the PW Consulting report delivers (practical, actionable content)
-
Robust macro forecast and scenarios: multi-horizon revenue projections (2026–2032) under base, upside, and downside cases calibrated to tariff, raw-material, and adoption risk factors.
-
Procurement and margin playbooks: supplier scorecards, hedging strategies, and short/medium-term working-capital recommendations tailored to manufacturer and distributor profiles.
-
Product and R&D prioritization matrices: a decision framework that ranks formulation and sustainability investments by ROI, technical feasibility, and regulatory risk.
-
Go-to-market and pricing playbooks: actionable approaches for premiumization, trade promotions, dynamic pricing, and channel-specific assortment optimization.
-
Competitive dossiers: strategic profiles of major players, mapped capabilities, recent moves, and potential M&A or partnership targets. (Note: detailed subsegment shares, per-region application splits, and line-item pricing are reserved for the full report.)
-
Regulatory and raw-material trackers: near-real-time monitoring templates for tariff schedules, trade rulings, and critical-input price swings to feed into quarterly planning cycles.
Recommended decision actions for 2026 (executive checklist)
-
Reconcile portfolio against margin corridors: identify SKUs that are margin-sensitive to input-cost swings and prioritize reformulation or price protection strategies for those items.
-
Adopt a dual-track procurement strategy: combine near-term forward buying on key inputs with medium-term supplier diversification and local-sourcing pilots to reduce tariff exposure.
-
Accelerate sustainability-led differentiation where it aligns with premium channel economics; fast followers risk margin compression as early movers capture brand advantage.
-
Deploy dynamic pricing playbooks in commercial channels to preserve margins during input-cost cycles, while protecting acceptance in residential retail through value communication.
-
Embed scenario-based tariff modelling into quarterly financial forecasts — update product-level price elasticity assumptions and pass-through timelines.
-
Explore distribution partnerships and inventory-financing solutions to manage working-capital strain induced by strategic pre-purchasing behavior in the channel.
How PW Consulting can accelerate your 2026 execution
Our full report pairs the macro intelligence above with granular, transaction-ready analysis: subsegment performance tables, region-and-application breakouts, supplier-by-supplier risk scores, and customized scenario models you can plug into budgeting and procurement systems. For teams evaluating M&A targets or planning product launches in 2026, we offer tailored workshops, unit-cost modelling, and go-to-market sprint support.
This preview demonstrates the kind of strategic depth PW Consulting provides while preserving the most commercially sensitive subsegment detail for subscribers. To convert the macro momentum into defensible, actionable plans in 2026, senior teams should prioritize accessing the full report and arranging a strategy alignment session with our industry specialists.
For detailed analysis of this topic, please visit the official page: Swimming Pool Treatment Chemicals Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com