

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
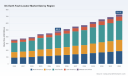
PW Consulting: Worldwide DC Earth Fault Locator Market to grow from USD 482.5 Million in 2025 to USD 731.27 Million by 2032 at a 6.12% CAGR — Asia Pacific leads with USD 186.0M, portable units dominate; top‑5 firms hold 47.65%
By pmarketresearch, 2026-07-13
Worldwide DC Earth Fault Locator Market — Strategic Briefing for 2026 Decision‑Makers
Executive summary
PW Consulting’s new market study on the Worldwide DC Earth Fault Locator Market synthesizes five years of historic performance and a seven‑year forecast to deliver a decision‑grade intelligence package for corporate leaders planning actions in 2026. The market has expanded steadily from a base in 2020 through 2025: our audited historical series shows growth from roughly USD 358 million in 2020 to USD 482.5 million in the base year 2025, and the market is projected to continue expanding at a compound annual growth rate (CAGR) of 6.12% over the 2026–2032 forecast window, reaching an estimated USD 731.3 million by 2032.
Worldwide DC Earth Fault Locator Market
This briefing highlights the elements of the report that most directly influence executive decisions in 2026—procurement cycles, product roadmaps, compliance, M&A screening, and supply‑chain resilience—while preserving the granular regional, application and vendor share tables for report purchasers who need the full dataset.
Worldwide DC Earth Fault Locator Market
Why this report matters for strategies executed in 2026
- Capital planning and procurement: Utilities and large industrial buyers face near‑term inspection and retrofit cycles driven by regulatory schedules and asset‑life planning. Accurate top‑line market sizing and a clear forecast trajectory help procurement teams time tenders and capital releases to minimize inventory and avoid premium sourcing.
- Product and R&D prioritisation: The report identifies where demand for online, non‑invasive locators versus portable instruments is accelerating, enabling product teams to prioritize features such as high‑resistance detection, low‑frequency injection, and AC‑noise immunity that materially affect field acceptance.
- Compliance and maintenance optimization: Standards and mandatory inspection cadences increase the value of online monitoring solutions that do not require de‑energization. The study links regulation timelines to addressable demand, enabling compliance officers to make the business case for continuous monitoring versus periodic testing.
- M&A and partnership screening: With market concentration measured and mapped (the three‑firm concentration cluster is modestly material), corporates can evaluate acquisitive growth and strategic alliances against realistic competitive benchmarks and synergy expectations.
Market dynamics: drivers, constraints and inflection points
- Regulatory cadence: Enforcement and inspection standards for battery and DC power systems—such as regular inadvertent ground inspections—are prompting demand for online systems that can operate without system interruption. This regulatory push materially alters lifecycle economics for owners of floating DC systems.
- Power system architecture changes: The global acceleration of DC architectures—microgrids, renewables with DC coupling, telecom power systems, and battery‑backed infrastructure—expands the number of end points that require reliable ground fault detection. These structural shifts underpin the long‑term CAGR observed in our forecast.
- Technology and product trends: The market is bifurcating between portable testers optimized for field fault tracing and always‑on online monitoring platforms that integrate into asset management stacks. Advances in signal processing, sensor miniaturization and wireless telemetry are increasing the value proposition of real‑time fault location.
- Supply‑side risk: DC earth fault locators rely on semiconductors, precision current sensors, and lithium‑based power modules. Global semiconductor cycles and component lead times therefore influence pricing and delivery risk—an important consideration for sourcing teams in 2026.
- Standards and safety compliance: Compliance with IS/IEC‑equivalent standards and industry test protocols remains a gating factor for adoption in regulated sectors (power utilities, rail, marine). Products that demonstrate compliance with these standards shorten procurement lead times and reduce field commissioning risk.
Competitive landscape snapshot — who matters and why
The competitive field includes a mix of specialised instrumentation manufacturers, regional system integrators, and broader test‑instrument brands. Market concentration metrics show room for scale consolidation: the top three firms account for a meaningful but not dominant share of the market, and the top five firms capture under half of industry revenues—indicating significant fragmentation and white space for strategic entrants or bolt‑on acquisitions.
Worldwide DC Earth Fault Locator Market
- Bender GmbH & Co. KG: Positioned as a systems‑oriented provider with online automatic location solutions that integrate into DCIM and facility management workflows. Strategic partnerships extending into DC infrastructure management increase their appeal to data centres and large utilities.
- Kehui International Limited: A Chinese manufacturer focused on battery and low‑voltage DC systems with feature sets emphasizing high‑resistance detection and wireless reporting—a practical choice for high‑volume, low‑cost deployments in telecom and industrial sites.
- Eagle Eye Power Solutions: US‑based company with product offerings aligned to regulatory compliance needs (e.g., meeting battery inspection mandates), leveraging low‑frequency injection approaches to locate faults without taking systems offline.
- HJ Arnett Industries: Specialized in sensitive detection for critical installations (nuclear, marine, refineries), with devices engineered for extremely low‑current fault detection to support safety‑critical maintenance regimes.
- Megger and other established test‑equipment brands: Offer modular platforms with strong training/documentation ecosystems and global distribution—advantages in noisy‑signal environments and larger enterprise accounts.
- Regional and niche players: Several firms in Asia and India supply portable and export‑oriented models, filling demand for on‑site diagnostics and complementing global vendors with competitive price‑performance tradeoffs.
Recent vendor developments shaping 2026 decisions
- Bender’s 2025 partnership and DCIM demonstrations indicate a newer tend toward integrated asset management solutions—an important signal for buyers that value data interoperability and long‑term TCO reduction.
- Megger’s sustained investment in user education, documented in 2025 product guides and training resources, is reducing buyer risk associated with field adoption and improving time‑to‑competence for service organisations.
- Regional trade show activity in 2025—where multiple vendors showcased high‑noise immunity devices—confirms that manufacturers are prioritizing field robustness to win specification‑driven contracts in utilities and rail.
What’s inside the report: operationally useful deliverables
The report is intentionally structured for immediate operational use by procurement, engineering and strategy teams. Key inclusions:
- Transparent market sizing and forecasting (historical 2020–2025; base year 2025; forecast 2026–2032) with scenario sensitivity that models alternative growth paths under varying policy and component‑supply assumptions.
- Vendor benchmarking templates and a scored supplier matrix covering technical capability, field service footprint, compliance posture, and integration maturity—designed for RFP shortlisting.
- Procurement playbooks that translate technical specification needs into contract language, acceptance test scripts and training requirements to de‑risk deployments.
- Use‑case economics for five representative end markets (from substations and utilities to renewable plants and telecom), showing expected payback windows for portable versus online solutions.
- Supply‑chain heatmaps and mitigation plans that link component sourcing risk (semiconductor exposure, battery modules) to lead‑time and cost contingencies.
- Scenario planning worksheets and M&A screening criteria for corporate development teams evaluating tuck‑ins or strategic partnerships.
Strategic implications and recommended moves for 2026
- Buyers (utilities, large enterprises): Prioritise online fault‑location capabilities in new procurements where continuous availability and regulatory inspection cadence drive lifecycle cost savings. Use the report’s RFP templates to standardise acceptance tests and limit vendor lock‑in.
- Vendors and OEMs: Invest selectively in interoperability (DCIM/APIs), noise‑suppression algorithms, and field training services—features shown to accelerate adoption in large critical‑infrastructure accounts. Consider partnerships with DCIM and asset‑management vendors to move up the value chain.
- Private equity and strategic acquirers: The market fragmentation and sub‑50% share of the top five firms create clear M&A playbooks: pursue bolt‑ons that add regional distribution, service capability, or complementary sensing technology to scale quickly.
- Service organisations and system integrators: Differentiate with turnkey offerings—hardware plus installation, monitoring, and SLA‑backed analytics—to capture recurring service revenue and reduce customer churn.
- Policy and compliance teams: Use the market’s regulatory alignment data to inform capital allowances and compliance budgets; early investment in online locators can reduce both inspection disruption and long‑term insurance exposure.
Methodology and transparency
The report’s base year is 2025 and it draws on a blended methodology combining primary interviews, vendor financials, equipment shipment proxies and end‑market consumption models. Our forecast extends 2026–2032 and uses a central case CAGR of 6.12%. Market concentration metrics and competitive profiles are presented with auditable scoring so buyers and investors can reproduce the logic behind vendor ratings.
Where we intentionally withhold detail — and why
Consistent with the report’s role as both an analytical product and a commercial dataset, this press briefing presents the high‑level market trajectory, regulatory drivers and competitive positioning that readers need to validate near‑term strategy. We intentionally reserve the full regional/Application‑level splits, granular vendor market shares, and downloadable data tables for the report package and interactive dashboards available on the source page—these granular datasets are the actionable assets that procurement teams, product managers and M&A groups will use to execute in 2026.
If your 2026 planning requires precise regional demand curves, application‑specific unit economics, vendor share matrices or downloadable procurement artifacts, PW Consulting’s full Worldwide DC Earth Fault Locator Market report and datapacks provide those deliverables with raw tables, modeling workbooks and editable vendor scoring sheets.
To request the full report, licensing options or a tailored briefing based on the dataset, visit the PW Consulting report page or contact our Research Sales team. Our analysts are available to run bespoke scenarios that incorporate your asset base, inspection cadence and procurement constraints to produce a customised investment roadmap for 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Worldwide DC Earth Fault Locator Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: Worldwide Scroll-Type Hydrogen Circulation Pump Market to Surge from USD 212.45 Million in 2025 to USD 2,024.93 Million by 2032 at a 38.42% CAGR
By pmarketresearch, 2026-07-13
PW Consulting Releases Worldwide Scroll Type Hydrogen Circulation Pump Market Report — Strategic Imperatives for 2026
PW Consulting today publishes its latest industry research: "Worldwide Scroll Type Hydrogen Circulation Pump Market (Base Year 2025)". This forward-looking study combines rigorous bottom‑up market sizing, vendor benchmarking and scenario modelling to give C-suite and business unit leaders the decision support required for 2026 planning. The report uses 2025 as its base year and delivers a clear seven‑year forecast window (2026–2032) that captures the economically material expansion of scroll‑type hydrogen recirculation pumps as fuel cell systems scale commercially.
Worldwide Scroll Type Hydrogen Circulation Pump Market
Macroeconomic trajectory that drives urgency
Our market model shows an inflection point between 2024 and 2026 as hydrogen fuel‑cell deployments accelerate across mobility and stationary applications. Measured in USD Million, the scroll‑type hydrogen circulation pump market has expanded rapidly over the 2020–2025 historical window and, under our base forecast, continues to scale at a compound annual growth rate (CAGR) of 38.42% through 2032. This trajectory produces a multi‑billion‑dollar opportunity by the end of the forecast period and creates time‑sensitive imperatives for product roadmaps, supply‑chain investment and commercial partnerships.
Worldwide Scroll Type Hydrogen Circulation Pump Market
Why this report matters to executives planning for 2026
- Capital allocation: The pace of market growth means investment windows for production capacity and tooling open and close rapidly. Our models translate market expansion into implied volume and capital needs across the next 24 months.
- Product strategy: Design choices (material selection, sealing architecture, motor‑controller integration) materially affect weight, cost and safety compliance. We show which technical tradeoffs preserve margin while meeting regulatory constraints.
- Supply‑chain resilience: Raw material choices and single‑source suppliers can become critical bottlenecks. The report identifies the risk vector and prescribes mitigation playbooks for procurement teams.
- M&A and partnerships: Market concentration is meaningful — the top three players control a majority of identifiable market share while the top five consolidate an even larger portion. Our competitive scorecards let acquirers and partners size realistic value capture scenarios.
What the report contains — practical, transaction‑ready intelligence
- Comprehensive market sizing (historical series 2020–2025; forecast 2026–2032) with transparent methodology and sensitivity cases.
- Demand‑side segmentation by application, product configuration and region (methodology and drivers provided; detailed segment tables available in the full report).
- Vendor scorecards and capability matrices that evaluate design maturity, production readiness, IP claims and route to compliance.
- Technology roadmap and engineering tradeoff analysis: sealing approaches, oil‑free architectures, motor‑controller integration and noise/MTBF benchmarks.
- Supply‑chain heat maps covering raw materials (including aluminium substitutions), precision machining, bearings and electronics sourcing, plus cost‑to‑produce models in editable format.
- Regulatory and safety matrix detailing hydrogen handling requirements, leakage and certification pathways across major markets.
- Go‑to‑market playbooks for OEMs, Tier‑1 suppliers and new entrants — including channel strategies, sample commercial terms and pricing sensitivity models.
- Scenario planning and three investment cases (conservative, base, aggressive) with NPV and payback outputs tailored for 2026 decision windows.
Competitive landscape — focused vendor intelligence
The report provides granular vendor analysis that combines public product specifications with primary interviews and teardown economics. A brief snapshot of core players illustrates the diversity of approaches in the market:
Worldwide Scroll Type Hydrogen Circulation Pump Market
- Air Squared (United States) — Known for oil‑free semi‑hermetic scroll compressors and hydrogen recirculation pumps designed for high‑temperature and mixed‑gas applications. Their product portfolio spans high flow and elevated pressure ranges, favouring modular semi‑hermetic architectures that appeal to heavy‑duty and stationary fuel cell OEMs.
- Scroll Labs — Specialises in compact, floating‑scroll architectures targeted at low‑to‑mid power fuel‑cell systems. Their designs prioritise acoustic performance and service life, with specific units engineered for low noise and multi‑thousand‑hour durability suitable for vehicle integration.
- Yantai Dongde Industrial Co., Ltd. (China) — A volume‑oriented manufacturer focused on core BOP (balance‑of‑plant) pumps across a range of fuel‑cell kW classes. Recent product upgrades underscore a focus on control logic and manufacturability improvements that reduce total ownership cost for OEMs.
Importantly, the market exhibits moderately high concentration: our CR3 and CR5 measures indicate that incumbent vendors control a significant portion of current commercial deployments. For 2026 planning this concentration has two implications — established suppliers can set commercial norms for pricing and certification, while differentiated technology or scale advantages can be converted quickly into share gains where safety and reliability are proven.
Engineering and regulatory dynamics that decide winners
- Material innovation: Lightweighting is an active lever. Recent engineering advances allow switching certain structural components from stainless steel to aluminum, yielding material‑level weight reductions (published examples report large percentage decreases in component mass). For vehicle OEMs and commercial fleets where weight impacts range and payload, such gains are decisive.
- Hydrogen safety and contamination control: Regulatory and customer specifications demand oil‑free operation and extremely low leakage rates to handle flammable hydrogen safely. Compliance with tight leakage targets is non‑negotiable and shapes sealing, testing and validation roadmaps.
- System efficiency: As fuel‑cell systems move toward closed‑loop anode designs, recirculation pumps become central to maximizing hydrogen utilization rates. Design choices that reduce parasitic power consumption and improve durability deliver direct system‑level cost savings.
- Acoustic and durability thresholds: Noise and MTBF benchmarks influence acceptance in passenger and commercial vehicle applications. Several vendors already publish sub‑60 dB acoustic signatures and multi‑thousand‑hour endurance figures, setting practical performance targets for newcomers.
Priority strategic actions for 2026
- Fast‑track material and sealing validation: Prioritise aluminium components where lifecycle analysis shows net system benefit; simultaneously, invest in high‑confidence sealing tests and hydrogen leak‑rate certification early in 2026 to avoid late‑stage rework.
- Design for integrated controls: Consider integrated motor‑controller solutions to reduce BOM complexity and improve system diagnostics. Our vendor scorecards identify preferred integration partners and expected time‑to‑market impacts.
- Secure dual sourcing for key inputs: Concentrate procurement efforts on alternate suppliers for precision machined housings, bearings and electronics to reduce single‑source exposure as volumes ramp.
- Commercial pilots over feature breadth: Run targeted field pilots with fleet and stationary partners to validate lifetime, noise and maintenance economics rather than pursuing broad product feature lists.
- Active surveillance of competitors: Monitor incumbent product upgrades and IP filings; the market rewards incremental reliability improvements that reduce warranty spend and integration effort.
- M&A disciplined by integration risk: Pursue acquisitions that close specific technology gaps (e.g., proprietary seal architectures, integrated motor controllers) rather than broad revenue plays.
How to use this report as a 2026 decision tool
The report functions as both a market atlas and an execution toolkit. For commercial teams it provides go‑to‑market templates and realistic conversion assumptions calibrated to the 2026 purchasing cycle. For product and engineering leaders it contains detailed cost‑to‑produce models and test sequences that reduce time to certification. For corporate development and investors, the scenario analyses and vendor scorecards deliver a rapid diligence checklist that can be executed in weeks rather than months.
Conclusion — where to go next
As hydrogen ecosystems scale, scroll‑type hydrogen circulation pumps transition from niche components to system‑critical hardware whose design and supply‑chain choices materially affect vehicle range, total cost of ownership and regulatory compliance. PW Consulting’s report crystallises these dynamics into actionable recommendations targeted at 2026 decision calendars. We intentionally present high‑level market trajectories, concentration metrics and vendor intelligence here — and reserve granular segment tables, downloadable models and complete company scorecards for the full report.
To access the executive summary, vendor scorecards and to evaluate the full dataset and modelling workbook for your internal planning, please visit the PW Consulting report page.
For detailed analysis of this topic, please visit the official page: Worldwide Scroll Type Hydrogen Circulation Pump Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Market in Full Bloom: PW Consulting Predicts Worldwide Handheld Leaf Area Meters to Expand at a 4.69% CAGR
By pmarketresearch, 2026-07-13
Worldwide Handheld Leaf Area Meters Market — Strategic Preview for 2026 Decision-Makers
Executive summary
PW Consulting’s latest market study on Worldwide Handheld Leaf Area Meters distills five years of historical performance (2020–2025) and delivers a forward-looking forecast through 2032. The handheld leaf area meter market demonstrated steady expansion from an estimated USD 38.7 million in 2020 to roughly USD 48.5 million in 2025. Our forecast points to continued, moderate growth at a compound annual growth rate (CAGR) of 4.69% across 2026–2032, culminating in an expected market size of approximately USD 66.9 million by 2032.
Worldwide Handheld Leaf Area Meters Market
This briefing is crafted as a strategic “trailer”: it surfaces the dynamics that will determine winners and losers in 2026, outlines where value pools will concentrate, and articulates the practical lines of action that procurement, R&D, and corporate strategy teams should prioritize. To preserve the full commercial utility of the study for subscribing organizations, detailed segment-level figures and granular regional splits are reserved for the full report.
Worldwide Handheld Leaf Area Meters Market
Why this market matters to 2026 corporate strategy
-
Precision agriculture and environmental monitoring are maturing into sustained procurement channels. Non-destructive, field-portable leaf area meters sit at the intersection of agronomy, plant breeding and ecology — disciplines that are increasingly data-driven and hardware-enabled.
Worldwide Handheld Leaf Area Meters Market -
The technology mix (laser scanning, CIS imaging, conveyor-integrated designs) is evolving from single-tool utility toward integrated sensor suites and workflow-native instruments that plug into digital field platforms. That technological transition is the principal vector for product differentiation over the next 18–36 months.
-
Market concentration is moderate: the top three players account for a meaningful share of industry revenues, while the top five widen that concentration further. This creates a landscape where scale advantages in distribution and validation credentials are decisive, but niche innovation can still win field adoption.
Technology and product architecture — what to watch
-
Laser-based scanning systems continue to be preferred for rapid, high-resolution measurements and are attractive in crop-science workflows that demand repeatable scans on attached leaves. Key product differentiators here are scan resolution, scan length, and integrated positioning or tagging (e.g., GPS) for geo-referenced datasets.
-
CIS (Contact Image Sensor) array products are making a renewed push in academic and botanical applications where shape fidelity and perimeter accuracy matter. Recent models from established manufacturers feature improved image-processing pipelines and ±2% area accuracy specifications that reduce post-processing overhead for researchers.
-
Conveyor-integrated or pallet-style designs have use cases in seed production and controlled-environment phenotyping labs. The convergence trend is toward modular hardware that supports both manual field use and semi-automated lab throughput.
-
Data interoperability and field-to-cloud workflows are now decisive. Instruments with easy USB/Excel export, automated tagging, and open data formats accelerate adoption among institutional buyers and commercial breeders who deploy high-throughput analytics.
Competitive landscape — profiles you need on your radar
The market is anchored by a small set of specialized manufacturers with deep product pedigrees and field validation records. Our report provides benchmarking of product families, go-to-market models, service capabilities and certification footprints. Highlights from primary players include:
-
CID Bio-Science (USA) — Offers wand and pallet-style handheld laser meters with capabilities for non-destructive measurement and high-resolution laser scanning. Their devices emphasize multi-parameter outputs (area, length, width, perimeter, shape metrics) and field tagging for geospatial research workflows.
-
LI-COR Environmental (Lincoln, NE, USA) — Known for lightweight, rapid-survey portable meters optimized for field surveys of attached and detached leaves, with high resolution and simple data export paths that appeal to agronomists and environmental researchers.
-
ADC BioScientific (UK) — Recently replaced an older model with a next-generation handheld scanner engineered for unlimited leaf length scanning and improved portability. Their AM400 launch represents a technology refresh that targets both research labs and field technicians.
-
Scitek Global (China) — Competes on field-spec robustness and certifications; their portfolio emphasizes long scan lengths and compliance with multiple regulatory standards that facilitate exports and institutional procurement.
-
BIOBASE Group (China) — Factory-direct supply models, touchscreen options and USB/Excel data transfer features make them a frequent consideration for price-sensitive institutional buyers seeking turnkey deployment.
Recent competitive movements also matter: for example, ADC BioScientific’s AM400 launch in late 2025 signals an upgrade cycle for replacement units, and several suppliers are emphasizing regulatory and product certifications as a way to lower procurement friction in clinical and institutional buyers.
Regulation, certification and field validation — operational enablers
-
Buyers increasingly request documented compliance and validation: product-level certifications (CE, ETL, FDA listings) and company-level management-system certifications (ISO 9001, ISO 13485, ISO 14001, ISO 45001) are frequently required for tenders and large institutional purchases.
-
Instruments with published accuracy and perimeter/area validation curves reduce field trial friction. Instruments certified to deliver ±2% area accuracy or similar are becoming de facto expectations in many research procurements, enabling faster institutional sign-off.
What the report delivers — practical, operational content
Beneath the headline forecasts, the PW Consulting report is structured to be directly actionable for executives and functional leaders. Key deliverables include:
-
Market sizing and CAGR through 2032, plus scenario modelling to test downside, base and upside assumptions against input-cost, raw material and adoption-rate sensitivities.
-
Go-to-market playbooks for OEMs and channel partners: pricing ladders, warranty and service strategies, distributor scorecards, and tender-readiness checklists.
-
Technology adoption roadmaps and product roadmaps that map sensor choices to buyer jobs-to-be-done across plant physiology, forestry, agronomy and botany use cases.
-
Field validation protocols, sample data templates and an open-data integration specification to accelerate pilot-to-deployment cycles for enterprise customers.
-
Supply-chain and manufacturing impact assessments, including lead-time scenarios, single-source risk heatmaps, and CAPEX/OPEX implications for scaling production.
-
M&A and partnership scouting: candidate profiles, valuation heuristics and integration risk checklists tailored to firms seeking inorganic expansion into adjacent phenotyping or sensing domains.
Strategic recommendations for 2026
-
Prioritize interoperability: product teams should make data-export and API integration first-class features. Buyers reward instruments that feed analytics pipelines without bespoke middleware.
-
Certify and validate early: secure relevant product and corporate certifications to shorten procurement cycles, particularly for institutional and cross-border tenders.
-
Segment go-to-market by buyer persona rather than by geography alone: breeding houses, academic labs, forestry services and environmental NGOs have different procurement cadences and after-sales expectations.
-
Invest selectively in hybrid offerings: combine laser/CIS sensor options with a modular approach so single SKUs can be configured for high-throughput labs or rugged fieldwork, reducing SKU proliferation while expanding addressable use cases.
-
Use certification and published accuracy as pricing levers: devices with independently verified accuracy curves command price premiums and accelerate institutional adoption.
-
Prepare for consolidation: moderate market concentration means well-capitalized buyers can gain scale advantages. Attractive inorganic targets often possess validated technology, niche channels, or certification portfolios.
How to use this research in your 2026 planning cycle
For executives building 2026 budgets and three-year strategic plans, the study provides the analytical foundation to allocate R&D dollars, plan capacity expansions, design channel incentives and prioritize certifications. Functional teams will find the field-validation kits and procurement templates immediately useful for tender responses and pilot deployments.
PW Consulting’s public summary above highlights the structural forces shaping supplier economics and buyer behavior. The complete study contains the detailed models, scenario tables and segment-level analytics that allow teams to run bespoke sensitivity analyses and prepare executable roadmaps. Accessing the full report will enable you to extract the precise segmented intelligence, regional demand projections and product-level benchmarks necessary for transaction-level decisions.
Next steps
For licensing the full Worldwide Handheld Leaf Area Meters Market report, tailored briefings, or a bespoke workshop to translate the findings into an actionable 90‑day tactical plan for your organization, please contact PW Consulting. The report’s depth is designed to move teams from insight to implementation within a single quarter.
For detailed analysis of this topic, please visit the official page: Worldwide Handheld Leaf Area Meters Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Predicts Worldwide Canned Red Kidney Beans Market to Reach USD 1,038.56 Million by 2032, Up from USD 745.5 Million in 2025 at a 4.85% CAGR
By pmarketresearch, 2026-07-13
Worldwide Canned Red Kidney Beans Market — Strategic Outlook for 2026
Executive summary
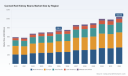
PW Consulting’s new market brief on the Worldwide Canned Red Kidney Beans Market positions 2026 as a turning point for manufacturers, retailers and ingredient buyers. Using 2025 as the analytical base, the market is estimated at approximately USD 745.5 Million, and PW’s forecast models project a compound annual growth rate (CAGR) of 4.85% through 2032, pushing the global market above the USD 1 billion threshold by the end of the forecast horizon. This trajectory reflects a blend of structural demand for convenient plant-based protein, premiumization and channel evolution — balanced against cyclical input-cost pressures and an increasingly complex regulatory environment.
Worldwide Canned Red Kidney Beans Market
Why this matters for 2026 decision-makers
- Timing: 2026 will be the first year many post-pandemic adjustments — from new label regimes to sourcing shifts after the 2024–25 production shocks — feed directly into procurement and shelf assortment decisions.
- Financial planning: With a mid-single-digit CAGR baked into our base case, firms must align produkt and channel investments to capture share where unit economics improve, while stress-testing plans for commodity-driven cost shocks.
- Competitive positioning: Market concentration metrics indicate a moderate level of incumbent scale; nimble entrants and private-label programs can still outmaneuver larger players through channel-specific plays and innovation.
What the report delivers — practical, transaction-ready content
PW Consulting has structured the full report to be immediately actionable for corporate strategy, commercial operations and M&A teams. Highlights include:
Worldwide Canned Red Kidney Beans Market
- Top-down market sizing and our 2026–2032 forecast (by value), including sensitivity analyses around key macro variables.
- Channel economics and retailer margin models — SKU-level profitability frameworks for supermarkets, convenience formats, online retail and foodservice.
- Supply-side diagnostics: cost build-ups for canning operations, primary processing, and a raw-material sensitivity model that quantifies margin impact vs. bean-price movements.
- Regulatory and trade playbook: compliance checklists for new nutrition labeling, regional import duty scenarios and state-level chemical warning exposure.
- Competitive scorecards and supplier benchmarking — a reproducible template for auditing co-packers, contract terms and quality controls.
- M&A and partnership heat maps identifying strategic targets (scale, specialty, organic), with diligence checklists and valuation sensitivity modules.
- Go-to-market blueprints for three strategic options: premium brand expansion, private-label scale-up, and direct-to-consumer launches — with retail negotiation scripts and promotional ROI calculators.
Market dynamics and strategic risks
Several near-term and structural dynamics will shape outcomes in 2026:
Worldwide Canned Red Kidney Beans Market
- Input volatility: Dry red kidney bean prices rose sharply in early 2025; USDA data show average prices materially higher than the prior year after drought impacts in major producing regions. This requires active hedging, longer-term contracting and consideration of alternative bean sourcing to protect margins.
- Regulatory tightening: Nutrition labeling updates implemented by major regulators have altered per-serving disclosures and can influence perceived product value. Additionally, regional chemical exposure rules (e.g., California’s Proposition 65) create localized compliance and liability risk for certain formulations and processing residues.
- Trade barriers and cost of access: Tariff regimes and import classifications affect cross-border flows — some markets maintain non-trivial import duty rates for canned pulses. Companies with global ambitions must price for tariff drag or locate production strategically to avoid margin erosion.
- Channel acceleration: E‑commerce and value formats continue to gain share in many markets. Channel-specific SKUs and flexible packaging formats will be decisive for market share gains, while in-store promotional dynamics remain critical for shelf-centric buyers.
- Consolidation pressure: Market concentration metrics indicate that the leading firms hold a meaningful share of traded value, creating a dual dynamic — scale efficiencies for incumbents and opportunistic consolidation targets for acquirers seeking fast scale or capability fills.
Competitive landscape — where incumbents and challengers stand
The competitive field mixes large, legacy grocery brands with specialty organic and premium players. Our qualitative assessment identifies three repeatable positions:
- National scale brands that leverage broad retail relationships and national promotions to defend shelf space. These firms continue to invest in SKU hygiene (e.g., reduced-sodium variants) to respond to retailer and consumer health trends.
- Ethnic and regional specialists that capture high-loyalty consumer segments and use recipe-led marketing to maintain price premia in key markets.
- Organic and premium processors that command category differentiation through ingredient provenance, processing claims (no added salt, traditional methods) and sustainability narratives.
Notable industry movements reflect these positions: a leading US brand released a reduced-sodium variant in late 2024 to broaden retail penetration; a major Hispanic food company used trade-expo visibility in 2024 to underscore its organic portfolio; and several specialty processors continue to emphasize clean-label, low-intervention processing as a differentiation strategy. PW’s full profile set includes supplier scorecards and playbooks for countering each archetype.
Segmentation insight — what we analyze (and why we’re withholding the granular numbers here)
PW’s segmentation matrix examines the market by region, product type (conventional vs. organic), and distribution channel. For this release we present the high-level growth trajectory and structural drivers; detailed sub-segment figures are intentionally omitted from this public synopsis to preserve the strategic value of our proprietary datasets. The full dataset, available through PW Consulting, contains the exact breakdown by region, type and channel, plus channel-level CAGR curves and SKU economics used to inform assortment and pricing decisions.
How to convert insights into 2026 actions — a strategic playbook
For executive teams preparing their 2026 plans we recommend a three-step approach drawn from the report’s operational tools:
- Protect margin: implement the raw-material sensitivity model to define acceptable price corridors, renegotiate multi-year contracts with escalation clauses tied to transparent indices, and evaluate selective vertical integration for high-risk input nodes.
- Segment-to-win: use channel-specific SKU rationalization to remove low-performing SKUs and redeploy CAPEX into high-return formats (e.g., value multi-packs for discounters, premium single-serve for convenience and online).
- Mitigate regulatory and trade exposure: adopt a region-by-region compliance matrix, pre-clear label changes with large retail partners and model tariff pass-through scenarios to determine pricing strategies or production relocation needs.
Methodology, confidence and sources
PW Consulting’s analysis uses 2025 as the base year and draws on historical data for 2020–2025 to calibrate the models used to forecast 2026–2032. Our forecast incorporates: primary interviews with manufacturers, retailers and co-packers; trade and customs datasets; commodity price series; and regulatory databases. We publish confidence intervals around our base case and provide scenario outputs (upside/downside) to help clients stress-test strategic choices. Macro inputs referenced in this brief include official agricultural statistics and regulatory guidance that materially influence sourcing and labeling strategy.
Accessing the full report and datasets
This brief is intentionally designed as a strategic preview. The full Worldwide Canned Red Kidney Beans Market report contains the proprietary, tranche-level data and downloadable models required to execute the plays outlined above — including the granular regional and channel splits, SKU-level profitability sheets, supplier scorecards, and M&A heat maps. Organizations seeking to operationalize these insights for their 2026 planning cycle should contact PW Consulting to obtain the complete research package, bespoke scenario runs and facilitated strategy workshops.
Final note
As 2026 approaches, the canned red kidney beans market presents both durable demand tailwinds and idiosyncratic risks. Firms that marry disciplined cost management with targeted channel and product plays — informed by quantitative scenario analysis and practical operational tools — will be best positioned to convert market growth into sustainable margin improvement. PW Consulting’s full study provides the playbooks and data required to make those decisions with confidence.
For detailed analysis of this topic, please visit the official page: Worldwide Canned Red Kidney Beans Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Biomass Fuel Testing Market Poised to Expand at a 7.51% CAGR Through 2032, New Report Shows
By pmarketresearch, 2026-07-13
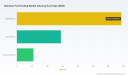
Worldwide Biomass Fuel Testing Market: Strategic Intelligence for 2026 Decision-Making
PW Consulting’s latest market study on the Worldwide Biomass Fuel Testing Market provides a pragmatic, decision-ready perspective for executives and investment committees preparing for 2026. The market has demonstrated resilient expansion through the first half of the decade—growing from the low‑hundreds in 2020 to an estimated mid‑hundreds (USD, Million) by 2025—and is projected to continue on a compound annual growth path of approximately 7.5% through our 2026–2032 forecast window. This report translates those macro trends into operational priorities, competitive risk maps, and a tactical playbook for sourcing, compliance, and lab investments.
Worldwide Biomass Fuel Testing Market
Why this study matters for 2026 planning
-
Market momentum meets regulatory inflection. Policy signals in 2025—including proposed Renewable Fuel Standard (RFS) volumes and new tax-credit guidance for low lifecycle‑GHG fuels—have materially increased the near‑term demand for validated testing and lifecycle verification. Organizations that lock in trusted testing pathways in 2026 will avoid downstream compliance friction and capture pricing premiums tied to certified low‑GHG fuels.
Worldwide Biomass Fuel Testing Market -
Capacity and quality are diverging. Production capacity for densified biomass in major producing markets has been consolidated among a defined set of manufacturers, creating opportunities and risks for off‑takers and service providers. Buyers must assess supplier quality with greater granularity—beyond certificate checks—to manage combustion performance, emission profiles, and logistics abrasion costs.
Worldwide Biomass Fuel Testing Market -
Investment timing matters. At an expected market expansion rate near 7.5% CAGR, 2026 is the inflection point where incremental investments in testing capabilities, lab accreditation, and digital traceability infrastructure generate disproportionate returns by 2028–2030. Capital deployed early against standardized testing protocols accelerates market access and reduces verification costs per ton.
What the report delivers: practical, transaction‑oriented intelligence
-
Actionable market sizing and trajectory: a transparent methodology from 2020 historicals through a 2026–2032 forecast that isolates growth drivers and the sensitivity of demand to policy shifts and fuel pricing.
-
Testing‑parameter playbooks: operational SOPs and KPI targets for proximate/ultimate analysis, calorific‑value testing, chemical/trace element analysis and physical property testing—complete with recommended sampling frames, error budgets, and turnaround optimization matrices.
-
Provider capability matrix: a comparative assessment of laboratory accreditations, geographic laboratory footprints, standards coverage (ASTM/EN/ISO), rapid‑testing options, and digital reporting capabilities to support procurement decisioning.
-
Regulatory impact scenarios: three policy scenarios (baseline, accelerated mandates, and tax‑credit amplification) that quantify incremental testing volumes, cost impacts on supply chains, and compliance risk profiles.
-
Commercial playbooks: procurement templates, RFP language for independent testing, and recommended contract clauses to protect buyers from latent quality issues and to share verification data with regulators and financiers.
-
Deal and partnership guidance: M&A lens and JV structuring considerations for vertically integrated producers, third‑party testing providers, and technology vendors providing in‑line sensors and digital traceability.
Competitive landscape: who matters and how to position
The market displays moderate concentration: the top three global testing and inspection providers collectively hold a substantial portion of commercial testing volumes, and the top five expand that position meaningfully. That structure creates a two‑tier market for buyers and investors—global, accredited multi‑service providers versus regional, specialist laboratories.
-
Intertek Group plc (London) — Strength: global laboratory network and brand recognition for fuels testing. Strategic implication: ideal partner for multinational offtakers needing harmonized reporting and advanced calorific/ash analytics across trade corridors.
-
SGS SA (Geneva) — Strength: end‑to‑end supply chain verification and ISO/IEC 17025‑accredited services. Strategic implication: valuable for buyers requiring integrated inspection, testing and certification packages tied to contract acceptance criteria.
-
Bureau Veritas (Paris) — Strength: strong compliance focus and standards conformity (ASTM/EN). Strategic implication: suits corporates seeking audit‑grade verification and pre‑export contingency testing to reduce buyer disputes.
-
AmSpec Services (U.S.) — Strength: specialized inspection/testing across energy commodities. Strategic implication: credible for trading houses and logistics providers where rapid on‑site testing and chain‑of‑custody services matter.
-
Specialist accredited labs (examples: Biomass Energy Lab / Timber Products Inspection, McCreath Laboratories, Standard Laboratories, Control Union, Global Energy Laboratories, Microbac) — Strength: niche expertise, flexible service packages, and close customer engagement. Strategic implication: these labs are efficient partners for bespoke testing protocols, pilot projects, and cost‑sensitive regional supply chains.
For 2026, corporate buyers should segment supplier engagement by three vectors: (1) accreditation & standards coverage, (2) reporting and data integration capability, and (3) speed‑to‑market for certification. Global providers offer scale and harmonization; regionals provide agility and cost efficiency. A blended sourcing strategy—global lead auditor for cross‑border contracts with regional labs for spot checks—delivers resilience.
Regulatory and market triggers to watch in 2026
-
Renewable Fuel Standard (RFS) updates and other jurisdictional volume mandates. Projected increases in mandated volumes drive incremental testing demand for both product qualification and RIN/credit claim substantiation.
-
Tax credits for low lifecycle GHG fuels. Guidance around lifecycle accounting increases the need for traceable sampling and validated emissions models tied to testing outputs.
-
Capacity disclosures from major producing markets. Transparency on production capacity and operational status will influence contracting horizons and buffer stock strategies for utilities and large industrial users.
Strategic actions for corporates and investors in 2026
-
Embed testing and verification into the commercial contract lifecycle. Require pre‑shipment and periodic retesting clauses, and standardize acceptance criteria across portfolios to limit quality disputes and valuation haircuts.
-
Invest in accredited partnerships and digital integration. Connect laboratory reporting to contract management and GHG accounting systems to streamline claim substantiation and tax‑credit capture.
-
Pursue selective lab investments or long‑term service agreements. For large volume players, capex to secure dedicated testing capacity or multi‑year service agreements with accredited labs can lower per‑unit verification costs and reduce time‑to‑market.
-
Use scenario planning to stress‑test procurement and compliance. Model outcomes under different regulatory intensities and adopt contingent supplier networks that can scale testing throughput without compromising turnaround times.
-
Differentiate with traceable low‑GHG claims. Companies that pair robust testing with supply‑chain traceability and verified lifecycle accounting will command price premiums and easier access to blended fuel mandates.
How the PW Consulting report supports boardroom decisions
This study is engineered to move beyond descriptive market commentary to prescriptive, executable guidance. It equips boards and senior management with: a calibrated view of market size and trajectory; a prioritized list of operational changes that produce the highest ROI within 18 months; supplier‑selection matrices; and legal/procurement language templates tailored to different risk appetites. Our scenario suite quantifies the P&L and balance‑sheet exposures to policy shifts, enabling CFOs to stress‑test capital allocation and working capital requirements tied to verification cycles.
Next steps and accessing the full intelligence
The analysis above highlights the strategic contours of the biomass fuel testing market and the discrete choices corporate leaders must make in 2026. PW Consulting’s full Worldwide Biomass Fuel Testing Market report contains the granular regional and application splits, testing‑parameter demand curves, provider scorecards, and an interactive model that clients can use to simulate procurement, capex, and pricing scenarios. Those detailed breakouts and datasets—intentionally withheld here to preserve the report’s commercial value—are available through PW Consulting for licensed subscribers and enterprise clients.
For decision‑makers preparing 2026 budgets, procurement strategies, or M&A activity, the report functions as both an intelligence product and a practical toolkit: not just what is happening, but precisely what to do next.
For detailed analysis of this topic, please visit the official page: Worldwide Biomass Fuel Testing Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Worldwide Stretcher Accessories Market to Grow at a 5.2% CAGR During 2026–2032
By pmarketresearch, 2026-07-13
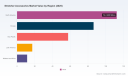
Worldwide Stretcher Accessories Market: Strategic Imperatives for 2026 — PW Consulting Insight Brief
As healthcare providers and medical device manufacturers prepare budgets and strategic plans for 2026, PW Consulting’s latest market study on the Worldwide Stretcher Accessories Market surfaces the commercial signals that will determine winners and laggards. The market — measured in USD Million — has expanded steadily from the low‑200s in 2020 to an estimated USD 285.0 Million in our 2025 base year, and our conservative baseline projects it will reach roughly USD 406.4 Million by 2032. Our modeled forecast for 2026–2032 embeds a compound annual growth rate (CAGR) of 5.2% and reflects a balance of mature hospital demand, EMS modernization, and incremental replacement cycles tied to material and regulatory shifts.
Worldwide Stretcher Accessories Market
Why this report matters for 2026 decisions
- Timing capital allocation. The market’s trajectory signals sustained, mid-single-digit growth—moving beyond episodic pandemic effects toward structural demand driven by replacement, safety retrofits, and product modularity. Buyers and investors should align CAPEX windows to capture early-mover advantages in modular accessories and lightweight materials before the market reaches the mid‑hundreds.
- Prioritizing R&D and product roadmaps. The dynamics we observe reward incremental innovation—weight reduction, hygiene features, and compatibility with powered platforms. Firms that prioritize interoperable accessory ecosystems will unlock OEM and aftermarket revenue pools.
- Regulatory and reimbursement risk calibration. Recent guidance and coding practices affect commercialization timelines. Firms planning launches in 2026 must build regulatory readiness and payer scenarios into product lifecycles.
Market dynamics and the near-term environment
Our historical review (2020–2025) and early 2026 outlook show a market that is resilient but selective. Key dynamics that will shape competitive advantage include:
Worldwide Stretcher Accessories Market
- Replacement-driven sustainment: Hospitals and EMS fleets follow predictable replacement and service cycles. While discretionary upgrades slow during tight budgets, safety and infection-control related accessories retain priority.
- Material innovation and unit economics: Migration from traditional aluminum components to carbon fiber and other composites is underway to reduce weight and improve ergonomics. This trend creates upstream supply vulnerabilities and cost variability for raw inputs — for example, medical‑grade nylon webbing for restraints is a procurement input with clear price sensitivity.
- Regulatory gating: Stretcher accessories are generally classified as Class I devices under FDA rules and require CE marking and ISO 13485 alignment in the EU. These ‘low‑barrier’ classifications speed market entry but do not eliminate the need for documented quality systems and post‑market surveillance—increasing the operational bar for midsize entrants.
- Reimbursement realities: In key markets like the United States, reimbursement structures often bundle accessories into transport or service codes—limiting discrete revenue capture for non‑powered items and heightening the importance of value‑in‑use and total cost of ownership selling points.
Competitive landscape — implications for 2026 strategies
The market shows moderate concentration: our CR3 and CR5 estimates indicate that the top three players capture a material share of market revenue, while the top five approach a majority level. This structure creates both scale advantages for incumbents and niche opportunities for focused challengers.
Worldwide Stretcher Accessories Market
- Ferno (Wilmington, OH) : A recognized leader in EMS equipment, Ferno’s breadth across restraint systems, IV mounting solutions, and pediatric accessories gives it a frontline advantage in emergency services procurement. Their catalog expansion and pediatric focus demonstrate a playbook of deep vertical specialization.
- Stryker (Kalamazoo, MI) : Stryker’s modular accessory strategy—particularly for powered stretcher platforms—signals a platform-driven approach to lock in recurring revenue through compatibility and upgrade paths. Their recent Power‑PRO line updates highlight the commercial value of quick‑release and modular restraints.
- Baxter (Hill‑Rom) : With a hospital‑system focus, Baxter’s accessory portfolio emphasizes bedside safety and integration with acute care workflows. Their OEM relationships and hospital sales channels favor large‑scale distribution and bundling with bed and stretcher systems.
- Medline Industries : As a major supplies distributor, Medline’s reach in consumables and disposable accessory items is a competitive moat for recurring revenue from high‑frequency use items such as pads and disposable restraints.
- Laerdal, Spencer Srl, and selected China‑based exporters : Each supplier has differentiated strengths—simulation and EMS tools (Laerdal), European rescue specialization (Spencer), and cost‑competitive component sourcing and export capabilities (Chinese manufacturers). These players are optimal partners for OEMs seeking regional adaptation or cost levers.
Recent product updates and catalog releases (e.g., Stryker’s 2023 Power‑PRO enhancements and Ferno’s pediatric catalog) illustrate incremental innovation rather than disruptive platform shifts. For 2026, differentiation will come from systems thinking—pairing accessories with services, sterile consumables, and lifecycle support.
Strategic plays for 2026
- Focus on modularity and backward compatibility. Design accessories that retrofit legacy stretchers and integrate with powered platforms—this reduces buyer friction and shortens sales cycles.
- Monetize ADMs (Accessory Data & Maintenance). Add low‑cost sensors or QR‑based maintenance tracking to high‑wear accessories to create service contracts that bypass reimbursement constraints on hardware.
- Optimize supply‑chain hedges. Secure dual sourcing for critical inputs (e.g., webbing, composite materials) and negotiate indexation clauses for volatile commodity prices to protect margins.
- Segment go‑to‑market by procurement logic. Distinguish offerings for acute hospitals (total cost of ownership focus), EMS fleets (weight, durability), and ambulatory centers (infection control and cost efficiency). Tailor sales enablement and bundling accordingly—without relying on separate reimbursement codes.
- Pursue selective M&A and partnerships. Target complementary niche producers (e.g., vacuum mattresses, pediatric fixation systems) to broaden product suites quickly while preserving operational focus.
Operational and commercial playbook
For product managers and commercial leaders planning 2026 launches, the report distills a practical checklist:
- Regulatory readiness: Ensure Class I compliance pathways are validated and that quality systems (ISO 13485) are audit‑ready for CE market access.
- Value messaging: Build clinical and economic evidence that demonstrates time‑savings, reduced injury risk, or infection‑control benefits—critical for negotiated hospital contracts.
- Service models: Develop maintenance programs and spare part kits with predictable margins and recurring revenue profiles.
- Pricing strategy: Use life‑cycle TCO analyses to justify higher upfront pricing for lightweight or hygienic solutions, especially where labor savings are quantifiable.
What PW Consulting’s report delivers — actionable intelligence
Our report is structured to move decision‑makers from insight to action. Key deliverables include:
- A transparent market-sizing model covering 2020–2032 with scenario levers for macroeconomic and regulatory shocks (usable as an Excel decision tool).
- Competitive benchmarking that maps product portfolios, channel strategies, and recent product events for leading OEMs and distributors.
- Commercial playbooks for OEMs, private equity, and distributors—covering product design, pricing, contracting, and aftermarket service strategies.
- Supply‑chain and procurement diagnostics that identify single‑source risks, margin compression points, and supplier negotiation levers.
- Dealflow and M&A screening criteria highlighting targets that enhance breadth (e.g., pediatric solutions), deepen service offerings, or strengthen cost positions via vertical integration.
Regulatory, reimbursement and sourcing considerations — 2026 checklist
- FDA/CE compliance: Treat Class I pathways as necessary but not sufficient—document post‑market surveillance and supplier audits as part of launch planning.
- Reimbursement: Build value propositions that align with bundled payment realities; do not assume separate coding for non‑powered accessories.
- Raw material volatility: Model scenarios for critical component cost swings and plan supplier partnerships or inventory strategies accordingly.
Concluding synthesis
The stretcher accessories market is neither a rapid boom nor a stagnating niche: it is a steady, structurally supported space where product design choices, supply‑chain discipline, and channel strategy determine long‑term returns. With the market growing from roughly USD 221 Million in 2020 to an estimated USD 285 Million in 2025, and with a forecast to around USD 406.4 Million by 2032 at a 5.2% CAGR for 2026–2032, the 2026 planning window represents a decisive juncture. Organizations that align R&D to modularity, lock in supply resiliency, and convert hardware into service streams will outperform peers.
PW Consulting’s Worldwide Stretcher Accessories Market report is designed as an executable toolkit for that 2026 turn. For full segment breakdowns, granular competitive positioning, and downloadable decision models, visit the PW Consulting report page to access the complete study and supporting datasets.
For detailed analysis of this topic, please visit the official page: Worldwide Stretcher Accessories Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Voiding Cystourethrogram Market to Expand from USD 645.5 Million in 2025 to USD 890.27 Million by 2032 at a 4.7% CAGR
By pmarketresearch, 2026-07-13
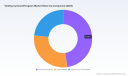
Worldwide Voiding Cystourethrogram (VCUG) Market: Strategic Imperatives for 2026 — Executive Preview
PW Consulting’s latest market study on the Worldwide Voiding Cystourethrogram (VCUG) market provides a decisive intelligence asset for executives making capital-allocation, product, and market-entry decisions in 2026. Anchored on a 2025 base-year and a seven-year forecast horizon (2026–2032), the report combines granular primary research, proprietary demand models, and regulatory and reimbursement mapping to help stakeholders convert clinical trends into commercial advantage.
Worldwide Voiding Cystourethrogram Market
Why this report matters for 2026 decision cycles
-
Market timing and resource allocation: Our forecast and scenario matrices translate the market’s mid-single-digit compound annual growth trajectory into tangible revenue and volume paths, enabling CFOs and business-unit heads to stress-test capex plans against plausible outcomes.
Worldwide Voiding Cystourethrogram Market -
Regulatory and reimbursement clarity: With procedural reimbursement and device classification shaping adoption curves, the report synthesizes the operational implications of prevailing CPT codes and device pathways so pricing, coding, and market-access teams can reduce approval and reimbursement risk.
Worldwide Voiding Cystourethrogram Market -
Competitive posture: The research maps concentration metrics and functional differentiation across the value chain, clarifying where incumbents are entrenched and where disruptive entrants can build defensible niches.
Market snapshot (historical context and forecast)
VCUG market activity has shown steady expansion in the 2020–2025 historical window, reflecting sustained clinical demand and incremental technology upgrades across diagnostic imaging suites. PW Consulting’s modeled total market size (USD, Million) traces this progression annually, culminating in a 2025 base-year market of USD 645.5 Million. Under our baseline scenario, the market is projected to grow to USD 669.3 Million in 2026 and follow a steady upward trajectory through 2032, reaching USD 890.27 Million by the end of the forecast period. The implied compound annual growth rate for 2026–2032 is 4.7%.
Two quantitative context points are critical for strategic planning: first, the market’s structural concentration (CR3 of 42.5% and CR5 of 58.8%) indicates that a small set of established suppliers collectively hold a majority share of commercial activity; second, demand is driven by a combination of legacy installed base refresh cycles, ongoing pediatric diagnostic needs, and procedural reimbursement stability in key markets.
Dynamics shaping 2026–2032
-
Reimbursement environment — procedural coding stability: VCUG procedures continue to be reimbursed under established CPT codes (e.g., CPT 51600 for cystography injection and CPT 74455 for fluoroscopic supervision and interpretation). Consistency in coding reduces one major source of downstream revenue volatility, but regional payer differentials and episodic policy reviews require proactive payer engagement.
-
Regulatory pathway — device classification and market-entry cadence: VCUG catheters are regulated as Class II devices in major markets, typically subject to 510(k) premarket notification in the U.S. This pathway enables faster time-to-market for iterative device improvements while preserving regulatory risk that must be managed through disciplined clinical and bench testing strategies.
-
Clinical guidelines — demand concentration by indication: Guideline endorsements for VCUG in select pediatric populations create reliable clinical volumes in those cohorts. Strategic product and commercial plans that address pediatric procedural nuances will capture disproportionate value.
-
Technology substitution and workflow integration: Fluoroscopy systems, contrast media formulations, and catheter ergonomics form an interdependent buying decision in many facilities. Bundled value propositions and interoperability improvements are increasingly decisive in procurement conversations.
Competitive landscape: positioning and implications
The market is characterized by a mix of specialty device manufacturers and larger imaging and medtech players. Leading firms occupy complementary roles along the procedure stack — from dedicated VCUG catheters and low-friction intermittent catheters to contrast media and fluoroscopy systems. Representative capabilities include:
-
Cook Medical — established specialist in dedicated VCUG catheters, offering features optimized for pediatric and adult voiding cystourethrography (e.g., low-volume balloons, soft tips, radiopaque markers). Its product-centric depth supports channel and clinical training strategies.
-
Teleflex — provides traditional catheter platforms (rubber and silicone) that are widely accepted across catheterization workflows; Teleflex’s breadth favors scale-oriented customers and broad channel coverage.
-
Becton, Dickinson and Company (BD) — supplying balloon-tipped catheters used in pediatric applications; BD’s brand and distribution footprint make it a default incumbent in many hospital systems.
-
Coloplast A/S — brings hydrophilic-coated intermittent catheter technologies that reduce insertion friction; these design attributes address distinct clinical value levers around patient safety and ease-of-use.
-
GE Healthcare — as a producer of contrast media used in urinary tract opacification, GE occupies a higher-level systems role; its position highlights cross-sell opportunities between imaging consumables and imaging equipment upgrades.
Strategic read: the CR3/CR5 concentration metrics mean that while large incumbents control much of the accessible demand, differentiation in catheter design, consumable convenience, integrated supply agreements, and procedure-level service offerings are actionable levers for smaller innovators.
Practical, actionable content included in the full report
PW Consulting’s full study goes beyond descriptive narrative to deliver operational tools you can apply immediately:
-
Comprehensive forecasting model (2026–2032) with scenario toggles for adoption rates, reimbursement changes, and technology substitution effects.
-
Unit-volume and ASP (average selling price) assumptions by product family, calibrated to historical shipments and recent tender activity.
-
Payor and coding impact assessment, including sensitivity runs around CPT and payer-policy shifts.
-
Commercial playbooks — channel strategies, distributor contracting templates, and key opinion leader engagement plans tailored for hospitals, diagnostic centers, and specialty clinics.
-
Regulatory roadmap templates for 510(k) submissions and evidence generation plans that minimize approval timelines.
-
Merger & acquisition target screening criteria and a short list of potential tuck-in targets based on capability gaps identified in the competitive review.
-
Sample datasets and benchmarking dashboards that allow buyers to re-run the core market model using client-specific assumptions.
Note: This public preview intentionally omits granular segment and regional line items for tactical reasons. The full datasets, including segmentation-level revenue breakout tables and regional demand curves, are available in the complete report package on our website.
Strategic recommendations for 2026
-
Prioritize pediatric-focused product improvements and clinical value messaging. Given guideline-backed procedural volumes in pediatrics, pediatric-ready catheters and pediatric-focused commercial pilots can accelerate adoption and justify premium positioning.
-
Bundle consumables with service contracts. Buyers increasingly value integrated procurement that simplifies inventory and billing; a bundled model that ties catheters, contrast media access, and fluoroscopy service support can unlock higher lifetime value per account.
-
Engage payers early. Although CPT coding is stable, granular payer policies and prior-authorization workflows vary. Early payer engagement—particularly around bundled payments for pediatric diagnostic episodes—reduces downstream reimbursement friction.
-
Invest in regulatory-first design. Where product differentiation relies on incremental improvements, designing for an efficient 510(k) pathway and capturing bench and clinical evidence early will shorten commercialization cycles.
-
Use concentration to your advantage. For entrants, target procurement pathways where incumbents are weakest—service levels at diagnostic centers and specialty clinics, or bundled supply deals—rather than competing head-on in entrenched hospital systems.
How clients typically use this intelligence
Executives deploy the report across three primary decision-use cases: (1) new product prioritization — ranking development projects by expected ROI under the baseline and downside scenarios; (2) commercial strategy — designing pricing and channel strategies that reflect local reimbursement realities and buyer preferences; and (3) inorganic strategy — screening and valuing acquisition targets against a defensibility matrix derived from the report’s competitive and concentration analysis.
Next steps and how to access the full intelligence
This executive preview demonstrates the analytical depth and operational applicability of PW Consulting’s assessment. To execute against the recommended plays in 2026, teams will need access to the report’s full datasets, scenario model, and supplier scorecards. Visit our report page to obtain the complete Worldwide Voiding Cystourethrogram Market study, download sample exhibits, and request a tailored briefing where our analysts will run your organization’s assumptions through the model and deliver a bespoke implications memo.
Contact PW Consulting to schedule a private walkthrough and to receive the full dataset and commercial playbooks referenced in this preview. The full report contains the precise segmentation tables, regional breakouts, and unit-level assumptions withheld here to preserve the strategic “trailer” effect of this release.
For detailed analysis of this topic, please visit the official page: Worldwide Voiding Cystourethrogram Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts Worldwide Graphene Polymer Battery Market to Top USD 770.37 Million by 2032
By pmarketresearch, 2026-07-13
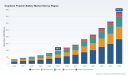
Worldwide Graphene Polymer Battery Market — Strategic Outlook for Corporate Decision‑Makers (PW Consulting, 2026)
PW Consulting's latest market intelligence briefing synthesizes the technical, commercial, and regulatory vectors reshaping the graphene‑polymer battery sector as companies enter a decisive 2026 planning window. Built on a 2025 base year and a granular 2026–2032 forecast horizon, the study quantifies a market that has expanded rapidly — from roughly USD 72.1 Million in 2020 to USD 195.4 Million in 2025 — and is projected to continue on a steep growth trajectory (compound annual growth rate: 21.65%). Our mid‑term model anticipates the market crossing the USD 240.8 Million mark in 2026 and approaching USD 770.4 Million by 2032. For executives allocating capital, identifying partners, or sizing technology risk, these topline dynamics create both a clear opportunity and a narrow window for strategic action.
Worldwide Graphene Polymer Battery Market
Why this report matters for 2026 decisions
-
Accelerated commercialization timelines. Breakthroughs in cell chemistry and composite components are compressing development cycles. Companies that convert lab gains into validated pilot units in 2026 will capture disproportionate commercial optionality in 2027–2029.
Worldwide Graphene Polymer Battery Market -
Capital allocation precision. With a market growing at ~22% CAGR, small differences in timing and scale of investment produce material differences in ROI. Our scenario models translate technology readiness levels into expected revenue phasing and cash‑flow impact across the 2026–2032 horizon.
Worldwide Graphene Polymer Battery Market -
Supply‑chain lock‑in risk. Graphene supply and functionalized nanoplatelets are formative inputs. Early procurement and qualification strategies materially reduce sourcing risk and cost volatility for OEMs and downstream integrators.
-
Regulatory and standards convergence. The emergence of ISO/TS frameworks (2025) and collaborative IEC/ISO workstreams is moving the market from fragmented practice toward common testing and characterization requirements — a shift that affects product claims, qualification timelines, and market access.
Market dynamics shaping strategy
-
Technology diversification — not a single winner yet: developments range from graphene‑enhanced lithium‑ion additives and conductive agents to aluminum‑ion architectures and graphene‑membrane assisted solid‑state concepts. Each class carries distinct TRLs (technology readiness levels), manufacturing implications, and cost pathways.
-
Scale economics and materials supply: manufacturing scale drives per‑unit cost declines for both graphene materials and graphene‑polymer composites. Notable capacity announcements and facility builds are already altering supplier bargaining power and should inform multi‑year procurement planning.
-
Standardization and testing: ISO/TS 9651:2025 and ISO/TS 23359:2025 establish a shared vocabulary and chemical characterization methods (XPS, TGA, ICP‑MS, FTIR) for graphene forms. Harmonized metrics are reducing technical ambiguity but will raise the bar for suppliers lacking robust analytical documentation.
-
Regulatory approvals as commercial enablers: public approvals under national schemes (examples include Australian and Canadian clearances for commercial graphene products) are increasingly prerequisites for large industrial engagements and public procurement.
What the PW Consulting report delivers — practical, decision‑ready content
-
Topline and scenario market sizing: multi‑year historical series and probabilistic forecasts that translate into revenue and TAM/SAM estimates for corporate planning (note: granular regional and application split tables are reserved for the full report).
-
Technology readiness and adoption maps: independent assessments of candidate chemistries and component solutions, including estimated qualification times and cost curves at pilot and commercial scale.
-
Supplier and partner scorecards: diligence templates covering production capacity, analytical compliance, IP status, and manufacturing readiness — formatted for use in RFPs and supplier qualification processes.
-
Commercial deployment playbooks: step‑by‑step guides for pilots, scale‑up, certification, and go‑to‑market sequencing adapted to OEMs, integrators, and material suppliers.
-
Manufacturing CAPEX/OPEX models and factory sizing templates: scenario tools that convert assumed yields, material costs, and scale into per‑unit economics across technology pathways.
-
M&A and partnership decision frameworks: valuation heuristics and deal structures tailored to acquiring material IP, licensing production technology, or securing supply‑chain exclusivity without overpaying for unproven scale.
-
Risk heatmaps and regulatory matrix: prioritized mitigation actions tied to standards, environmental health & safety, and cross‑border trade constraints.
Competitive landscape — who matters, and why
The sector combines early‑stage innovators with established materials companies moving into energy storage. Our analysis focuses on capabilities, technology pathways, and realistic commercialization timelines rather than headline claims alone.
-
Graphene Manufacturing Group (GMG) (Brisbane, Australia) — pursuing graphene aluminium‑ion (G+AI) cells and graphene additives. Recent technical updates indicate rapid charge capability in prototype cells and active capital deployment to scale second‑generation production. GMG’s positioning is significant for firms assessing non‑lithium chemistries and fast‑charge niches.
-
NanoXplore Inc. (Montreal, Canada) — commercial nanoplatelet production and silicon‑graphene anodes targeting safety and performance gains in EV and stationary storage. Large production volumes at NanoXplore level the playing field for large OEMs seeking qualified graphene additives.
-
Toray Industries and Sekisui Chemical (Tokyo, Japan) — incumbents in advanced composites and separators. Their polymer‑graphene composite capabilities are especially relevant for customers prioritizing mechanical strength, thermal resilience, and scalable manufacturing integration.
-
First Graphene (Perth, Australia) — supplier of high‑purity nanoplatelets with regulatory approvals. PureGRAPH and similar offerings are attractive to industrial users requiring compliance documentation for upstream procurement.
-
GQenergy (Italy) — developing solid‑state cells with graphene membranes and novel cell architectures that reduce recharge frequency. These concepts are of particular interest to defense and long‑duration energy storage buyers.
-
Global Graphene Group (G3), XG Sciences, Vorbeck, Graphenea — a mix of US and European material specialists supplying conductive additives, electrode components, and R&D grade materials. They form the supplier pool that OEMs will rely on during qualification and iterative product improvements.
Overall, the market exhibits a moderate degree of concentration: a handful of established materials firms and a smaller set of focused developers are setting technical and commercial baselines. For buyers and investors, this implies both clear shortlist candidates for qualification and continuing opportunities for niche innovators to capture capability gaps.
Strategic recommendations for 2026 — five priority moves
-
Initiate at least one supplier qualification pilot in 1H 2026. Use defined acceptance criteria aligned to ISO/TS characterization methods to avoid late‑stage disqualifications.
-
Lock incremental supply via multi‑year offtake or toll‑manufacturing agreements rather than seeking full upstream integration immediately — this preserves flexibility while securing material access.
-
Run dual technology tracks for 12–18 months: one focused on highest TRL graphene additives for near‑term product improvements; another on higher‑reward architectures (e.g., graphene aluminium‑ion or graphene‑enabled solid‑state) that require longer qualification.
-
Embed regulatory and standards readiness into product roadmaps. Pre‑emptive analytical packages and third‑party certification accelerate procurement cycles with risk‑averse customers.
-
Prepare acquisition and alliance playbooks now. With top players already scaling capacity and several specialized entrants in play, 2026–2027 will be the period of selective consolidation where deal discipline matters.
How to use this briefing in your 2026 planning cycle
Use this analysis as the strategic overlay to three operational workstreams: (1) product R&D prioritization, (2) sourcing and supplier qualification, and (3) capital allocation and partner selection. The full PW Consulting report supplies the granular segmented matrices, supplier scorecards, and financial models required to operationalize each recommendation and to quantify the tradeoffs between speed‑to‑market and technical ambition.
For companies evaluating entry, scale‑up, or acquisition in the graphene‑polymer battery value chain, 2026 is the year to move from exploratory partnerships to committed pilots and contractual protections. The market’s compound growth and evolving standards create a predictable runway for those who act with analytical rigor and procurement discipline.
To access the full dataset, regional and application splits, supplier benchmarking tables and the downloadable financial models that support these conclusions, consult the PW Consulting report page for the Worldwide Graphene Polymer Battery Market — the detailed intelligence is available in the full publication and accompanying data packet.
For detailed analysis of this topic, please visit the official page: Worldwide Graphene Polymer Battery Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com