

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
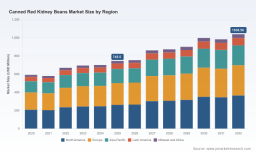
PW Consulting Predicts Worldwide Canned Red Kidney Beans Market to Reach USD 1,038.56 Million by 2032, Up from USD 745.5 Million in 2025 at a 4.85% CAGR

Worldwide Canned Red Kidney Beans Market — Strategic Outlook for 2026
Executive summary
PW Consulting’s new market brief on the Worldwide Canned Red Kidney Beans Market positions 2026 as a turning point for manufacturers, retailers and ingredient buyers. Using 2025 as the analytical base, the market is estimated at approximately USD 745.5 Million, and PW’s forecast models project a compound annual growth rate (CAGR) of 4.85% through 2032, pushing the global market above the USD 1 billion threshold by the end of the forecast horizon. This trajectory reflects a blend of structural demand for convenient plant-based protein, premiumization and channel evolution — balanced against cyclical input-cost pressures and an increasingly complex regulatory environment.
Worldwide Canned Red Kidney Beans Market
Why this matters for 2026 decision-makers
- Timing: 2026 will be the first year many post-pandemic adjustments — from new label regimes to sourcing shifts after the 2024–25 production shocks — feed directly into procurement and shelf assortment decisions.
- Financial planning: With a mid-single-digit CAGR baked into our base case, firms must align produkt and channel investments to capture share where unit economics improve, while stress-testing plans for commodity-driven cost shocks.
- Competitive positioning: Market concentration metrics indicate a moderate level of incumbent scale; nimble entrants and private-label programs can still outmaneuver larger players through channel-specific plays and innovation.
What the report delivers — practical, transaction-ready content
PW Consulting has structured the full report to be immediately actionable for corporate strategy, commercial operations and M&A teams. Highlights include:
Worldwide Canned Red Kidney Beans Market
- Top-down market sizing and our 2026–2032 forecast (by value), including sensitivity analyses around key macro variables.
- Channel economics and retailer margin models — SKU-level profitability frameworks for supermarkets, convenience formats, online retail and foodservice.
- Supply-side diagnostics: cost build-ups for canning operations, primary processing, and a raw-material sensitivity model that quantifies margin impact vs. bean-price movements.
- Regulatory and trade playbook: compliance checklists for new nutrition labeling, regional import duty scenarios and state-level chemical warning exposure.
- Competitive scorecards and supplier benchmarking — a reproducible template for auditing co-packers, contract terms and quality controls.
- M&A and partnership heat maps identifying strategic targets (scale, specialty, organic), with diligence checklists and valuation sensitivity modules.
- Go-to-market blueprints for three strategic options: premium brand expansion, private-label scale-up, and direct-to-consumer launches — with retail negotiation scripts and promotional ROI calculators.
Market dynamics and strategic risks
Several near-term and structural dynamics will shape outcomes in 2026:
Worldwide Canned Red Kidney Beans Market
- Input volatility: Dry red kidney bean prices rose sharply in early 2025; USDA data show average prices materially higher than the prior year after drought impacts in major producing regions. This requires active hedging, longer-term contracting and consideration of alternative bean sourcing to protect margins.
- Regulatory tightening: Nutrition labeling updates implemented by major regulators have altered per-serving disclosures and can influence perceived product value. Additionally, regional chemical exposure rules (e.g., California’s Proposition 65) create localized compliance and liability risk for certain formulations and processing residues.
- Trade barriers and cost of access: Tariff regimes and import classifications affect cross-border flows — some markets maintain non-trivial import duty rates for canned pulses. Companies with global ambitions must price for tariff drag or locate production strategically to avoid margin erosion.
- Channel acceleration: E‑commerce and value formats continue to gain share in many markets. Channel-specific SKUs and flexible packaging formats will be decisive for market share gains, while in-store promotional dynamics remain critical for shelf-centric buyers.
- Consolidation pressure: Market concentration metrics indicate that the leading firms hold a meaningful share of traded value, creating a dual dynamic — scale efficiencies for incumbents and opportunistic consolidation targets for acquirers seeking fast scale or capability fills.
Competitive landscape — where incumbents and challengers stand
The competitive field mixes large, legacy grocery brands with specialty organic and premium players. Our qualitative assessment identifies three repeatable positions:
- National scale brands that leverage broad retail relationships and national promotions to defend shelf space. These firms continue to invest in SKU hygiene (e.g., reduced-sodium variants) to respond to retailer and consumer health trends.
- Ethnic and regional specialists that capture high-loyalty consumer segments and use recipe-led marketing to maintain price premia in key markets.
- Organic and premium processors that command category differentiation through ingredient provenance, processing claims (no added salt, traditional methods) and sustainability narratives.
Notable industry movements reflect these positions: a leading US brand released a reduced-sodium variant in late 2024 to broaden retail penetration; a major Hispanic food company used trade-expo visibility in 2024 to underscore its organic portfolio; and several specialty processors continue to emphasize clean-label, low-intervention processing as a differentiation strategy. PW’s full profile set includes supplier scorecards and playbooks for countering each archetype.
Segmentation insight — what we analyze (and why we’re withholding the granular numbers here)
PW’s segmentation matrix examines the market by region, product type (conventional vs. organic), and distribution channel. For this release we present the high-level growth trajectory and structural drivers; detailed sub-segment figures are intentionally omitted from this public synopsis to preserve the strategic value of our proprietary datasets. The full dataset, available through PW Consulting, contains the exact breakdown by region, type and channel, plus channel-level CAGR curves and SKU economics used to inform assortment and pricing decisions.
How to convert insights into 2026 actions — a strategic playbook
For executive teams preparing their 2026 plans we recommend a three-step approach drawn from the report’s operational tools:
- Protect margin: implement the raw-material sensitivity model to define acceptable price corridors, renegotiate multi-year contracts with escalation clauses tied to transparent indices, and evaluate selective vertical integration for high-risk input nodes.
- Segment-to-win: use channel-specific SKU rationalization to remove low-performing SKUs and redeploy CAPEX into high-return formats (e.g., value multi-packs for discounters, premium single-serve for convenience and online).
- Mitigate regulatory and trade exposure: adopt a region-by-region compliance matrix, pre-clear label changes with large retail partners and model tariff pass-through scenarios to determine pricing strategies or production relocation needs.
Methodology, confidence and sources
PW Consulting’s analysis uses 2025 as the base year and draws on historical data for 2020–2025 to calibrate the models used to forecast 2026–2032. Our forecast incorporates: primary interviews with manufacturers, retailers and co-packers; trade and customs datasets; commodity price series; and regulatory databases. We publish confidence intervals around our base case and provide scenario outputs (upside/downside) to help clients stress-test strategic choices. Macro inputs referenced in this brief include official agricultural statistics and regulatory guidance that materially influence sourcing and labeling strategy.
Accessing the full report and datasets
This brief is intentionally designed as a strategic preview. The full Worldwide Canned Red Kidney Beans Market report contains the proprietary, tranche-level data and downloadable models required to execute the plays outlined above — including the granular regional and channel splits, SKU-level profitability sheets, supplier scorecards, and M&A heat maps. Organizations seeking to operationalize these insights for their 2026 planning cycle should contact PW Consulting to obtain the complete research package, bespoke scenario runs and facilitated strategy workshops.
Final note
As 2026 approaches, the canned red kidney beans market presents both durable demand tailwinds and idiosyncratic risks. Firms that marry disciplined cost management with targeted channel and product plays — informed by quantitative scenario analysis and practical operational tools — will be best positioned to convert market growth into sustainable margin improvement. PW Consulting’s full study provides the playbooks and data required to make those decisions with confidence.
For detailed analysis of this topic, please visit the official page: Worldwide Canned Red Kidney Beans Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com