

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Market in Full Bloom: PW Consulting Predicts Worldwide Handheld Leaf Area Meters to Expand at a 4.69% CAGR

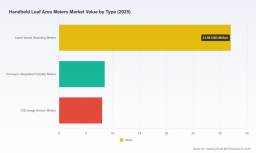
Worldwide Handheld Leaf Area Meters Market — Strategic Preview for 2026 Decision-Makers
Executive summary
PW Consulting’s latest market study on Worldwide Handheld Leaf Area Meters distills five years of historical performance (2020–2025) and delivers a forward-looking forecast through 2032. The handheld leaf area meter market demonstrated steady expansion from an estimated USD 38.7 million in 2020 to roughly USD 48.5 million in 2025. Our forecast points to continued, moderate growth at a compound annual growth rate (CAGR) of 4.69% across 2026–2032, culminating in an expected market size of approximately USD 66.9 million by 2032.
Worldwide Handheld Leaf Area Meters Market
This briefing is crafted as a strategic “trailer”: it surfaces the dynamics that will determine winners and losers in 2026, outlines where value pools will concentrate, and articulates the practical lines of action that procurement, R&D, and corporate strategy teams should prioritize. To preserve the full commercial utility of the study for subscribing organizations, detailed segment-level figures and granular regional splits are reserved for the full report.
Worldwide Handheld Leaf Area Meters Market
Why this market matters to 2026 corporate strategy
-
Precision agriculture and environmental monitoring are maturing into sustained procurement channels. Non-destructive, field-portable leaf area meters sit at the intersection of agronomy, plant breeding and ecology — disciplines that are increasingly data-driven and hardware-enabled.
Worldwide Handheld Leaf Area Meters Market -
The technology mix (laser scanning, CIS imaging, conveyor-integrated designs) is evolving from single-tool utility toward integrated sensor suites and workflow-native instruments that plug into digital field platforms. That technological transition is the principal vector for product differentiation over the next 18–36 months.
-
Market concentration is moderate: the top three players account for a meaningful share of industry revenues, while the top five widen that concentration further. This creates a landscape where scale advantages in distribution and validation credentials are decisive, but niche innovation can still win field adoption.
Technology and product architecture — what to watch
-
Laser-based scanning systems continue to be preferred for rapid, high-resolution measurements and are attractive in crop-science workflows that demand repeatable scans on attached leaves. Key product differentiators here are scan resolution, scan length, and integrated positioning or tagging (e.g., GPS) for geo-referenced datasets.
-
CIS (Contact Image Sensor) array products are making a renewed push in academic and botanical applications where shape fidelity and perimeter accuracy matter. Recent models from established manufacturers feature improved image-processing pipelines and ±2% area accuracy specifications that reduce post-processing overhead for researchers.
-
Conveyor-integrated or pallet-style designs have use cases in seed production and controlled-environment phenotyping labs. The convergence trend is toward modular hardware that supports both manual field use and semi-automated lab throughput.
-
Data interoperability and field-to-cloud workflows are now decisive. Instruments with easy USB/Excel export, automated tagging, and open data formats accelerate adoption among institutional buyers and commercial breeders who deploy high-throughput analytics.
Competitive landscape — profiles you need on your radar
The market is anchored by a small set of specialized manufacturers with deep product pedigrees and field validation records. Our report provides benchmarking of product families, go-to-market models, service capabilities and certification footprints. Highlights from primary players include:
-
CID Bio-Science (USA) — Offers wand and pallet-style handheld laser meters with capabilities for non-destructive measurement and high-resolution laser scanning. Their devices emphasize multi-parameter outputs (area, length, width, perimeter, shape metrics) and field tagging for geospatial research workflows.
-
LI-COR Environmental (Lincoln, NE, USA) — Known for lightweight, rapid-survey portable meters optimized for field surveys of attached and detached leaves, with high resolution and simple data export paths that appeal to agronomists and environmental researchers.
-
ADC BioScientific (UK) — Recently replaced an older model with a next-generation handheld scanner engineered for unlimited leaf length scanning and improved portability. Their AM400 launch represents a technology refresh that targets both research labs and field technicians.
-
Scitek Global (China) — Competes on field-spec robustness and certifications; their portfolio emphasizes long scan lengths and compliance with multiple regulatory standards that facilitate exports and institutional procurement.
-
BIOBASE Group (China) — Factory-direct supply models, touchscreen options and USB/Excel data transfer features make them a frequent consideration for price-sensitive institutional buyers seeking turnkey deployment.
Recent competitive movements also matter: for example, ADC BioScientific’s AM400 launch in late 2025 signals an upgrade cycle for replacement units, and several suppliers are emphasizing regulatory and product certifications as a way to lower procurement friction in clinical and institutional buyers.
Regulation, certification and field validation — operational enablers
-
Buyers increasingly request documented compliance and validation: product-level certifications (CE, ETL, FDA listings) and company-level management-system certifications (ISO 9001, ISO 13485, ISO 14001, ISO 45001) are frequently required for tenders and large institutional purchases.
-
Instruments with published accuracy and perimeter/area validation curves reduce field trial friction. Instruments certified to deliver ±2% area accuracy or similar are becoming de facto expectations in many research procurements, enabling faster institutional sign-off.
What the report delivers — practical, operational content
Beneath the headline forecasts, the PW Consulting report is structured to be directly actionable for executives and functional leaders. Key deliverables include:
-
Market sizing and CAGR through 2032, plus scenario modelling to test downside, base and upside assumptions against input-cost, raw material and adoption-rate sensitivities.
-
Go-to-market playbooks for OEMs and channel partners: pricing ladders, warranty and service strategies, distributor scorecards, and tender-readiness checklists.
-
Technology adoption roadmaps and product roadmaps that map sensor choices to buyer jobs-to-be-done across plant physiology, forestry, agronomy and botany use cases.
-
Field validation protocols, sample data templates and an open-data integration specification to accelerate pilot-to-deployment cycles for enterprise customers.
-
Supply-chain and manufacturing impact assessments, including lead-time scenarios, single-source risk heatmaps, and CAPEX/OPEX implications for scaling production.
-
M&A and partnership scouting: candidate profiles, valuation heuristics and integration risk checklists tailored to firms seeking inorganic expansion into adjacent phenotyping or sensing domains.
Strategic recommendations for 2026
-
Prioritize interoperability: product teams should make data-export and API integration first-class features. Buyers reward instruments that feed analytics pipelines without bespoke middleware.
-
Certify and validate early: secure relevant product and corporate certifications to shorten procurement cycles, particularly for institutional and cross-border tenders.
-
Segment go-to-market by buyer persona rather than by geography alone: breeding houses, academic labs, forestry services and environmental NGOs have different procurement cadences and after-sales expectations.
-
Invest selectively in hybrid offerings: combine laser/CIS sensor options with a modular approach so single SKUs can be configured for high-throughput labs or rugged fieldwork, reducing SKU proliferation while expanding addressable use cases.
-
Use certification and published accuracy as pricing levers: devices with independently verified accuracy curves command price premiums and accelerate institutional adoption.
-
Prepare for consolidation: moderate market concentration means well-capitalized buyers can gain scale advantages. Attractive inorganic targets often possess validated technology, niche channels, or certification portfolios.
How to use this research in your 2026 planning cycle
For executives building 2026 budgets and three-year strategic plans, the study provides the analytical foundation to allocate R&D dollars, plan capacity expansions, design channel incentives and prioritize certifications. Functional teams will find the field-validation kits and procurement templates immediately useful for tender responses and pilot deployments.
PW Consulting’s public summary above highlights the structural forces shaping supplier economics and buyer behavior. The complete study contains the detailed models, scenario tables and segment-level analytics that allow teams to run bespoke sensitivity analyses and prepare executable roadmaps. Accessing the full report will enable you to extract the precise segmented intelligence, regional demand projections and product-level benchmarks necessary for transaction-level decisions.
Next steps
For licensing the full Worldwide Handheld Leaf Area Meters Market report, tailored briefings, or a bespoke workshop to translate the findings into an actionable 90‑day tactical plan for your organization, please contact PW Consulting. The report’s depth is designed to move teams from insight to implementation within a single quarter.
For detailed analysis of this topic, please visit the official page: Worldwide Handheld Leaf Area Meters Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com