

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
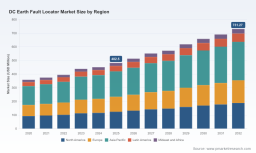
PW Consulting: Worldwide DC Earth Fault Locator Market to grow from USD 482.5 Million in 2025 to USD 731.27 Million by 2032 at a 6.12% CAGR — Asia Pacific leads with USD 186.0M, portable units dominate; top‑5 firms hold 47.65%

Worldwide DC Earth Fault Locator Market — Strategic Briefing for 2026 Decision‑Makers
Executive summary
PW Consulting’s new market study on the Worldwide DC Earth Fault Locator Market synthesizes five years of historic performance and a seven‑year forecast to deliver a decision‑grade intelligence package for corporate leaders planning actions in 2026. The market has expanded steadily from a base in 2020 through 2025: our audited historical series shows growth from roughly USD 358 million in 2020 to USD 482.5 million in the base year 2025, and the market is projected to continue expanding at a compound annual growth rate (CAGR) of 6.12% over the 2026–2032 forecast window, reaching an estimated USD 731.3 million by 2032.
Worldwide DC Earth Fault Locator Market
This briefing highlights the elements of the report that most directly influence executive decisions in 2026—procurement cycles, product roadmaps, compliance, M&A screening, and supply‑chain resilience—while preserving the granular regional, application and vendor share tables for report purchasers who need the full dataset.
Worldwide DC Earth Fault Locator Market
Why this report matters for strategies executed in 2026
- Capital planning and procurement: Utilities and large industrial buyers face near‑term inspection and retrofit cycles driven by regulatory schedules and asset‑life planning. Accurate top‑line market sizing and a clear forecast trajectory help procurement teams time tenders and capital releases to minimize inventory and avoid premium sourcing.
- Product and R&D prioritisation: The report identifies where demand for online, non‑invasive locators versus portable instruments is accelerating, enabling product teams to prioritize features such as high‑resistance detection, low‑frequency injection, and AC‑noise immunity that materially affect field acceptance.
- Compliance and maintenance optimization: Standards and mandatory inspection cadences increase the value of online monitoring solutions that do not require de‑energization. The study links regulation timelines to addressable demand, enabling compliance officers to make the business case for continuous monitoring versus periodic testing.
- M&A and partnership screening: With market concentration measured and mapped (the three‑firm concentration cluster is modestly material), corporates can evaluate acquisitive growth and strategic alliances against realistic competitive benchmarks and synergy expectations.
Market dynamics: drivers, constraints and inflection points
- Regulatory cadence: Enforcement and inspection standards for battery and DC power systems—such as regular inadvertent ground inspections—are prompting demand for online systems that can operate without system interruption. This regulatory push materially alters lifecycle economics for owners of floating DC systems.
- Power system architecture changes: The global acceleration of DC architectures—microgrids, renewables with DC coupling, telecom power systems, and battery‑backed infrastructure—expands the number of end points that require reliable ground fault detection. These structural shifts underpin the long‑term CAGR observed in our forecast.
- Technology and product trends: The market is bifurcating between portable testers optimized for field fault tracing and always‑on online monitoring platforms that integrate into asset management stacks. Advances in signal processing, sensor miniaturization and wireless telemetry are increasing the value proposition of real‑time fault location.
- Supply‑side risk: DC earth fault locators rely on semiconductors, precision current sensors, and lithium‑based power modules. Global semiconductor cycles and component lead times therefore influence pricing and delivery risk—an important consideration for sourcing teams in 2026.
- Standards and safety compliance: Compliance with IS/IEC‑equivalent standards and industry test protocols remains a gating factor for adoption in regulated sectors (power utilities, rail, marine). Products that demonstrate compliance with these standards shorten procurement lead times and reduce field commissioning risk.
Competitive landscape snapshot — who matters and why
The competitive field includes a mix of specialised instrumentation manufacturers, regional system integrators, and broader test‑instrument brands. Market concentration metrics show room for scale consolidation: the top three firms account for a meaningful but not dominant share of the market, and the top five firms capture under half of industry revenues—indicating significant fragmentation and white space for strategic entrants or bolt‑on acquisitions.
Worldwide DC Earth Fault Locator Market
- Bender GmbH & Co. KG: Positioned as a systems‑oriented provider with online automatic location solutions that integrate into DCIM and facility management workflows. Strategic partnerships extending into DC infrastructure management increase their appeal to data centres and large utilities.
- Kehui International Limited: A Chinese manufacturer focused on battery and low‑voltage DC systems with feature sets emphasizing high‑resistance detection and wireless reporting—a practical choice for high‑volume, low‑cost deployments in telecom and industrial sites.
- Eagle Eye Power Solutions: US‑based company with product offerings aligned to regulatory compliance needs (e.g., meeting battery inspection mandates), leveraging low‑frequency injection approaches to locate faults without taking systems offline.
- HJ Arnett Industries: Specialized in sensitive detection for critical installations (nuclear, marine, refineries), with devices engineered for extremely low‑current fault detection to support safety‑critical maintenance regimes.
- Megger and other established test‑equipment brands: Offer modular platforms with strong training/documentation ecosystems and global distribution—advantages in noisy‑signal environments and larger enterprise accounts.
- Regional and niche players: Several firms in Asia and India supply portable and export‑oriented models, filling demand for on‑site diagnostics and complementing global vendors with competitive price‑performance tradeoffs.
Recent vendor developments shaping 2026 decisions
- Bender’s 2025 partnership and DCIM demonstrations indicate a newer tend toward integrated asset management solutions—an important signal for buyers that value data interoperability and long‑term TCO reduction.
- Megger’s sustained investment in user education, documented in 2025 product guides and training resources, is reducing buyer risk associated with field adoption and improving time‑to‑competence for service organisations.
- Regional trade show activity in 2025—where multiple vendors showcased high‑noise immunity devices—confirms that manufacturers are prioritizing field robustness to win specification‑driven contracts in utilities and rail.
What’s inside the report: operationally useful deliverables
The report is intentionally structured for immediate operational use by procurement, engineering and strategy teams. Key inclusions:
- Transparent market sizing and forecasting (historical 2020–2025; base year 2025; forecast 2026–2032) with scenario sensitivity that models alternative growth paths under varying policy and component‑supply assumptions.
- Vendor benchmarking templates and a scored supplier matrix covering technical capability, field service footprint, compliance posture, and integration maturity—designed for RFP shortlisting.
- Procurement playbooks that translate technical specification needs into contract language, acceptance test scripts and training requirements to de‑risk deployments.
- Use‑case economics for five representative end markets (from substations and utilities to renewable plants and telecom), showing expected payback windows for portable versus online solutions.
- Supply‑chain heatmaps and mitigation plans that link component sourcing risk (semiconductor exposure, battery modules) to lead‑time and cost contingencies.
- Scenario planning worksheets and M&A screening criteria for corporate development teams evaluating tuck‑ins or strategic partnerships.
Strategic implications and recommended moves for 2026
- Buyers (utilities, large enterprises): Prioritise online fault‑location capabilities in new procurements where continuous availability and regulatory inspection cadence drive lifecycle cost savings. Use the report’s RFP templates to standardise acceptance tests and limit vendor lock‑in.
- Vendors and OEMs: Invest selectively in interoperability (DCIM/APIs), noise‑suppression algorithms, and field training services—features shown to accelerate adoption in large critical‑infrastructure accounts. Consider partnerships with DCIM and asset‑management vendors to move up the value chain.
- Private equity and strategic acquirers: The market fragmentation and sub‑50% share of the top five firms create clear M&A playbooks: pursue bolt‑ons that add regional distribution, service capability, or complementary sensing technology to scale quickly.
- Service organisations and system integrators: Differentiate with turnkey offerings—hardware plus installation, monitoring, and SLA‑backed analytics—to capture recurring service revenue and reduce customer churn.
- Policy and compliance teams: Use the market’s regulatory alignment data to inform capital allowances and compliance budgets; early investment in online locators can reduce both inspection disruption and long‑term insurance exposure.
Methodology and transparency
The report’s base year is 2025 and it draws on a blended methodology combining primary interviews, vendor financials, equipment shipment proxies and end‑market consumption models. Our forecast extends 2026–2032 and uses a central case CAGR of 6.12%. Market concentration metrics and competitive profiles are presented with auditable scoring so buyers and investors can reproduce the logic behind vendor ratings.
Where we intentionally withhold detail — and why
Consistent with the report’s role as both an analytical product and a commercial dataset, this press briefing presents the high‑level market trajectory, regulatory drivers and competitive positioning that readers need to validate near‑term strategy. We intentionally reserve the full regional/Application‑level splits, granular vendor market shares, and downloadable data tables for the report package and interactive dashboards available on the source page—these granular datasets are the actionable assets that procurement teams, product managers and M&A groups will use to execute in 2026.
If your 2026 planning requires precise regional demand curves, application‑specific unit economics, vendor share matrices or downloadable procurement artifacts, PW Consulting’s full Worldwide DC Earth Fault Locator Market report and datapacks provide those deliverables with raw tables, modeling workbooks and editable vendor scoring sheets.
To request the full report, licensing options or a tailored briefing based on the dataset, visit the PW Consulting report page or contact our Research Sales team. Our analysts are available to run bespoke scenarios that incorporate your asset base, inspection cadence and procurement constraints to produce a customised investment roadmap for 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Worldwide DC Earth Fault Locator Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com