

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Voiding Cystourethrogram Market to Expand from USD 645.5 Million in 2025 to USD 890.27 Million by 2032 at a 4.7% CAGR

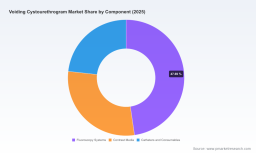
Worldwide Voiding Cystourethrogram (VCUG) Market: Strategic Imperatives for 2026 — Executive Preview
PW Consulting’s latest market study on the Worldwide Voiding Cystourethrogram (VCUG) market provides a decisive intelligence asset for executives making capital-allocation, product, and market-entry decisions in 2026. Anchored on a 2025 base-year and a seven-year forecast horizon (2026–2032), the report combines granular primary research, proprietary demand models, and regulatory and reimbursement mapping to help stakeholders convert clinical trends into commercial advantage.
Worldwide Voiding Cystourethrogram Market
Why this report matters for 2026 decision cycles
-
Market timing and resource allocation: Our forecast and scenario matrices translate the market’s mid-single-digit compound annual growth trajectory into tangible revenue and volume paths, enabling CFOs and business-unit heads to stress-test capex plans against plausible outcomes.
Worldwide Voiding Cystourethrogram Market -
Regulatory and reimbursement clarity: With procedural reimbursement and device classification shaping adoption curves, the report synthesizes the operational implications of prevailing CPT codes and device pathways so pricing, coding, and market-access teams can reduce approval and reimbursement risk.
Worldwide Voiding Cystourethrogram Market -
Competitive posture: The research maps concentration metrics and functional differentiation across the value chain, clarifying where incumbents are entrenched and where disruptive entrants can build defensible niches.
Market snapshot (historical context and forecast)
VCUG market activity has shown steady expansion in the 2020–2025 historical window, reflecting sustained clinical demand and incremental technology upgrades across diagnostic imaging suites. PW Consulting’s modeled total market size (USD, Million) traces this progression annually, culminating in a 2025 base-year market of USD 645.5 Million. Under our baseline scenario, the market is projected to grow to USD 669.3 Million in 2026 and follow a steady upward trajectory through 2032, reaching USD 890.27 Million by the end of the forecast period. The implied compound annual growth rate for 2026–2032 is 4.7%.
Two quantitative context points are critical for strategic planning: first, the market’s structural concentration (CR3 of 42.5% and CR5 of 58.8%) indicates that a small set of established suppliers collectively hold a majority share of commercial activity; second, demand is driven by a combination of legacy installed base refresh cycles, ongoing pediatric diagnostic needs, and procedural reimbursement stability in key markets.
Dynamics shaping 2026–2032
-
Reimbursement environment — procedural coding stability: VCUG procedures continue to be reimbursed under established CPT codes (e.g., CPT 51600 for cystography injection and CPT 74455 for fluoroscopic supervision and interpretation). Consistency in coding reduces one major source of downstream revenue volatility, but regional payer differentials and episodic policy reviews require proactive payer engagement.
-
Regulatory pathway — device classification and market-entry cadence: VCUG catheters are regulated as Class II devices in major markets, typically subject to 510(k) premarket notification in the U.S. This pathway enables faster time-to-market for iterative device improvements while preserving regulatory risk that must be managed through disciplined clinical and bench testing strategies.
-
Clinical guidelines — demand concentration by indication: Guideline endorsements for VCUG in select pediatric populations create reliable clinical volumes in those cohorts. Strategic product and commercial plans that address pediatric procedural nuances will capture disproportionate value.
-
Technology substitution and workflow integration: Fluoroscopy systems, contrast media formulations, and catheter ergonomics form an interdependent buying decision in many facilities. Bundled value propositions and interoperability improvements are increasingly decisive in procurement conversations.
Competitive landscape: positioning and implications
The market is characterized by a mix of specialty device manufacturers and larger imaging and medtech players. Leading firms occupy complementary roles along the procedure stack — from dedicated VCUG catheters and low-friction intermittent catheters to contrast media and fluoroscopy systems. Representative capabilities include:
-
Cook Medical — established specialist in dedicated VCUG catheters, offering features optimized for pediatric and adult voiding cystourethrography (e.g., low-volume balloons, soft tips, radiopaque markers). Its product-centric depth supports channel and clinical training strategies.
-
Teleflex — provides traditional catheter platforms (rubber and silicone) that are widely accepted across catheterization workflows; Teleflex’s breadth favors scale-oriented customers and broad channel coverage.
-
Becton, Dickinson and Company (BD) — supplying balloon-tipped catheters used in pediatric applications; BD’s brand and distribution footprint make it a default incumbent in many hospital systems.
-
Coloplast A/S — brings hydrophilic-coated intermittent catheter technologies that reduce insertion friction; these design attributes address distinct clinical value levers around patient safety and ease-of-use.
-
GE Healthcare — as a producer of contrast media used in urinary tract opacification, GE occupies a higher-level systems role; its position highlights cross-sell opportunities between imaging consumables and imaging equipment upgrades.
Strategic read: the CR3/CR5 concentration metrics mean that while large incumbents control much of the accessible demand, differentiation in catheter design, consumable convenience, integrated supply agreements, and procedure-level service offerings are actionable levers for smaller innovators.
Practical, actionable content included in the full report
PW Consulting’s full study goes beyond descriptive narrative to deliver operational tools you can apply immediately:
-
Comprehensive forecasting model (2026–2032) with scenario toggles for adoption rates, reimbursement changes, and technology substitution effects.
-
Unit-volume and ASP (average selling price) assumptions by product family, calibrated to historical shipments and recent tender activity.
-
Payor and coding impact assessment, including sensitivity runs around CPT and payer-policy shifts.
-
Commercial playbooks — channel strategies, distributor contracting templates, and key opinion leader engagement plans tailored for hospitals, diagnostic centers, and specialty clinics.
-
Regulatory roadmap templates for 510(k) submissions and evidence generation plans that minimize approval timelines.
-
Merger & acquisition target screening criteria and a short list of potential tuck-in targets based on capability gaps identified in the competitive review.
-
Sample datasets and benchmarking dashboards that allow buyers to re-run the core market model using client-specific assumptions.
Note: This public preview intentionally omits granular segment and regional line items for tactical reasons. The full datasets, including segmentation-level revenue breakout tables and regional demand curves, are available in the complete report package on our website.
Strategic recommendations for 2026
-
Prioritize pediatric-focused product improvements and clinical value messaging. Given guideline-backed procedural volumes in pediatrics, pediatric-ready catheters and pediatric-focused commercial pilots can accelerate adoption and justify premium positioning.
-
Bundle consumables with service contracts. Buyers increasingly value integrated procurement that simplifies inventory and billing; a bundled model that ties catheters, contrast media access, and fluoroscopy service support can unlock higher lifetime value per account.
-
Engage payers early. Although CPT coding is stable, granular payer policies and prior-authorization workflows vary. Early payer engagement—particularly around bundled payments for pediatric diagnostic episodes—reduces downstream reimbursement friction.
-
Invest in regulatory-first design. Where product differentiation relies on incremental improvements, designing for an efficient 510(k) pathway and capturing bench and clinical evidence early will shorten commercialization cycles.
-
Use concentration to your advantage. For entrants, target procurement pathways where incumbents are weakest—service levels at diagnostic centers and specialty clinics, or bundled supply deals—rather than competing head-on in entrenched hospital systems.
How clients typically use this intelligence
Executives deploy the report across three primary decision-use cases: (1) new product prioritization — ranking development projects by expected ROI under the baseline and downside scenarios; (2) commercial strategy — designing pricing and channel strategies that reflect local reimbursement realities and buyer preferences; and (3) inorganic strategy — screening and valuing acquisition targets against a defensibility matrix derived from the report’s competitive and concentration analysis.
Next steps and how to access the full intelligence
This executive preview demonstrates the analytical depth and operational applicability of PW Consulting’s assessment. To execute against the recommended plays in 2026, teams will need access to the report’s full datasets, scenario model, and supplier scorecards. Visit our report page to obtain the complete Worldwide Voiding Cystourethrogram Market study, download sample exhibits, and request a tailored briefing where our analysts will run your organization’s assumptions through the model and deliver a bespoke implications memo.
Contact PW Consulting to schedule a private walkthrough and to receive the full dataset and commercial playbooks referenced in this preview. The full report contains the precise segmentation tables, regional breakouts, and unit-level assumptions withheld here to preserve the strategic “trailer” effect of this release.
For detailed analysis of this topic, please visit the official page: Worldwide Voiding Cystourethrogram Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com