

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting: Worldwide Smart-connected Wallets Market Set to Expand at 8.2% CAGR Through 2032
By pmarketresearch, 2026-07-15
Worldwide Smart-connected Wallets Market: Strategic Briefing for 2026 Decisions
Executive snapshot
The smart-connected wallet has moved beyond novelty to become a commercially meaningful category. Our new market assessment shows the global market expanded from roughly USD 295 million in 2020 to about USD 420 million in 2025, and is projected to grow at a compound annual growth rate (CAGR) of 8.2% through the 2026–2032 forecast window, reaching an addressable market approaching three-quarters of a billion USD by 2032. For corporate leaders planning product roadmaps, partnerships, or M&A activity in 2026, these topline dynamics demand concrete strategic responses: protect IP and data flows, choose tracking and security technology stacks judiciously, and align channel models with evolving consumer purchase behaviors.
Worldwide Smart-connected Wallets Market
Why this report matters to 2026 decision-makers
-
Validated growth trajectory: The trajectory from 2020–2025 confirms a transition from early-adopter volumes to mainstream demand. That shift alters the calculus for investments in scale, manufacturing automation, and after-sales support.
Worldwide Smart-connected Wallets Market -
Actionable foresight, not just numbers: Executives need practical roadmaps for product architecture, partner ecosystems, and regulatory compliance; the right strategic choices in 2026 will lock in multi-year competitive advantage.
Worldwide Smart-connected Wallets Market -
Complexity at the nexus of hardware, firmware, and services: Smart wallets combine materials, RF/Bluetooth tracking, biometric security, cloud services and app ecosystems—decisions about which layer to own versus outsource are central to profitability and defensibility.
What PW Consulting’s report delivers (practical, operational intelligence)
Our research is designed as an implementation playbook for product, commercial, and corporate strategy teams. The report blends proprietary market sizing with operational templates and decision frameworks that executives can deploy immediately:
-
Technology selection matrix—trade-offs between low-power Bluetooth tracking, RFID shielding, and biometric subsystems tied to cost, battery life, regulatory exposure, and user experience priorities.
-
Vendor scorecards—comparative assessments of component suppliers, tracker integrators, and firmware providers keyed to longevity, update policies, and data governance practices.
-
Go-to-market playbooks—channel mix scenarios, pricing architectures, and subscription vs. one-time revenue models, with customer acquisition cost and lifetime-value stress tests tailored to three archetypal go-to-market strategies.
-
Compliance and privacy checklists—concrete controls and contractual language recommended for 2026 procurement and partnership agreements in light of recent data-security rules.
-
M&A and JVS playbooks—how to evaluate tuck-in acquisitions (trackers, biometric modules, firmware houses) and when to favor strategic alliances over ownership to accelerate time-to-market.
-
Scenario planning and sensitivity models—three demand scenarios (base, fast-adoption, and constrained-growth) with explicit inflection points for capex, inventory, and service support.
Competitive landscape: who matters and what they signal
The smart-wallet arena is populated by a mix of design-driven premium brands, specialist hardware suppliers, and integrators that bridge accessory design with connected services. Market concentration data indicate a moderately fragmented field—market leadership is meaningful but not dominant, leaving opportunity for differentiated entrants and smart consolidation plays.
-
Ekster (Netherlands) —Positions itself at the premium end with integrated rechargeable Bluetooth trackers compatible with mainstream ecosystem location services. Their model demonstrates a profitable premiumization path: design-led leather goods coupled with replaceable or rechargeable tracking modules, and a clear focus on ecosystem compatibility (Apple Find My, Android).
-
iWallet Corporation (United States) —A firm to watch in 2025–26. Their recent product activity (the iClutch launch and the announced iWallet 2.0 flagship) signals an aggressive push on aerospace-grade materials, advanced tracking and biometric security. iWallet also offers consulting services—an indicator of monetizing IP beyond hardware and into advisory and integration revenue.
-
Bellroy (Fitzroy, Australia) —A model for premium minimalism and brand-driven lifecycle value. Their emphasis on high-quality materials with optional tracking integrations shows how established accessory brands can extend into connected experiences without fully owning the electronics stack.
-
Dango Products (Palo Alto) —Exemplifies a durable, modular hardware approach, targeting consumers who prioritize ruggedness and component interchangeability.
-
Arista Vault (Gurgaon) —Focuses on ‘vault-style’ security, underscoring the demand segment for higher-assurance storage and anti-tamper design—relevant for customers managing higher-value physical and digital assets.
-
Groove Life, The Ridge, Nomad, Innway —Collectively these players illustrate vendor specialization: some bring tight ecosystem integrations (e.g., Apple Find My), others provide metal minimalist hardware, card trackers, or white-label tracker modules. Their presence emphasizes modular strategies for companies that want fast time-to-market by integrating third-party trackers.
Recent product and technology developments—implications for 2026
-
Product cadence matters: iWallet’s sequences of launches in 2025 reflect an industry move toward higher-spec materials and stronger tracking/biometric claims. Executives must assess whether to compete on hardware differentiation or to compete on ecosystem/service monetization.
-
DeFi and on-chain security experiments (e.g., AI agent security wallets) indicate an emerging intersection between smart wallets and fintech use cases; firms targeting digital-asset users need architecture that isolates keys, supports secure enclaves, and offers verifiable transaction paths.
-
Tracker integration strategies are diversifying: companies are balancing proprietary tracker development against leveraging platform-native services (e.g., major smartphone ecosystem location services). The choice will affect margins, upgrade paths, and data governance obligations.
Regulatory and geopolitical dynamics to bake into 2026 plans
Two regulatory developments in 2025 materially change the risk landscape for connected-wallet businesses:
-
The U.S. Department of Justice’s Data Security Program rules (effective April 2025) impose restrictions on bulk transfers of certain sensitive personal data to specified jurisdictions. For companies with cloud-dependent services, firmware update flows, or third-party analytics, this requires immediate re-engineering of data residency, consent flows, and contractual safeguards.
-
A 2025 court ruling on net neutrality oversight—shifting significant authority to Congress and states—creates uncertainty for service-level agreements that depend on network-layer guarantees. Firms that embed wallet services into broader connectivity offerings should evaluate resilience strategies that do not assume uniform network behavior across jurisdictions.
Operationally, these pressures favor architectures that minimize persistent personal data collection, favor device-resident keys and ephemeral telemetry, and adopt privacy-preserving analytics models. Procurement teams must now include cross-border-data and lawful-basis checks as a standard gating item.
Strategic recommendations for 2026
-
Prioritize data minimization and modular privacy: Implement edge-first designs where possible—store identity artifacts and biometric templates on-device, limit cloud dependency for core security functions, and adopt transparent user consent models.
-
Make a clear build-or-buy decision by component: For trackers and firmware, assess total-cost-of-ownership for proprietary development versus partnering with specialist suppliers; for biometric modules, favor suppliers with long-term OTA update commitments and robust vulnerability disclosure policies.
-
Differentiate via services: With hardware converging, services (lost-item workflows, indemnity, premium support, and digital-key management) will be critical to lift ARPU and increase retention.
-
Design for regulatory agility: Implement data localization options and modular cloud endpoints to enable fast re-routing of data flows in response to shifting legal constraints.
-
Prepare M&A and alliance playbooks: Identify targets that close capability gaps—trackers, secure element providers, or app/analytics platforms—and be ready to execute tuck-ins that accelerate time-to-market in 12–18 months.
How PW Consulting’s deliverables support these actions
The report supplies the exact artifacts needed to operationalize the recommendations above: procurement RFIs and scoring templates, legal-first contract clauses tailored to new data rules, supplier due-diligence checklists, and a prioritized roadmap that converts market scenarios into quarterly milestones for product, legal, and go-to-market teams.
Conclusion and call to action
Smart-connected wallets are at an inflection point where product differentiation, data governance, and channel execution will determine winners and losers. The market’s healthy mid-single-digit CAGR and near-term growth make 2026 a pivotal year to decide whether to scale, partner, or specialize. PW Consulting’s Worldwide Smart-connected Wallets Market report arms leaders with the strategic frameworks and executable tools required to translate market opportunity into sustainable advantage.
To download the full report, including our proprietary segmentation models, vendor scorecards, and scenario spreadsheets, visit the PW Consulting report page and access the dataset behind these insights. For tailored strategy sessions and bespoke market briefs calibrated to your company’s risk appetite and role in the value chain, contact our Smart Devices & Wearables practice.
For detailed analysis of this topic, please visit the official page: Worldwide Smart-connected Wallets Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Enzymes for Biofuels Market to Reach USD 1.89 Billion in 2025, Poised for 6.51% CAGR Through 2026–2032
By pmarketresearch, 2026-07-15
Worldwide Enzymes for Biofuels Market — Strategic Outlook 2026: What Global Energy and Industrial Leaders Need to Know
Executive preview
As energy transition pathways accelerate, enzymatic solutions for biofuels are moving from niche technical enablers to strategic levers for decarbonization, cost reduction and feedstock diversification. PW Consulting’s latest market study — built on a 2020–2025 historical baseline and projecting through 2026–2032 — quantifies this shift and translates it into decision-ready insight for executives, investors and policy teams preparing plans in 2026.
Worldwide Enzymes for Biofuels Market
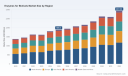
The worldwide market for enzymes used in biofuel production grew from roughly USD 1.38 billion in 2020 to about USD 1.89 billion in 2025, and our forecast sees continued expansion to nearly USD 2.93 billion by 2032, reflecting a compound annual growth rate (CAGR) of 6.51% across the 2026–2032 projection window. These headline trajectories underline two simultaneous realities: steady baseline demand from established starch-based ethanol value chains, and accelerating upside from second‑generation (lignocellulosic) and enzymatic biodiesel routes as policy, feedstock innovation and enzyme engineering converge.
Worldwide Enzymes for Biofuels Market
Why this study matters for 2026 decision cycles
- Actionable timing (2026 as the inflection year): regulators and obligation frameworks set for 2026–2027 create a new planning horizon for procurement, capex and product development — our modeling maps those policy pivots to enzyme demand, margin outcomes and ROI windows.
- Risk-to-return triage for management teams: by quantifying technology, feedstock and market concentration risks, the report enables portfolio managers to prioritize investments with the best probability-adjusted returns.
- M&A and partnership surfacing: given the market’s concentrated supplier base, the analysis identifies capability gaps and high-value acquisition archetypes that can accelerate entry into advanced biofuels or broaden enzyme capability sets.
What the report contains — practical, consultative deliverables
This is not a catalog of numbers alone. The report is structured as a practitioner’s toolkit for 2026 action:
Worldwide Enzymes for Biofuels Market
- Market sizing and trenddrivers: end-to-end revenue trajectory from 2020 through our forecast horizon, with scenario modeling that isolates policy, raw material and technology adoption impacts on enzyme demand.
- Commercial and procurement playbooks: term structures, volume-flex clauses and pricing levers that buyers can use to mitigate volatility in enzyme input costs and raw material feedstocks.
- Technology readiness and value-chain roadmaps: comparative assessment of enzyme classes, process integration options, and likely deployment timelines for advanced cellulases and enzymatic transesterification at scale.
- Supply‑chain and input-cost stress tests: maps and simulations that show sensitivity to fermentation feedstock prices and the knock-on effects on manufacturer margins and cost pass-through to biofuel producers.
- Competitive and M&A diligence frameworks: profiles, capability matrices and acquisition target archetypes to accelerate internal evaluation and speed up diligence.
- Regulatory impact matrices and scenario playbooks: policy levers (including pending and published volumes under renewable fuel standards) translated into demand shocks and compliance cost curves.
- Customized advisory annexes: playbook modules for investors, midstream ethanol producers, integrated oil and gas companies evaluating biofuel conversion, and bioprocess equipment OEMs.
Competitive landscape — strategic implications of a concentrated supplier base
The enzyme-for-biofuels sector shows high market concentration, with our analysis indicating that the top three providers account for roughly two‑thirds of supply and the top five exceed four‑fifths of the market. That concentration has three practical effects for 2026 decision-making:
- Price and availability discipline: dominant suppliers can set commercial terms and prioritize contract fulfillment for strategic partners; buyers should prepare hedging and contracting strategies rather than rely on spot procurement.
- Innovation funnel control: large, integrated enzyme firms remain the primary investors in R&D, but targeted partnerships and licensing remain viable routes to access advanced capabilities quickly.
- Acquisition and counterparty risk: consolidation events or strategic exits can rapidly reconfigure competitive dynamics; monitoring M&A activity is essential for both suppliers and purchasers.
Key supplier profiles in the report synthesize market position, product strategy and strategic levers. Highlights include:
- Novonesis (formerly Novozymes) — a market leader offering comprehensive enzyme and yeast portfolios for both starch-based and fiber-based ethanol. Its strength is end-to-end process solutions (liquefaction, saccharification, biomass conversion) and sustainability positioning to reduce producers’ carbon footprints.
- Lallemand Biofuels & Distilled Spirits (LBDS) — following its acquisition of BASF’s bioenergy enzymes business in 2024, LBDS’s product set and developmental pipeline (including brand portfolios like Spartec®) enhance its relevance to grain processors and fuel ethanol producers.
- DuPont (Industrial Biosciences / IFF) — technology-driven offerings such as Accellerase emphasize lignocellulosic hydrolysis and starch processing efficiency; DuPont’s capabilities are optimized for scale deployments in corn- and cellulosic-based value chains.
- Regional and specialist players — firms like AB Enzymes, DSM‑Firmenich (Health & Biosciences), Codexis and a cohort of Indian, Japanese and North American specialists contribute differentiated capabilities: lower-cost formulations, engineered biocatalysts, lipase-driven biodiesel routes, and feedstock-integrated enzyme approaches.
The report examines how these providers compete across three dimensions: technical performance (e.g., activity per dose, thermostability), commercial model (licensing vs. supply vs. joint development), and geographic/service footprint (regional warehousing, on‑site formulation). For procurement and business development teams, knowing which suppliers excel on which dimension is a prerequisite to negotiating the right contract structure in 2026.
Market dynamics that will shape 2026 strategy
Our analysis synthesizes supply-side economics, policy drivers and technological evolution into a set of dynamics that should shape boardroom decisions in 2026:
- Raw‑material exposure: industrial enzyme manufacture depends heavily on fermentation feedstocks (glucose derived from corn or other starches). Raw material inputs account for a substantial share of manufacturing cost (industry estimates cluster in the 30–40% range). That creates a two‑way dependency: biomaterial producers influence enzyme costs, while enzyme demand competes with food and feed uses for the same commodities.
- Commodity price volatility: agricultural price swings materially affect enzyme margins and can create procurement discontinuities for biofuel producers. Scenario runs in the report show how different corn price trajectories translate into enzyme price pressure and, by extension, ethanol production economics.
- Regulatory acceleration for advanced biofuels: recent decisions on renewable fuel standards — including U.S. EPA volume requirements published for 2026–2027 — and global blending mandates create a predictable lift for cellulases and other enzymes that enable lignocellulosic ethanol. Policy certainty shortens investment payback horizons and alters capital allocation choices.
- Technological maturation and process integration: improvements in enzyme engineering, lower enzyme loading requirements, and novel process configurations (e.g., consolidated bioprocessing, enzymatic biodiesel production using lipases) are reducing operating costs and enabling new plant economics that were previously marginal.
Strategic recommendations for 2026
For executive teams preparing budgets, partnerships and M&A activity in 2026, the following priorities capture the highest-value, practical steps:
- Lock in supply through flexible long‑term agreements: prioritize contracts that incorporate volume flexibility, cost pass-through clauses tied to transparent indices, and built-in development pathways for next‑generation enzymes.
- Invest selectively in pilot commercialization of lignocellulosic pathways: allocate funding to demonstration projects with partners that provide enzyme co‑development — these projects will be the source of first-mover advantages as policy support matures.
- Hedge input exposure and diversify feedstock sources: develop feedstock diversification strategies and financial hedges that reduce sensitivity to single‑commodity price swings.
- Pursue capability gaps via bolt-on M&A or licensing: target mid‑sized, technology-focused enzyme firms or startups with novel biocatalysts or formulation expertise rather than broad horizontal consolidation; this approach preserves capital and accelerates access to differentiated performance.
- Embed regulatory scenario planning into capital allocation: stress-test investments against alternative RFS and global blending outcomes to avoid stranded capital in the event of slower-than-expected policy adoption.
How PW Consulting’s report supports execution
The study is designed to move leaders from insight to execution. Each chapter closes with specific decision frameworks — e.g., a procurement term checklist, a techno‑economic model template, and a target screening matrix for M&A. Methodologically, the work combines primary interviews with producers and suppliers, proprietary techno-economic modeling, and scenario sensitivity testing tied to regulatory timelines. Importantly, our public summary intentionally omits granular regional and application-level splits so that commercial clients can access full subsegment tables, supplier-by-supplier pricing scenarios and regional demand overlays through the full report package and advisory engagements.
Next steps
For firms that need to finalize 2026 procurement, capex or M&A decisions, the full report — and our accompanying advisory modules — deliver the granular inputs and bespoke scenario runs required for executable plans. Contact PW Consulting to commission tailored country or feedstock studies, supplier diligence projects, or integration roadmaps that convert the market’s macro trajectory into concrete commercial outcomes.
For detailed analysis of this topic, please visit the official page: Worldwide Enzymes for Biofuels Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Broadband Data Card Market Poised to Reach USD 2,495.03 Million by 2032 on a 2.15% CAGR
By pmarketresearch, 2026-07-15
Worldwide Broadband Data Card Market: Strategic Roadmap for 2026 — PW Consulting Release
Executive summary
PW Consulting’s new Worldwide Broadband Data Card Market report, with a 2025 base year and a forecast horizon through 2032, delivers a pragmatic, decision-focused perspective for corporate leaders planning capital allocation, product roadmaps, and go-to-market strategies in 2026. The global market — roughly USD 2.15 billion in 2025 — is projected to grow at a modest compound annual growth rate (CAGR) of 2.15% through the forecast window. That steady, low-single-digit expansion belies a nuanced set of structural shifts: 5G commercial rollouts, LTE persistence in legacy platforms, evolving device form-factors (M.2 and integrated modules), and the interplay between fixed broadband infrastructure and wireless broadband use cases.
Worldwide Broadband Data Card Market
Why this report matters for 2026 decision-making
-
Actionable foresight for portfolio strategy — We translate macro growth into practical guidance on where to prioritize R&D spend, which device form-factors require scale, and how to balance 5G investment with LTE lifecycle management to protect margins while avoiding stranded inventory risks.
Worldwide Broadband Data Card Market -
Go-to-market sequencing under regulatory uncertainty — With spectrum allocation and device certification timelines creating asymmetric launch windows across markets, the report maps timing-sensitive market entry options and contingency plans for delay-sensitive product launches.
Worldwide Broadband Data Card Market -
Supplier and component risk management — Component availability for radio front-ends, M.2 modules, and RF front-end integration remains a gating variable. Our analysis identifies where captive sourcing, strategic partnerships, or dual-sourcing materially alter time-to-market and TCO.
-
Commercial optimization playbook — We provide revenue capture levers (pricing architecture, bundled service partnerships, MVNO strategies) calibrated to the current mid-cycle growth environment so commercial teams can convert modest market expansion into above-market returns.
What’s in the report — pragmatic, operational content
This study is designed to be an operational manual for 2026. Key deliverables include:
-
Market sizing and scenario forecasts (base-year 2025, 2026–2032 outlook) with four demand scenarios that stress-test supply, regulation, and competitive disruption.
-
Product and deployment economics models that let readers simulate margin outcomes by form-factor (embedded modules, M.2 cards, mobile hotspots, USB/plug-in devices) and connectivity technology (LTE fallback, 5G sub-6 GHz strategy).
-
Go-to-market and channel playbooks for consumer, enterprise, and public-sector buyers — including partner archetypes, contract and pricing templates, and distribution priorities for urban vs. long-tail rural deployments.
-
Vendor benchmarking and technology scorecards covering radio performance, certification footprints, module integration ease, roadmap clarity, and supply-chain resilience.
-
Regulatory and spectrum impact assessment with mitigation plans for data sovereignty constraints, net neutrality developments, and certification timelines across critical markets.
-
M&A and partnership heatmaps highlighting strategic targets (component specialists, regional CPE makers, and software platforms) that can accelerate scale or expand addressable markets without heavy greenfield investment.
Market dynamics and the subtle growth story
The market’s projected steady trajectory masks a bifurcated landscape. On one hand, 5G is enabling differentiated enterprise and fixed-wireless access (FWA) use cases that demand higher-performing M.2 and integrated modules. On the other hand, FTTH penetration and legacy LTE deployments exert a dampening effect on unit growth in certain consumer segments. For decision-makers this creates both risk and optionality: investments targeted at high-value enterprise and industrial applications will capture disproportionate upside, while consumer-oriented product plays require tight cost control and channel discipline.
Competitive landscape — who to watch and why
The competitive structure is balanced: a handful of firms exert meaningful influence, but the market is not a closed oligopoly. Top-tier suppliers maintain strong engineering roadmaps and broad certification footprints, which creates barriers for late entrants but leaves space for specialist suppliers with targeted value propositions.
-
Huawei Technologies Co. Ltd. — A major OEM across mobile hotspots and integrated broadband cards, Huawei’s portable devices and SIM-enabled solutions continue to push performance per watt and user experience in markets where certification allows rapid commercial deployment.
-
Telit Cinterion (now under Semtech) — Focused on M.2 5G modules with LTE fallback and GNSS capabilities, positioning its products for fixed wireless access, enterprise routers, and vehicle connectivity where integration flexibility and multi-network support are decisive.
-
Sierra Wireless (now part of Semtech) — Brings multi-network 5G modules and system-level integration experience for mobile broadband and IoT, serving customers who need field-proven module-to-application continuity.
-
Inseego and Netgear — Both are focused on mobile hotspot and MiFi product lines, with an emphasis on user experience, ease of SIM management, and consumer/SMB distribution. Their differentiation lies in device firmware, management portals, and channel relationships.
-
ZTE, Quectel, Fibocom — These vendors play to strengths in module manufacturing scale, form-factor variety, and OEM partnerships, supporting CPE, industrial routers, and embedded use cases where price-performance and certification breadth matter.
Our vendor scorecards in the report evaluate these players on multi-dimensional criteria — technology roadmap, certification coverage, supply-chain resilience, and commercial flexibility — and recommend partner archetypes for different corporate priorities (speed-to-market, cost leadership, bespoke integration).
Regulation, infrastructure, and systemic risks
Several cross-cutting factors will materially affect 2026 decisions:
-
Net neutrality and open-internet policy continue to shape commercial terms and pricing strategies for bundled connectivity offerings.
-
Data sovereignty and local regulation increase compliance costs for international deployments, particularly for MVNO and IoT service models that rely on third-party SIM provisioning.
-
Spectrum allocation and device certification timelines amplify obsolescence risk for 4G/5G product lines; firms must factor certification lag into product launch calendars.
-
Parallel infrastructure trends — rising FTTH penetration globally — shift some consumer demand away from wireless-only solutions and elevate the strategic value of hybrid offers and seamless fallback experiences.
Strategic recommendations for 2026
-
Prioritize modular product architectures: Design platforms that can accept swappable radio modules to extend product life across certification cycles and regional spectrum variants.
-
Target enterprise and industrial segments where differentiated connectivity (QoS, SLA-backed FWA) and verticalized solutions command healthier margins and justify bespoke integration.
-
Invest selectively in software and device management ecosystems to turn hardware into recurring revenue engines through subscription services, device management, and carrier partnerships.
-
Implement a dual-sourcing approach for critical RF components and modules to mitigate supply-chain volatility without surrendering cost competitiveness.
-
Design certification-first launch plans: Align product roadmaps to prioritized certification paths and build regulatory monitoring into the product development lifecycle to avoid market-entry delays.
-
Assess inorganic opportunities strategically: Look for tuck-ins that provide market access (regional CPE specialists, platform software providers) rather than scale-only acquisitions that increase complexity.
How to use the report
Executives, product leads, M&A teams, and commercial strategists will find distinct, operational outputs in the report: scenario-based revenue models, supplier negotiation playbooks, certification calendars, and vendor scorecards. The document is structured to support rapid decision cycles: executive summaries for board briefings, one-page playbooks for product teams, and appendices with methodology and data lineage for finance and audit.
About the analytical approach and what’s intentionally excluded here
Our methodology combines primary interviews with device OEMs, module vendors, tier-1 carriers, and component suppliers, with a demand-side synthesis informed by installed base dynamics and infrastructure trends. For this public release we deliberately withhold detailed segment-level numbers and regional/application splits to preserve the report’s role as the definitive source for downstream commercial planning — the full data tables, segment breakouts, and supplier revenue curves are available in the paid report.
Conclusion & next steps
In a market characterized by modest aggregate growth but concentrated pockets of high strategic value, 2026 will be a year where execution precision outpaces scale. Companies that align architecture flexibility, certification planning, and channel economics will convert incremental market growth into sustained commercial advantage. PW Consulting’s Worldwide Broadband Data Card Market report is built to be the tactical compass for that execution. For the full data suite, vendor scorecards, and downloadable scenario models, access the report landing page and obtain the complete research package.
For detailed analysis of this topic, please visit the official page: Worldwide Broadband Data Card Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: Worldwide Single Point Anchor Reservoir Market to Rise from USD 1,420.5 Million in 2025 to USD 2,059.53 Million by 2032 at a 5.45% CAGR
By pmarketresearch, 2026-07-15
Worldwide Single Point Anchor Reservoir Market — 2026 Strategic Briefing
PW Consulting today releases a strategic preview of its forthcoming Worldwide Single Point Anchor Reservoir Market research report. Designed for C-suite leaders, project directors, and strategic planners preparing for 2026 decision cycles, this briefing synthesizes the report’s most consequential, actionable insights while preserving the granular data available only in the full publication.
Worldwide Single Point Anchor Reservoir Market
Why this market matters in 2026
Single point anchor reservoirs (SPARs) remain a critical enabling technology across a changing offshore landscape. Over the five years to 2025 the global market expanded meaningfully, moving from an estimated USD 1,089.45 Million in 2020 to USD 1,420.50 Million in 2025. Our baseline projects continued, steady growth through the 2026–2032 forecast window, culminating in an estimated USD 2,059.53 Million by 2032 — an implied compound annual growth rate (CAGR) of 5.45% for the forecast period.
Worldwide Single Point Anchor Reservoir Market
That growth trajectory is less about a single driver and more about the intersection of multiple structural forces: portfolio rebalancing among majors, the push to unlock deeper and higher-pressure reservoirs, and the early-stage incorporation of floating renewables into traditional supply chains. For organizations planning capital allocation and strategic partnerships in 2026, these dynamics translate into distinct windows of opportunity — and risk — which the full report quantifies and operationalizes.
Worldwide Single Point Anchor Reservoir Market
What PW Consulting’s report delivers — practical, decision-grade intelligence
- Proprietary market model: A bottom-up revenue model covering the historical period (2020–2025) and a detailed forecast (2026–2032) with scenario toggles for price, deployment rate, and technology adoption.
- Investment playbooks: Capex phasing and ROI sensitivity analyses that translate macro growth into specific timing recommendations for greenfield projects, FPSO integrations, and retrofits.
- Supply chain diagnostics: A practical supplier and fabricator scorecard, lead‑time heat maps, and alternative sourcing pathways to de-risk long-lead components within a two- to four-year procurement horizon.
- Regulatory and permitting matrix: Regional compliance frameworks, permitting timelines, and policy-trigger scenarios that materially affect deployment schedules and contract structuring.
- Commercial strategies: Tender design, contract clauses, and pricing models tailored to mitigate volatility in steel, fabrication, and logistics costs while preserving margin.
- Technology and integration guidance: Comparative assessments of SPAR subtypes, mooring architectures, and integration pathways with floating wind and subsea production systems (note: the report highlights relative strengths and trade-offs; it deliberately withholds granular subsegment revenue tables in this preview to preserve competitive value).
Concentration and competitive dynamics — what to expect
The market exhibits moderate concentration: the top-three firms collectively control approximately 42.5% of market revenue, while the top-five account for roughly 61.25%. This structure creates a two-speed competitive environment in which established engineering-and-fabrication integrators retain significant pricing and delivery power, while specialized mid‑tier suppliers and new entrants compete on modularity, speed-to-deploy, and niche technical differentiators.
Strategic implications for 2026:
- Incumbents will prioritize integrated project delivery models and long-term supply agreements to secure fabrication capacity and protect margins.
- Mid-tier players can capture value through focused capabilities — e.g., innovative mooring solutions, rapid-installation modules, or lifecycle services — but must demonstrate repeatable performance records to win tier-one buyers.
- Private equity and strategic investors will find arbitrage in consolidation plays where operational scale can be combined with advanced manufacturing to compress lead times and cost curves.
Key market dynamics shaping tactical choices
Three interlocking dynamics will define the 2026 decision environment:
- Deployment cadence vs. fabrication capacity: Fabrication yards remain the critical choke point. Buyers that lock conditional capacity or adopt modularization can reduce schedule risk and avoid inflationary tender cycles.
- Cross-sector convergence: The initial coupling of floating offshore wind supply chains with oil and gas SPAR systems is creating both competition for yard capacity and opportunities for shared logistics and standards—buyers that proactively develop cross-sector alliances can secure preferential access to resources.
- Regulatory and contractual risk transfer: With increasing scrutiny on offshore operations and local content regimes in key markets, contract structures must be rebalanced to allocate permitting, environmental and decommissioning risk more explicitly between sponsors and suppliers.
How PW Consulting’s scenarios inform 2026 decisions
The report provides three practical scenarios—Conservative, Base, and Accelerated—that translate macro assumptions into actionable outcomes at the project and portfolio levels. Each scenario includes:
- Quantified impacts on revenue timing and supplier capacity utilization;
- Trigger points for contract renegotiation or capital reallocation;
- Recommendations for hedging strategies across procurement, financing, and insurance;
- Early-warning indicators to monitor in 2026 (e.g., tender backlog velocity, yard utilization rates, key raw-material index spreads).
For executives, the value is immediate: scenario outputs show not just what might happen to topline demand, but how procurement windows, financing rounds, and partnership timetables must shift to optimize NPV under each plausible future.
Practical recommendations for 2026 planning
Based on our analysis, PW Consulting recommends the following actions for stakeholders preparing decisions in 2026:
- Lock conditional fabrication capacity: Negotiate shortlist agreements with yards that include escalation clauses tied to pre-agreed indices instead of fixed-price long‑term contracts.
- Modularize scope where possible: Decompose large SPAR deliveries into deliverable modules to shorten critical-path manufacturing and reduce single-supplier dependency.
- Prioritize early supplier integration: Move key suppliers into front-end engineering and design (FEED) stages to align lead times and reduce change orders.
- Hedge regulatory risk: Use staged permitting commitments and create contractual pass-throughs for jurisdictional policy changes to limit sponsor exposure.
- Explore cross-sector alliances: Identify floating renewables partners to co-locate fabrication and logistics services and realize shared cost synergies.
- Prepare an exit/scale play: Define clear KPI thresholds for accelerating capex, pursuing bolt-on acquisitions, or divesting marginal assets as scenarios unfold.
What’s intentionally withheld in this preview — and why
To preserve the actionable advantage for subscribers and paying clients, this briefing intentionally omits the report’s most granular subsegment tables — including detailed region-by-region and application-by-application revenue splits, vendor-level market shares, and line-item pricing schedules. The full report contains these datasets, downloadable models, and editable dashboards that enable direct application to your project financials, tender evaluations, and M&A screens.
Who should read the full report
- Corporate strategy teams at E&P companies planning deepwater or floating renewable integrations.
- Procurement and supply chain executives seeking to optimize sourcing and yard allocation strategies for 2026 bids.
- Investors and private equity sponsors evaluating roll-up or growth equity opportunities in fabrication and engineering niches.
- Project finance teams requiring transparent scenario-testing for covenant design and cashflow modeling.
About PW Consulting’s methodology
PW Consulting’s market model synthesizes a multi-source evidence base: vendor disclosures, project procurement notices, yard capacity audits, and interviews with procurement leads across operators and integrators. Coverage includes a detailed historical run (2020–2025), a base-year alignment at 2025, and forecast scenarios for 2026–2032. Our concentration metrics (CR3 ~42.5%; CR5 ~61.25%) are calculated from supplier revenue estimates captured in the model and validated against multiple independent sources.
Next steps — where to get the full intelligence
This preview is intended as a strategic primer. For teams that must translate market trends into executable 2026 plans, the full report is the operational toolkit: editable financial models, supplier scorecards, procurement templates, and scenario dashboards. To access the complete Worldwide Single Point Anchor Reservoir Market report, supporting datasets, and bespoke consulting engagements, visit our report page or contact PW Consulting’s industry team to schedule a briefing.
PW Consulting remains available to run tailored workshops that convert these insights into procurement strategies, portfolio optimization plans, and risk mitigation programs timed to your 2026 decision milestones.
For detailed analysis of this topic, please visit the official page: Worldwide Single Point Anchor Reservoir Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Predicts Negative Thermal Expansion Filler Market to Reach USD 473.43 Million by 2032, Driven by an 8.79% CAGR
By pmarketresearch, 2026-07-13
Negative Thermal Expansion (NTE) Filler Market: Strategic Priorities for 2026 — A PW Consulting Advisory
As companies plan capital allocation and product roadmaps for 2026, Negative Thermal Expansion (NTE) fillers have moved from niche materials into a strategic lever for managing reliability, miniaturization and athermalization across high-value industries. Our latest market study — anchored on a 2025 base year and a detailed 2026–2032 forecast horizon — projects continued, above-market growth for the NTE filler sector, with the global market expanding at a compound annual growth rate of 8.79%. The market has grown materially over the last half-decade, and our scenarios indicate a robust climb from the 2025 baseline toward substantially higher volumes and revenues by the end of the forecast period.
Negative Thermal Expansion Filler Market
Why 2026 Is a Pivotal Year for Decision-Makers
Several converging forces make 2026 a turning point for firms that manufacture, source or specify NTE fillers:
Negative Thermal Expansion Filler Market
- Engineering constraints in advanced electronics and optics are tightening as device geometries shrink and multi-material assemblies proliferate; thermal mismatch is now a first-order design constraint rather than an afterthought.
- Supply-side volatility in critical feedstocks (notably tungsten and zirconium derivatives) has increased input-cost and continuity risk, elevating procurement and inventory strategy to board-level priorities.
- Regulatory and certification pathways — particularly in aerospace and defense — are creating premium product segments where validated NTE solutions command disproportionate value.
- Manufacturing innovations such as nano-structured powders and additive-compatible formulations are opening new applications while changing unit economics and integration complexity.
For executives, the practical implication is clear: 2026 is the year to transition from opportunistic engagement with NTE technologies to integrated strategic programs that span R&D, supply chain and commercial go-to-market.
Negative Thermal Expansion Filler Market
Data-driven market posture
Our analysis shows the industry’s macro trajectory is healthy: between 2020 and 2025 the market expanded markedly, and the forecast through 2032 reflects sustained mid-to-high single-digit CAGR growth. This macro momentum masks important heterogeneity — certain material families and end-use pairings are emerging as premium pockets while others remain price- and commodity-driven. PW Consulting’s report quantifies these dynamics at the product and application level and models scenarios that translate macro growth into actionable demand forecasts for product teams and procurement functions.
Competitive Landscape: Who Matters and Why
Understanding incumbent capabilities and technology roadmaps is essential when crafting partnerships, licensing deals or M&A approaches. The NTE filler ecosystem today combines specialty chemical producers, advanced materials manufacturers and precision component firms. Notable players we profile include:
- TOAGOSEI CO., LTD. — With ULTEA (zirconium phosphate based) offerings that exhibit NTE behavior to high temperatures and notable chemical resilience, TOAGOSEI is positioned for sealed-glass and high-temperature applications. Their strength is applied material reliability and formulation know-how for adhesion and sealing systems.
- Nippon Electric Glass (NEG) — NEG’s spherical glass-based negative-CTE fillers prioritize packability and dispersibility in resin systems, directly addressing manufacturability and processing efficiency for electronics and precision assemblies.
- Mitsui Kinzoku — By commercializing powders that deliver substantial NTE, Mitsui brings metallurgical and powder-processing scale advantages that suit glass and resin suppression applications where throughput and cost efficiency are important.
- JX Advanced Metals — Focused development of zirconium tungstate (ZrW2O8) with attention to particle fineness and phase behavior positions JX for semiconductor packaging and sealing markets that require tight CTE control and process compatibility.
- Japan Material Technologies Corporation (JMTC) — Offering perovskite oxide-based NTE materials with tunable center temperatures, JMTC represents an innovation vector for thermally responsive composites and advanced epoxies with bespoke thermal profiles.
- ALLVAR Alloys — A different commercialization model: metal-alloy components and custom mechanical parts that exhibit strong NTE and are used directly in optical assemblies and precision structural items where form factor and machinability matter.
Each of these players brings a differentiated value proposition: from powder chemistry and thermal stability to particle morphology and finished-component supply. For strategic buyers and OEMs, the right engagement model will depend on desired control over specification, sensitivity to raw-material cycles and certification requirements in target end-markets.
Supply Chain and Input Risk: The New Operating Reality
Raw material dynamics are an unavoidable part of any 2026 sourcing strategy for NTE fillers. Recent market signals are instructive:
- Tungsten markets have tightened materially, and price spikes observed in early 2026 have direct implications for tungsten-containing NTE chemistries (e.g., zirconium tungstate). Such moves change the relative economics between competing NTE material families and elevate the value of material-agnostic design options.
- Export controls and trade policy shifts — notably actions that affect key concentrate flows — have compressed available global supply and increased the probability of supply interruptions for tungsten-dependent manufacturers.
- Zirconium oxide and related zirconia derivatives also showed price pressure in late 2025, reflecting both energy/input cost pass-through and capacity constraints. For firms using zirconium phosphate, zirconia or related compounds, contingency plans are essential.
For procurement organizations, the takeaway is straightforward: active commodity risk-management (strategic stock positions, diversified sourcing, long-term offtakes), combined with near-term product substitution assessments, will materially reduce margin and schedule exposure.
Strategic Playbook for 2026
PW Consulting’s advisory recommends a four-track strategy for players who want to convert the macro growth tailwind into durable competitive advantage:
- Product and IP posture: Prioritize R&D investments that address dispersibility and particle control (reducing agglomeration and improving resin compatibility), along with efforts to lower phase-transition sensitivity across operating temperatures. Proprietary surface treatments and composite engineering provide defensible differentiation.
- Supply resiliency: Execute dual-sourcing strategies for tungsten and zirconium feedstocks, explore hedging and long-term contracts with upstream miners and consider strategic inventory buffers targeted at high-risk SKUs.
- Commercial focus: Target high-value, high-barrier applications — aerospace, high-end optics, and advanced semiconductor packaging — where certification and reliability premium justify higher margins. Build joint-development agreements with OEMs to lock in application-specific qualifications.
- M&A and partnerships: For firms seeking to scale quickly, bolt-on acquisitions that bring particle-engineering expertise, certifications for regulated markets, or downstream assembly capabilities can accelerate entry and reduce go-to-market friction.
What Our Report Delivers — Practical, Executable Insight
This release is not an academic paper; it is a practitioner’s toolkit. Highlights from the full PW Consulting NTE Filler Market Report include:
- Top-down and bottom-up market forecasts (2026–2032) cross-validated against supply-side capacity and demand signals, with scenario stress-testing for raw-material shocks.
- Commercial due-diligence templates: supplier scorecards, margin sensitivities, and procurement negotiation playbooks tailored to NTE materials.
- Product-development briefs that translate thermal expansion targets into formulation priorities (particle size, morphology, surface chemistry, and binder compatibility), plus a prioritized technology roadmap for R&D teams.
- Regulatory and certification pathway maps for aerospace, medical and semiconductor applications, including time-to-qualification estimates and key test protocols.
- Competitive landscape dossiers with capability matrices, potential white-space opportunities, and strategic options (partner, acquire, co-develop) for market entrants.
We deliberately omit line-by-line disclosure of granular regional splits and application-specific revenue buckets in this public summary — the full dataset and interactive dashboards are available through our report portal for clients who require the complete, attributional intelligence necessary to execute transaction and product decisions.
Near-term Signals to Watch in 2026
- Raw-material price trajectories and policy announcements affecting tungsten and zirconium supply will be immediate leading indicators of margin pressure and product re-pricing.
- Certification wins and aerospace approvals will re-rate suppliers into premium segments; watch for additional announcements following the recent aerospace certifications observed in the sector.
- New product introductions and manufacturing methods (e.g., nano-structured powders or additive-compatible formulations) will indicate where early adopters are focusing and where downstream demand is likely to concentrate.
- Consolidation activity: given the market’s concentration dynamics, expect selective M&A among specialty providers aimed at augmenting particle-engineering or downstream application capabilities.
Concluding Recommendations for 2026 Planning
For leadership teams our advice is pragmatic: treat NTE fillers as a strategic material category, not a commodity. Embed thermal-management considerations into product and procurement planning cycles, invest in joint-development projects with leading suppliers to secure differentiated formulations, and build supply-side contingencies for critical feedstocks. The market’s projected growth — underpinned by a near-double-digit CAGR relative to many mature materials segments — creates attractive upside for companies that act now to secure technology, qualify materials in target assemblies and mitigate supply risk.
PW Consulting’s full Negative Thermal Expansion Filler Market Report provides the granular forecasts, supplier assessments, and execution-ready playbooks required to convert this strategic insight into measurable commercial outcomes. For clients who need the datasets, scenario models, and bespoke advisory to support 2026 capital and product decisions, please visit our report page to access the complete intelligence suite and to arrange a dedicated briefing.
For detailed analysis of this topic, please visit the official page: Negative Thermal Expansion Filler Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide 4‑Chlorobenzonitrile Market Poised to Grow at a 4.15% CAGR, Says New Report
By pmarketresearch, 2026-07-13
Worldwide 4-Chlorobenzonitrile Market — Strategic Preview for 2026 Decision‑Makers
Executive summary
PW Consulting’s new market study on 4‑Chlorobenzonitrile provides a focused, decision‑ready briefing for executives planning investment, procurement, or commercial strategies in 2026. Built on a 2020–2025 historical base and a 2026–2032 forecast horizon, the analysis demonstrates a resilient market trajectory: the global market size rose from the low‑hundreds of USD Million in 2020 to a 2025 base year of USD 234.6 Million and is modeled to grow to roughly USD 311.9 Million by 2032 at a 2026–2032 CAGR of 4.15%. Market concentration is meaningful — the top three players account for just over 42% of the market, while the top five control nearly 59% — creating a competitive environment where scale and specialty positioning both matter.
Worldwide 4-Chlorbenzonitrile Market
Why this matters for 2026 strategy
- Investment timing: The forecasted mid‑single‑digit CAGR through 2032 signals steady demand, but not runaway expansion — this favors measured capital deployment with optionality.
- Supplier selection: Because concentration is moderate, buyers can balance price leverage against quality and regulatory track‑record when choosing suppliers.
- Risk planning: Feedstock and regulatory shifts are the dominant short‑term risk vectors; proactive mitigation will preserve margins and secure continuity.
Market trajectory and the forces shaping it
Our model captures a market that has recovered from early‑decade headwinds and now sits on a platform of industrial and research applications. Drivers include consistent demand from fine chemicals, pharma and agrochemical intermediates, and steady uptake in specialty pigment and dye applications. At the same time, input costs and regulatory compliance are growing considerations for both suppliers and buyers.
Worldwide 4-Chlorbenzonitrile Market
Primary external influences we track for 2026 planning:
Worldwide 4-Chlorbenzonitrile Market
- Feedstock price volatility — notably chlorobenzene — which traded in the range of approximately USD 1,200–1,400 per metric ton in Q1 2026, creating a direct and predictable channel to product cost structures.
- Regulatory tightening in key markets — for example, REACH registration requirements that impose extended safety data obligations for substances exceeding defined tonnage thresholds in the EU.
- Trade and documentation protocols — such as the U.S. HTS classification that requires import documentation for this chemical but, as of 2026, carries no Section 301 tariff; these administrative rules affect lead times and compliance overheads for cross‑border flows.
What PW Consulting’s report delivers (practical, execution‑focused)
This report is built to be operationally useful for commercial and procurement teams. Highlights include:
- Proprietary forecast model (2026–2032) with base‑case and alternative scenarios that quantify the impact of feedstock price shocks, demand shocks from downstream industries, and regulatory compliance costs.
- A supplier scorecard that assesses production footprint, purity‑grade capabilities, MOQ ranges, quality assurance practices, and supply continuity performance.
- Customer‑persona demand segmentation and purchase behavior mapping (buyers in pharma R&D vs. bulk agrochemical manufacturers), with recommended commercial approaches for each persona.
- Supply‑chain diagnostic and a procurement playbook: negotiation levers, contract clauses to manage feedstock pass‑through, inventory strategies (safety stock vs. JIT), and dual‑sourcing frameworks.
- Regulatory and customs checklist for 2026: key filings, labelling and documentation templates, and a practical roadmap for REACH conformity and U.S. import compliance.
- Risk matrix and mitigation templates for contamination events, export disruptions, and feedstock spikes — including decision triggers for switching suppliers or invoking force majeure.
Competitive landscape — profiles and strategic implications
The market is characterized by a mix of global high‑purity suppliers, regionally competitive producers, and specialized fine‑chemical houses. Our report analyzes the competitive positioning of the principal players to help buyers and investors prioritize engagement.
- Alfa Aesar (Thermo Fisher Scientific) — USA : A go‑to for high‑purity lab and small‑scale supplies, Alfa Aesar’s brand strength and global distribution make it ideal for pharmaceutical R&D partnerships. Strategic implication: long‑term buyers of high‑purity intermediates should use Alfa Aesar for rapid prototyping and quality benchmarking.
- Sigma‑Aldrich (Merck KGaA) — Germany : Offers multiple purity grades and a mature distribution network. Strategic implication: buyers prioritizing regulatory documentation and established supply chains will find value in Sigma‑Aldrich’s compliance pedigree.
- TCI America (Tokyo Chemical Industry) — Japan : Positioned as a reliable international shipper with a strong organic synthesis customer base. Strategic implication: consider TCI for consistent mid‑scale supply and cross‑border logistical efficiency.
- Apollo Scientific — UK : Focused on manufacturing for fine chemical markets and custom/bulk order flexibility. Strategic implication: an attractive partner for custom synthesis, toll manufacturing, and tailored supply agreements.
- Combi‑Blocks — USA : Specialist in gram‑to‑kilogram building blocks for medicinal chemistry, with responsive service for small‑scale clinical work. Strategic implication: well suited for early‑stage drug discovery programs requiring agility over scale.
- Oakwood Chemical — USA : Emphasizes aromatic halide intermediates and bridges R&D to low‑volume production. Strategic implication: good fit for customers needing transition support from lab to pilot production.
- Nanjing Chemlin Chemical Industry — China : Active in bulk export markets and competitive on cost. Strategic implication: offers scale and cost advantages for volume buyers but requires careful due diligence on QA and compliance documentation.
Collectively, these players illustrate a market where differentiated service, regulatory compliance, and geographic reach are as important as price. The mix of global established brands and regional bulk producers underpins the observed concentration metrics.
Supply chain and cost dynamics: what procurement needs to know
Two levers will dominate near‑term commercial outcomes:
- Raw material exposure: Chlorobenzene price swings transmit quickly to producers’ margins. Our scenario tests show that a sustained move toward the top of the Q1 2026 price band materially compresses margins for non‑integrated producers and shifts ordering behavior among buyers.
- Purity segmentation: Products supplied across multiple purity grades create distinct value pools. Buyers who can tolerate slightly lower purity for non‑critical uses can optimize costs; conversely, premium‑purity demand supports higher margins and longer lead times for suppliers.
Operational recommendations for procurement teams:
- Run a short‑cycle total‑cost‑of‑ownership (TCO) analysis incorporating feedstock pass‑through, logistics, and compliance costs rather than relying on unit price alone.
- Secure at least one supplier with demonstrated REACH and import documentation readiness if operating in the EU or sourcing into the U.S.
- Use flexible contract structures with scheduled price reviews linked to a chlorobenzene index to reduce disputes and preserve margin visibility.
Regulatory and trade considerations
Regulation is now a commercial differentiator. In the EU, REACH obligations require extended safety dossiers for firms manufacturing or importing above defined tonnages — a practical compliance threshold that changes supplier economics for mid‑sized producers. In the U.S., the harmonized tariff schedule classification requires specific import documentation under HTS 292690; while there are no Section 301 tariffs affecting this code as of 2026, the administrative cost of customs compliance remains material for cross‑border supply chains.
Strategic recommendations for 2026
- For buyers: implement a two‑track sourcing strategy — retain a high‑compliance global supplier for critical, high‑purity needs, and qualify a cost‑efficient regional producer for volume requirements. Lock a portion of supply under indexed pricing to mitigate feedstock shocks.
- For suppliers: prioritize investments in quality assurance, regulatory documentation, and small‑lot packaging to capture R&D and specialty markets while selectively scaling bulk capacity where margin outlook is favorable.
- For investors: seek assets that combine feedstock security (or integration) with documented regulatory compliance; these attributes compress downside risk in a market with steady but moderate growth.
About the report and next steps
This article is a strategic preview designed to orient executives and highlight the practical utility of PW Consulting’s full study. The complete report contains the granular segmentation, supplier scorecards, price‑sensitivity modelling, and downloadable decision tools that are intentionally withheld here to preserve the report’s commercial value. If you are evaluating capital deployment, procurement policy changes, or supplier consolidation in 2026, the full dataset and playbooks in our report will shorten your implementation timeline and reduce execution risk.
Contact PW Consulting to access the comprehensive Worldwide 4‑Chlorobenzonitrile Market report and receive a tailored briefing for your organization’s 2026 planning cycle.
For detailed analysis of this topic, please visit the official page: Worldwide 4-Chlorbenzonitrile Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide CD4 Antibody Market Set to Expand at an 8.41% CAGR Through 2032
By pmarketresearch, 2026-07-13
Worldwide CD4 Antibody Market: Strategic Imperatives for 2026 — PW Consulting Preview
As life-sciences executives and investors refine priority lists for 2026, the CD4 antibody arena is re-emerging as a strategic crossroads between foundational research tools and next‑generation therapeutic innovation. PW Consulting’s new Worldwide CD4 Antibody Market report (base year 2025; historical 2020–2025; forecast 2026–2032) provides an evidence‑based framework to translate market momentum into executable corporate decisions. The market reached an estimated USD 846.2 Million in 2025 and is projected to expand at a compound annual growth rate (CAGR) of 8.41% through the forecast horizon — approaching a near‑term strategic inflection by the end of the 2026 planning cycle.
Worldwide CD4 Antibody Market
Why CD4 Antibodies Matter to 2026 Strategy
-
Platform elasticity: CD4 antibodies sit at the intersection of immunophenotyping, translational immunology, and targeted immunomodulation. Their role extends from flow cytometry panels used in clinical monitoring to engineered monoclonals being evaluated for regulatory T‑cell modulation. For product leaders, this means CD4 reagents are simultaneously a steady revenue stream and a source of disruptive therapeutic opportunity.
Worldwide CD4 Antibody Market -
Regulatory inflection: Most commercial CD4 reagents remain designated Research Use Only (RUO), but an expanding subset is being developed or cleared for in‑vitro diagnostic (IVD) use. This creates differentiated pathways — and differentiated margins — for firms that can navigate IVD validation and device regulatory frameworks.
Worldwide CD4 Antibody Market -
reimbursement levers: Reimbursement policies — including place‑of‑service and laboratory code frameworks — continue to influence adoption of CD4 count testing in specific care pathways. For example, absolute CD4 testing performed by flow cytometry is reimbursable in certain payer environments under established CPT codes, which sustains demand within defined clinical pockets.
Market Trajectory: From Research Reagent to Strategic Asset
Our base‑case model positions the CD4 antibody market on a steady growth trajectory from 2026 onward. The market’s expansion is driven by a mix of durable demand for flow cytometry reagents in immunology and infectious‑disease labs, the diffusion of higher‑value conjugates and recombinant formats, and selective therapeutic development programs that re‑position CD4 as a targetable axis for immune modulation. By 2032, the market is expected to significantly exceed its 2025 level, reflecting both sustained research spend and incremental uptake of clinically validated products.
Key Growth Drivers and Headwinds
-
Scientific demand: Rising investment in immune‑profiling and single‑cell analytics increases demand for high‑performance CD4 reagents across both academia and biopharma R&D.
-
Product innovation: Advances in recombinant antibody platforms, fluorochrome chemistry, and conjugation formats are creating premium product tiers that command higher ASPs (average selling prices) and customer loyalty.
-
Therapeutic pipelines: Select clinical programs that target CD4 or CD4‑expressing lymphocyte subsets can materially alter the market composition by shifting spend toward clinical‑grade materials and companion diagnostics.
-
Regulatory complexity: Transitioning a CD4 reagent from RUO to IVD/CE marking requires disciplined regulatory investment. Companies that succeed can access clinical markets with higher barriers to entry — but the validation burden and timelines are non‑trivial.
-
Concentration and competition: The market exhibits measurable concentration among established reagent and life‑science tool companies, creating structural advantages around scale, distribution, and bundled panel solutions.
What the Report Delivers: Operational, Commercial, and Strategic Tools
This report is built for decision makers who need to convert market intelligence into actions in 2026. It blends quantitative forecasting with actionable diagnostics and includes:
-
A transparent market model and base‑case/alternate scenarios for 2026–2032 that let users stress‑test assumptions (demand elasticity, premium product adoption, and regulatory conversion rates).
-
Segment‑level archetypes and buyer personas (research labs, clinical diagnostics, biopharma CMC groups), with go‑to‑market playbooks tailored to each customer type.
-
Regulatory and reimbursement matrix mapping RUO versus IVD pathways across major jurisdictions, including device classification references relevant to flow cytometry reagent panels.
-
Commercial diligence templates: pricing benchmarks, channel economics, and an M&A scorecard to evaluate tuck‑ins, licensing opportunities, or vertical integration plays.
-
Supplier and technical due diligence checklists (assay validation, lot‑to‑lot consistency, fluorochrome stability) for sourcing and partnership decisions.
-
Primary interview summaries and a validated competitor database to support vendor selection and negotiation.
Competitive Landscape — Strategic Profiles
The CD4 antibody ecosystem spans global reagent companies, specialized antibody providers, and emerging therapeutic developers. Key players profiled in the report illustrate diverse strategic positions:
-
Bio‑Rad Laboratories: Known for established CD4 clones and a broad conjugate portfolio optimized for flow cytometry and immunohistology. Strengths include longstanding assay validation and a deep research‑market channel footprint.
-
Thermo Fisher Scientific (including Invitrogen and eBioscience brands): Leverages scale and an expansive portfolio of conjugates and clones to serve high‑throughput research operations. The company’s strength is breadth — enabling bundled solutions across antibody and instrumentation ecosystems.
-
R&D Systems (Bio‑Techne) and Novus Biologicals: Offer validated CD4 clones with emphasis on reproducibility and research‑grade performance, appealing to translational labs requiring consistency across studies.
-
Beckman Coulter Life Sciences: Differentiates through clinical‑grade reagents and CE/IVD offerings designed for diagnostic immunophenotyping and clinical laboratory workflows.
-
BioLegend, Miltenyi Biotec, Abcam: Compete through targeted innovation — whether that is novel fluorochrome conjugates, recombinant antibody platforms, or flexible reagent formats that address evolving cytometry platforms and single‑cell workflows.
-
CD4 Therapeutics GmbH: Represents the therapeutic inflection — in mid‑2024 the company secured exclusive rights to a regulatory T‑cell‑modulating anti‑CD4 monoclonal (Tregalizumab), underscoring a strategic pathway where CD4 biology transitions from marker to mechanism.
-
Specialist suppliers (e.g., Boster Bio): Continue to supply research markets with cost‑effective clones and multi‑format reagents, serving as important components of long tail demand.
Recent Industry Movements and Their Strategic Implications
-
Licensing and therapeutic development: The mid‑2024 exclusive agreement securing rights for a regulatory T‑cell‑activating anti‑CD4 monoclonal highlights how licensing deals can quickly elevate CD4 from a reagent market to a therapeutic target with broader commercial ramifications. For product and BD leaders, these deals signal the need to align reagent roadmaps with potential companion diagnostic demand.
-
Regulatory posture: Many commercial CD4 antibodies remain RUO; where CE/IVD versions exist, they command clinical workflows. The report maps how regulatory designation alters commercialization pathways and time to revenue.
-
Reimbursement context: In select payer jurisdictions, absolute CD4 testing via flow cytometry is covered under established laboratory procedure codes — a dynamic that preserves clinical demand for validated CD4 reagents in niche care pathways and monitoring programs.
How to Use This Intelligence in 2026 Planning
-
For product teams: Prioritize investment in recombinant formats and premium conjugation chemistry where the market shows willingness to pay for consistency and enhanced performance. Use the report’s scenario tools to quantify ROI under different R&D and regulatory timelines.
-
For BD and corporate development: Use the M&A scorecard to screen targets that fill capability gaps (IVD validation, fluorochrome IP, or therapeutic partnerships) and to evaluate licensing opportunities similar to recent anti‑CD4 transactions.
-
For commercial leaders: Reconfigure channel strategies to capture both steady RUO demand and emerging clinical volumes. The report’s go‑to‑market playbooks provide playbooks for bundling, tiered pricing, and distributor engagement.
-
For investors: The market’s mid‑single‑digit to high‑single‑digit CAGR and measurable concentration among leaders create distinct risk/reward profiles for platform plays versus niche reagent specialists. Use the competitor benchmarking and concentration metrics to inform portfolio construction.
About the PW Consulting Report and Next Steps
PW Consulting’s Worldwide CD4 Antibody Market report is designed to be both an evidence base and an operational tool for 2026 decision cycles. It combines quantitative forecasts (2026–2032), a regulatory and reimbursement compendium, detailed competitor profiles, and practical playbooks for product, BD, and commercial teams. For executives who require the underlying datapack, full segmentation, and downloadable financial models — including the granular outputs that power the scenarios summarized here — please visit our report page to access the complete dataset and licensing options.
Methodology note: Our analysis uses a 2025 base year, reviews historical performance from 2020–2025, and applies demand‑side and supply‑side scenario modeling across the 2026–2032 forecast window to produce the CAGR and trajectory estimates cited above.
Contact
PW Consulting remains available to conduct bespoke workshops, in‑depth competitor due diligence, and model customizations to align this market intelligence with your 2026 strategic planning process.
For detailed analysis of this topic, please visit the official page: Worldwide CD4 Antibody Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Rectangular Enameled Wire Market at USD 4.58B in 2025 — Asia‑Pacific Leads with USD 2.46B, EV Motors Drive USD 1.83B Demand; 6.35% CAGR Projected to 2032 (CR5 41.2%)
By pmarketresearch, 2026-07-13
Worldwide Rectangular Enameled Wire Market — Strategic Briefing for 2026 Decision-Makers
PW Consulting’s latest market study on the Worldwide Rectangular Enameled Wire market (base year 2025) synthesizes five years of historical behavior (2020–2025) and delivers a forward-looking forecast through 2032. The market has expanded from an estimated USD 3,420.5 Million in 2020 to USD 4,580.45 Million in 2025 and is projected to reach approximately USD 7,048.08 Million by 2032, reflecting a compound annual growth rate of roughly 6.35% across the forecast horizon. This briefing highlights the report’s strategic value for executive teams planning capacity, sourcing, product development, and M&A in 2026, while preserving the report’s proprietary segmentation detail to encourage full-report engagement.
Worldwide Retangular Enameled Wire Market
Why this matters for 2026 strategy
- Timing of investments. The mid-2020s represent an inflection where demand vectors (electrification, industrial modernization, renewables) create sustained structural growth rather than short cyclical upticks. Capital allocations to capacity, tooling, or productization undertaken in 2026 will realize utilization and margin benefits throughout the 2026–2032 growth window.
- Sourcing and input-cost exposure. With upstream volatility (notably copper and specialty enamel resins) material decisions made now will determine cost competitiveness for several years. Our scenario analyses quantify payback sensitivity to raw material swings — essential input to risk-adjusted capital plans.
- Regulatory and tariff posture. Compliance and trade risk are non-trivial. Regulatory changes and tariff regimes are shifting supplier economics; the right regulatory roadmap and customs strategy can unlock near-term supply advantages or avert costly rework.
Market trajectory and what the numbers tell us
Our topline metrics show a clear structural upward trajectory: 2020–2025 was a period of steady expansion, with market value rising from USD 3.42 billion to USD 4.58 billion. The base-year assessment (2025) and our forecast to 2032 indicate a continuation of that trend, with the market expected to exceed USD 7.0 billion by the end of the forecast period at an aggregate growth rate of about 6.35%.
Worldwide Retangular Enameled Wire Market
Interpretively, this growth is being underwritten by demand for higher-efficiency electric machines, denser motor windings for EV traction and industrial drives, and increased electrification in utilities and renewables. However, growth is not uniform: product-grade innovation (higher thermal class enamels, thinner gauges, rectangular geometries optimized for automated winding) and regional policy choices will produce pockets of premium pricing and accelerated adoption.
Worldwide Retangular Enameled Wire Market
Competitive landscape — dynamics for 2026
The market is moderately concentrated: our concentration metrics show that the top three players hold a material but not dominant share, and the top five consolidate a meaningful portion of revenue. This structure leaves space for both incumbent scale players and focused specialists to capture differentiated value.
- Elektrisola Drähtefabrik GmbH & Co. KG (Stolberg, Germany) — a global specialist in fine and rectangular enameled wires with strong technology depth in high-performance motors and high-temperature grades. Their product roadmap and investments in advanced enamels position them as a go-to partner for OEMs seeking thermal and electrical performance.
- Superior Essex Magnet Wire (Fort Wayne, USA) — a large-scale producer with recent capital commitments targeted at EV motor demand. Their announced capacity expansion in 2024 underscores the strategic bet on localized production to serve North American EV OEMs.
- Rea Magnet Wire Company, LLC (Scranton, USA) — focused on custom solutions; a preferred source for complex motor and generator projects, particularly where specification flexibility matters.
- Fujikura Ltd. (Tokyo, Japan) and Furukawa Electric Co., Ltd. (Tokyo, Japan) — both bring advanced insulation and integration capabilities for automotive and high-voltage use-cases, with Furukawa’s partnerships and footprint expansions aimed at North American EV supply chains.
- Regional specialists such as Sam Dong (South Korea), Tongling Jingda (China) and Shanghai Shenghua (China) — supply resilient regional capacity and cost-competitive options, particularly for appliance, industrial, and domestically-focused EV manufacturers.
Recent corporate moves underscore two strategic themes: (1) capacity and geographic realignment to be closer to EV and industrial OEM clusters (e.g., production increases in the U.S. and Mexico); and (2) product differentiation through higher-temperature-capable enamels and tighter gauge control for automated winding. For 2026, buyers and competitors should expect continued investment in both scale and premium-grade products.
Key market dynamics shaping 2026 decisions
- Input-cost volatility: Spot and contract copper prices have observed meaningful increases, and specialty enamel resin costs have risen on petrochemical feedstock constraints. These shifts compress margins for commodity-grade producers and incentivize vertical integration or hedging strategies for larger players.
- Regulatory constraints: Global thermal-class and enamel-adhesion standards (e.g., IEC 60317) drive qualification timelines and testing regimes. Additionally, regional chemical regulations (for example, restrictions on certain plasticizers under EU frameworks) require reformulation investments for some enamel grades.
- Trade measures: Tariff regimes in major markets can create differential landed-costs that alter sourcing decisions. Firms should model duty-impacted scenarios when sizing near-term capacity and inventory policies.
- Customer application evolution: EV traction motors, power transformers, and high-efficiency industrial drives are shifting product mix toward higher-performance rectangular wires. OEMs are increasingly specifying higher thermal classes and tighter dimensional tolerances that favor producers with advanced R&D and consistent quality systems.
What PW Consulting’s report provides — practical, executable content
The study is structured to serve corporate strategy, commercial, and operations teams. Key deliverables include:
- Topline market sizing and validated time-series forecasts (2020–2032), with scenario and sensitivity modules tied to raw material and demand variables.
- End-user demand-driver analysis mapping electrification, industrial automation, and renewable generation to product-grade requirements and procurement cycles.
- Supply-side cataloguing: supplier capability matrices, capacity maps, technology differentiators, and quality-certification overlays to speed vendor selection and qualification.
- Cost and margin modeling templates that allow users to simulate commodity and resin price swings, tariff stress-tests, and localized labor-cost impacts on unit economics.
- Regulatory impact assessment with recommended compliance roadmaps and reformulation timelines for impacted enamel chemistry classes.
- Corporate strategy playbook: M&A screens, JV archetypes, and greenfield vs brownfield investment decision trees backed by NPV and IRR ranges under multiple demand scenarios.
- Commercial go-to-market tactics for OEM and Tier-1 engagement, including specification negotiation levers, qualification timelines, and premium-value capture strategies.
Note: The report includes granular segmentation tables, regional and application-level forecasts, and supplier-level benchmarking that are intentionally reserved for the full report package.
Strategic recommendations for 2026
- Lock partial raw-material coverage now. Given recent copper and resin price volatility, a hybrid hedging strategy combining medium-term contracts and spot positions reduces downside while retaining upside participation.
- Prioritize premium-grade capability. Investment in higher-temperature enamels and tighter geometric control yields better margin resilience as OEMs shift to more demanding motor architectures.
- Assess near-market capacity. For manufacturers serving high-growth EV clusters, proximity reduces landed costs and tariff exposure; evaluate brownfield expansion or JV options in target regions.
- Build regulatory and compliance agility. Allocate R&D and quality resources to accelerate qualification against IEC standards and evolving chemical restrictions to avoid lost sales windows.
- Use M&A selectively to acquire missing capabilities. Given the moderate top-five concentration, bolt-on acquisitions can rapidly add specialized grades, certification credentials, or regional manufacturing footprints.
How PW Consulting can accelerate your 2026 plan
Our report is designed to be decision-grade: actionable cost models, supplier shortlists, transaction screens, and regulatory roadmaps expedite strategy execution. For leadership teams evaluating capital allocation, procurement optimization, or M&A in 2026, the report serves as both the analytic backbone and the operational checklist to convert strategy into measurable outcomes.
To preserve the integrity of primary data and to encourage direct engagement with our full analysis, we have intentionally refrained from publishing the detailed segment-by-segment tables and supplier-level revenue figures in this briefing. The full report includes all granular forecasts, regional analyses, and downloadable financial models that underpin the recommendations summarized here.
Next steps
- Download the full Worldwide Rectangular Enameled Wire Market report for complete segmentation data, supplier scorecards, and the interactive financial model.
- Engage PW Consulting for a tailored workshop: we will map the report’s findings to your portfolio, run scenario stress-tests specific to your supply chain, and produce a 90-day execution roadmap.
PW Consulting remains committed to equipping clients with the granular, commercially actionable insights required to convert 2026 market opportunities into sustainable competitive advantage in the rectangular enameled wire value chain.
For detailed analysis of this topic, please visit the official page: Worldwide Retangular Enameled Wire Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com