

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
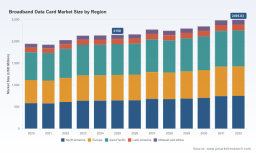
PW Consulting: Worldwide Broadband Data Card Market Poised to Reach USD 2,495.03 Million by 2032 on a 2.15% CAGR

Worldwide Broadband Data Card Market: Strategic Roadmap for 2026 — PW Consulting Release
Executive summary
PW Consulting’s new Worldwide Broadband Data Card Market report, with a 2025 base year and a forecast horizon through 2032, delivers a pragmatic, decision-focused perspective for corporate leaders planning capital allocation, product roadmaps, and go-to-market strategies in 2026. The global market — roughly USD 2.15 billion in 2025 — is projected to grow at a modest compound annual growth rate (CAGR) of 2.15% through the forecast window. That steady, low-single-digit expansion belies a nuanced set of structural shifts: 5G commercial rollouts, LTE persistence in legacy platforms, evolving device form-factors (M.2 and integrated modules), and the interplay between fixed broadband infrastructure and wireless broadband use cases.
Worldwide Broadband Data Card Market
Why this report matters for 2026 decision-making
-
Actionable foresight for portfolio strategy — We translate macro growth into practical guidance on where to prioritize R&D spend, which device form-factors require scale, and how to balance 5G investment with LTE lifecycle management to protect margins while avoiding stranded inventory risks.
Worldwide Broadband Data Card Market -
Go-to-market sequencing under regulatory uncertainty — With spectrum allocation and device certification timelines creating asymmetric launch windows across markets, the report maps timing-sensitive market entry options and contingency plans for delay-sensitive product launches.
Worldwide Broadband Data Card Market -
Supplier and component risk management — Component availability for radio front-ends, M.2 modules, and RF front-end integration remains a gating variable. Our analysis identifies where captive sourcing, strategic partnerships, or dual-sourcing materially alter time-to-market and TCO.
-
Commercial optimization playbook — We provide revenue capture levers (pricing architecture, bundled service partnerships, MVNO strategies) calibrated to the current mid-cycle growth environment so commercial teams can convert modest market expansion into above-market returns.
What’s in the report — pragmatic, operational content
This study is designed to be an operational manual for 2026. Key deliverables include:
-
Market sizing and scenario forecasts (base-year 2025, 2026–2032 outlook) with four demand scenarios that stress-test supply, regulation, and competitive disruption.
-
Product and deployment economics models that let readers simulate margin outcomes by form-factor (embedded modules, M.2 cards, mobile hotspots, USB/plug-in devices) and connectivity technology (LTE fallback, 5G sub-6 GHz strategy).
-
Go-to-market and channel playbooks for consumer, enterprise, and public-sector buyers — including partner archetypes, contract and pricing templates, and distribution priorities for urban vs. long-tail rural deployments.
-
Vendor benchmarking and technology scorecards covering radio performance, certification footprints, module integration ease, roadmap clarity, and supply-chain resilience.
-
Regulatory and spectrum impact assessment with mitigation plans for data sovereignty constraints, net neutrality developments, and certification timelines across critical markets.
-
M&A and partnership heatmaps highlighting strategic targets (component specialists, regional CPE makers, and software platforms) that can accelerate scale or expand addressable markets without heavy greenfield investment.
Market dynamics and the subtle growth story
The market’s projected steady trajectory masks a bifurcated landscape. On one hand, 5G is enabling differentiated enterprise and fixed-wireless access (FWA) use cases that demand higher-performing M.2 and integrated modules. On the other hand, FTTH penetration and legacy LTE deployments exert a dampening effect on unit growth in certain consumer segments. For decision-makers this creates both risk and optionality: investments targeted at high-value enterprise and industrial applications will capture disproportionate upside, while consumer-oriented product plays require tight cost control and channel discipline.
Competitive landscape — who to watch and why
The competitive structure is balanced: a handful of firms exert meaningful influence, but the market is not a closed oligopoly. Top-tier suppliers maintain strong engineering roadmaps and broad certification footprints, which creates barriers for late entrants but leaves space for specialist suppliers with targeted value propositions.
-
Huawei Technologies Co. Ltd. — A major OEM across mobile hotspots and integrated broadband cards, Huawei’s portable devices and SIM-enabled solutions continue to push performance per watt and user experience in markets where certification allows rapid commercial deployment.
-
Telit Cinterion (now under Semtech) — Focused on M.2 5G modules with LTE fallback and GNSS capabilities, positioning its products for fixed wireless access, enterprise routers, and vehicle connectivity where integration flexibility and multi-network support are decisive.
-
Sierra Wireless (now part of Semtech) — Brings multi-network 5G modules and system-level integration experience for mobile broadband and IoT, serving customers who need field-proven module-to-application continuity.
-
Inseego and Netgear — Both are focused on mobile hotspot and MiFi product lines, with an emphasis on user experience, ease of SIM management, and consumer/SMB distribution. Their differentiation lies in device firmware, management portals, and channel relationships.
-
ZTE, Quectel, Fibocom — These vendors play to strengths in module manufacturing scale, form-factor variety, and OEM partnerships, supporting CPE, industrial routers, and embedded use cases where price-performance and certification breadth matter.
Our vendor scorecards in the report evaluate these players on multi-dimensional criteria — technology roadmap, certification coverage, supply-chain resilience, and commercial flexibility — and recommend partner archetypes for different corporate priorities (speed-to-market, cost leadership, bespoke integration).
Regulation, infrastructure, and systemic risks
Several cross-cutting factors will materially affect 2026 decisions:
-
Net neutrality and open-internet policy continue to shape commercial terms and pricing strategies for bundled connectivity offerings.
-
Data sovereignty and local regulation increase compliance costs for international deployments, particularly for MVNO and IoT service models that rely on third-party SIM provisioning.
-
Spectrum allocation and device certification timelines amplify obsolescence risk for 4G/5G product lines; firms must factor certification lag into product launch calendars.
-
Parallel infrastructure trends — rising FTTH penetration globally — shift some consumer demand away from wireless-only solutions and elevate the strategic value of hybrid offers and seamless fallback experiences.
Strategic recommendations for 2026
-
Prioritize modular product architectures: Design platforms that can accept swappable radio modules to extend product life across certification cycles and regional spectrum variants.
-
Target enterprise and industrial segments where differentiated connectivity (QoS, SLA-backed FWA) and verticalized solutions command healthier margins and justify bespoke integration.
-
Invest selectively in software and device management ecosystems to turn hardware into recurring revenue engines through subscription services, device management, and carrier partnerships.
-
Implement a dual-sourcing approach for critical RF components and modules to mitigate supply-chain volatility without surrendering cost competitiveness.
-
Design certification-first launch plans: Align product roadmaps to prioritized certification paths and build regulatory monitoring into the product development lifecycle to avoid market-entry delays.
-
Assess inorganic opportunities strategically: Look for tuck-ins that provide market access (regional CPE specialists, platform software providers) rather than scale-only acquisitions that increase complexity.
How to use the report
Executives, product leads, M&A teams, and commercial strategists will find distinct, operational outputs in the report: scenario-based revenue models, supplier negotiation playbooks, certification calendars, and vendor scorecards. The document is structured to support rapid decision cycles: executive summaries for board briefings, one-page playbooks for product teams, and appendices with methodology and data lineage for finance and audit.
About the analytical approach and what’s intentionally excluded here
Our methodology combines primary interviews with device OEMs, module vendors, tier-1 carriers, and component suppliers, with a demand-side synthesis informed by installed base dynamics and infrastructure trends. For this public release we deliberately withhold detailed segment-level numbers and regional/application splits to preserve the report’s role as the definitive source for downstream commercial planning — the full data tables, segment breakouts, and supplier revenue curves are available in the paid report.
Conclusion & next steps
In a market characterized by modest aggregate growth but concentrated pockets of high strategic value, 2026 will be a year where execution precision outpaces scale. Companies that align architecture flexibility, certification planning, and channel economics will convert incremental market growth into sustained commercial advantage. PW Consulting’s Worldwide Broadband Data Card Market report is built to be the tactical compass for that execution. For the full data suite, vendor scorecards, and downloadable scenario models, access the report landing page and obtain the complete research package.
For detailed analysis of this topic, please visit the official page: Worldwide Broadband Data Card Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com