

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecast: Worldwide Single Point Anchor Reservoir Market to Rise from USD 1,420.5 Million in 2025 to USD 2,059.53 Million by 2032 at a 5.45% CAGR

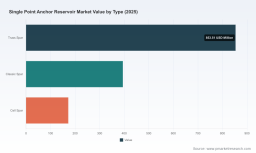
Worldwide Single Point Anchor Reservoir Market — 2026 Strategic Briefing
PW Consulting today releases a strategic preview of its forthcoming Worldwide Single Point Anchor Reservoir Market research report. Designed for C-suite leaders, project directors, and strategic planners preparing for 2026 decision cycles, this briefing synthesizes the report’s most consequential, actionable insights while preserving the granular data available only in the full publication.
Worldwide Single Point Anchor Reservoir Market
Why this market matters in 2026
Single point anchor reservoirs (SPARs) remain a critical enabling technology across a changing offshore landscape. Over the five years to 2025 the global market expanded meaningfully, moving from an estimated USD 1,089.45 Million in 2020 to USD 1,420.50 Million in 2025. Our baseline projects continued, steady growth through the 2026–2032 forecast window, culminating in an estimated USD 2,059.53 Million by 2032 — an implied compound annual growth rate (CAGR) of 5.45% for the forecast period.
Worldwide Single Point Anchor Reservoir Market
That growth trajectory is less about a single driver and more about the intersection of multiple structural forces: portfolio rebalancing among majors, the push to unlock deeper and higher-pressure reservoirs, and the early-stage incorporation of floating renewables into traditional supply chains. For organizations planning capital allocation and strategic partnerships in 2026, these dynamics translate into distinct windows of opportunity — and risk — which the full report quantifies and operationalizes.
Worldwide Single Point Anchor Reservoir Market
What PW Consulting’s report delivers — practical, decision-grade intelligence
- Proprietary market model: A bottom-up revenue model covering the historical period (2020–2025) and a detailed forecast (2026–2032) with scenario toggles for price, deployment rate, and technology adoption.
- Investment playbooks: Capex phasing and ROI sensitivity analyses that translate macro growth into specific timing recommendations for greenfield projects, FPSO integrations, and retrofits.
- Supply chain diagnostics: A practical supplier and fabricator scorecard, lead‑time heat maps, and alternative sourcing pathways to de-risk long-lead components within a two- to four-year procurement horizon.
- Regulatory and permitting matrix: Regional compliance frameworks, permitting timelines, and policy-trigger scenarios that materially affect deployment schedules and contract structuring.
- Commercial strategies: Tender design, contract clauses, and pricing models tailored to mitigate volatility in steel, fabrication, and logistics costs while preserving margin.
- Technology and integration guidance: Comparative assessments of SPAR subtypes, mooring architectures, and integration pathways with floating wind and subsea production systems (note: the report highlights relative strengths and trade-offs; it deliberately withholds granular subsegment revenue tables in this preview to preserve competitive value).
Concentration and competitive dynamics — what to expect
The market exhibits moderate concentration: the top-three firms collectively control approximately 42.5% of market revenue, while the top-five account for roughly 61.25%. This structure creates a two-speed competitive environment in which established engineering-and-fabrication integrators retain significant pricing and delivery power, while specialized mid‑tier suppliers and new entrants compete on modularity, speed-to-deploy, and niche technical differentiators.
Strategic implications for 2026:
- Incumbents will prioritize integrated project delivery models and long-term supply agreements to secure fabrication capacity and protect margins.
- Mid-tier players can capture value through focused capabilities — e.g., innovative mooring solutions, rapid-installation modules, or lifecycle services — but must demonstrate repeatable performance records to win tier-one buyers.
- Private equity and strategic investors will find arbitrage in consolidation plays where operational scale can be combined with advanced manufacturing to compress lead times and cost curves.
Key market dynamics shaping tactical choices
Three interlocking dynamics will define the 2026 decision environment:
- Deployment cadence vs. fabrication capacity: Fabrication yards remain the critical choke point. Buyers that lock conditional capacity or adopt modularization can reduce schedule risk and avoid inflationary tender cycles.
- Cross-sector convergence: The initial coupling of floating offshore wind supply chains with oil and gas SPAR systems is creating both competition for yard capacity and opportunities for shared logistics and standards—buyers that proactively develop cross-sector alliances can secure preferential access to resources.
- Regulatory and contractual risk transfer: With increasing scrutiny on offshore operations and local content regimes in key markets, contract structures must be rebalanced to allocate permitting, environmental and decommissioning risk more explicitly between sponsors and suppliers.
How PW Consulting’s scenarios inform 2026 decisions
The report provides three practical scenarios—Conservative, Base, and Accelerated—that translate macro assumptions into actionable outcomes at the project and portfolio levels. Each scenario includes:
- Quantified impacts on revenue timing and supplier capacity utilization;
- Trigger points for contract renegotiation or capital reallocation;
- Recommendations for hedging strategies across procurement, financing, and insurance;
- Early-warning indicators to monitor in 2026 (e.g., tender backlog velocity, yard utilization rates, key raw-material index spreads).
For executives, the value is immediate: scenario outputs show not just what might happen to topline demand, but how procurement windows, financing rounds, and partnership timetables must shift to optimize NPV under each plausible future.
Practical recommendations for 2026 planning
Based on our analysis, PW Consulting recommends the following actions for stakeholders preparing decisions in 2026:
- Lock conditional fabrication capacity: Negotiate shortlist agreements with yards that include escalation clauses tied to pre-agreed indices instead of fixed-price long‑term contracts.
- Modularize scope where possible: Decompose large SPAR deliveries into deliverable modules to shorten critical-path manufacturing and reduce single-supplier dependency.
- Prioritize early supplier integration: Move key suppliers into front-end engineering and design (FEED) stages to align lead times and reduce change orders.
- Hedge regulatory risk: Use staged permitting commitments and create contractual pass-throughs for jurisdictional policy changes to limit sponsor exposure.
- Explore cross-sector alliances: Identify floating renewables partners to co-locate fabrication and logistics services and realize shared cost synergies.
- Prepare an exit/scale play: Define clear KPI thresholds for accelerating capex, pursuing bolt-on acquisitions, or divesting marginal assets as scenarios unfold.
What’s intentionally withheld in this preview — and why
To preserve the actionable advantage for subscribers and paying clients, this briefing intentionally omits the report’s most granular subsegment tables — including detailed region-by-region and application-by-application revenue splits, vendor-level market shares, and line-item pricing schedules. The full report contains these datasets, downloadable models, and editable dashboards that enable direct application to your project financials, tender evaluations, and M&A screens.
Who should read the full report
- Corporate strategy teams at E&P companies planning deepwater or floating renewable integrations.
- Procurement and supply chain executives seeking to optimize sourcing and yard allocation strategies for 2026 bids.
- Investors and private equity sponsors evaluating roll-up or growth equity opportunities in fabrication and engineering niches.
- Project finance teams requiring transparent scenario-testing for covenant design and cashflow modeling.
About PW Consulting’s methodology
PW Consulting’s market model synthesizes a multi-source evidence base: vendor disclosures, project procurement notices, yard capacity audits, and interviews with procurement leads across operators and integrators. Coverage includes a detailed historical run (2020–2025), a base-year alignment at 2025, and forecast scenarios for 2026–2032. Our concentration metrics (CR3 ~42.5%; CR5 ~61.25%) are calculated from supplier revenue estimates captured in the model and validated against multiple independent sources.
Next steps — where to get the full intelligence
This preview is intended as a strategic primer. For teams that must translate market trends into executable 2026 plans, the full report is the operational toolkit: editable financial models, supplier scorecards, procurement templates, and scenario dashboards. To access the complete Worldwide Single Point Anchor Reservoir Market report, supporting datasets, and bespoke consulting engagements, visit our report page or contact PW Consulting’s industry team to schedule a briefing.
PW Consulting remains available to run tailored workshops that convert these insights into procurement strategies, portfolio optimization plans, and risk mitigation programs timed to your 2026 decision milestones.
For detailed analysis of this topic, please visit the official page: Worldwide Single Point Anchor Reservoir Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com