

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Rectangular Enameled Wire Market at USD 4.58B in 2025 — Asia‑Pacific Leads with USD 2.46B, EV Motors Drive USD 1.83B Demand; 6.35% CAGR Projected to 2032 (CR5 41.2%)

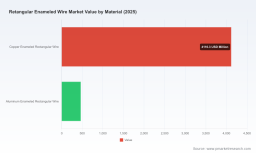
Worldwide Rectangular Enameled Wire Market — Strategic Briefing for 2026 Decision-Makers
PW Consulting’s latest market study on the Worldwide Rectangular Enameled Wire market (base year 2025) synthesizes five years of historical behavior (2020–2025) and delivers a forward-looking forecast through 2032. The market has expanded from an estimated USD 3,420.5 Million in 2020 to USD 4,580.45 Million in 2025 and is projected to reach approximately USD 7,048.08 Million by 2032, reflecting a compound annual growth rate of roughly 6.35% across the forecast horizon. This briefing highlights the report’s strategic value for executive teams planning capacity, sourcing, product development, and M&A in 2026, while preserving the report’s proprietary segmentation detail to encourage full-report engagement.
Worldwide Retangular Enameled Wire Market
Why this matters for 2026 strategy
- Timing of investments. The mid-2020s represent an inflection where demand vectors (electrification, industrial modernization, renewables) create sustained structural growth rather than short cyclical upticks. Capital allocations to capacity, tooling, or productization undertaken in 2026 will realize utilization and margin benefits throughout the 2026–2032 growth window.
- Sourcing and input-cost exposure. With upstream volatility (notably copper and specialty enamel resins) material decisions made now will determine cost competitiveness for several years. Our scenario analyses quantify payback sensitivity to raw material swings — essential input to risk-adjusted capital plans.
- Regulatory and tariff posture. Compliance and trade risk are non-trivial. Regulatory changes and tariff regimes are shifting supplier economics; the right regulatory roadmap and customs strategy can unlock near-term supply advantages or avert costly rework.
Market trajectory and what the numbers tell us
Our topline metrics show a clear structural upward trajectory: 2020–2025 was a period of steady expansion, with market value rising from USD 3.42 billion to USD 4.58 billion. The base-year assessment (2025) and our forecast to 2032 indicate a continuation of that trend, with the market expected to exceed USD 7.0 billion by the end of the forecast period at an aggregate growth rate of about 6.35%.
Worldwide Retangular Enameled Wire Market
Interpretively, this growth is being underwritten by demand for higher-efficiency electric machines, denser motor windings for EV traction and industrial drives, and increased electrification in utilities and renewables. However, growth is not uniform: product-grade innovation (higher thermal class enamels, thinner gauges, rectangular geometries optimized for automated winding) and regional policy choices will produce pockets of premium pricing and accelerated adoption.
Worldwide Retangular Enameled Wire Market
Competitive landscape — dynamics for 2026
The market is moderately concentrated: our concentration metrics show that the top three players hold a material but not dominant share, and the top five consolidate a meaningful portion of revenue. This structure leaves space for both incumbent scale players and focused specialists to capture differentiated value.
- Elektrisola Drähtefabrik GmbH & Co. KG (Stolberg, Germany) — a global specialist in fine and rectangular enameled wires with strong technology depth in high-performance motors and high-temperature grades. Their product roadmap and investments in advanced enamels position them as a go-to partner for OEMs seeking thermal and electrical performance.
- Superior Essex Magnet Wire (Fort Wayne, USA) — a large-scale producer with recent capital commitments targeted at EV motor demand. Their announced capacity expansion in 2024 underscores the strategic bet on localized production to serve North American EV OEMs.
- Rea Magnet Wire Company, LLC (Scranton, USA) — focused on custom solutions; a preferred source for complex motor and generator projects, particularly where specification flexibility matters.
- Fujikura Ltd. (Tokyo, Japan) and Furukawa Electric Co., Ltd. (Tokyo, Japan) — both bring advanced insulation and integration capabilities for automotive and high-voltage use-cases, with Furukawa’s partnerships and footprint expansions aimed at North American EV supply chains.
- Regional specialists such as Sam Dong (South Korea), Tongling Jingda (China) and Shanghai Shenghua (China) — supply resilient regional capacity and cost-competitive options, particularly for appliance, industrial, and domestically-focused EV manufacturers.
Recent corporate moves underscore two strategic themes: (1) capacity and geographic realignment to be closer to EV and industrial OEM clusters (e.g., production increases in the U.S. and Mexico); and (2) product differentiation through higher-temperature-capable enamels and tighter gauge control for automated winding. For 2026, buyers and competitors should expect continued investment in both scale and premium-grade products.
Key market dynamics shaping 2026 decisions
- Input-cost volatility: Spot and contract copper prices have observed meaningful increases, and specialty enamel resin costs have risen on petrochemical feedstock constraints. These shifts compress margins for commodity-grade producers and incentivize vertical integration or hedging strategies for larger players.
- Regulatory constraints: Global thermal-class and enamel-adhesion standards (e.g., IEC 60317) drive qualification timelines and testing regimes. Additionally, regional chemical regulations (for example, restrictions on certain plasticizers under EU frameworks) require reformulation investments for some enamel grades.
- Trade measures: Tariff regimes in major markets can create differential landed-costs that alter sourcing decisions. Firms should model duty-impacted scenarios when sizing near-term capacity and inventory policies.
- Customer application evolution: EV traction motors, power transformers, and high-efficiency industrial drives are shifting product mix toward higher-performance rectangular wires. OEMs are increasingly specifying higher thermal classes and tighter dimensional tolerances that favor producers with advanced R&D and consistent quality systems.
What PW Consulting’s report provides — practical, executable content
The study is structured to serve corporate strategy, commercial, and operations teams. Key deliverables include:
- Topline market sizing and validated time-series forecasts (2020–2032), with scenario and sensitivity modules tied to raw material and demand variables.
- End-user demand-driver analysis mapping electrification, industrial automation, and renewable generation to product-grade requirements and procurement cycles.
- Supply-side cataloguing: supplier capability matrices, capacity maps, technology differentiators, and quality-certification overlays to speed vendor selection and qualification.
- Cost and margin modeling templates that allow users to simulate commodity and resin price swings, tariff stress-tests, and localized labor-cost impacts on unit economics.
- Regulatory impact assessment with recommended compliance roadmaps and reformulation timelines for impacted enamel chemistry classes.
- Corporate strategy playbook: M&A screens, JV archetypes, and greenfield vs brownfield investment decision trees backed by NPV and IRR ranges under multiple demand scenarios.
- Commercial go-to-market tactics for OEM and Tier-1 engagement, including specification negotiation levers, qualification timelines, and premium-value capture strategies.
Note: The report includes granular segmentation tables, regional and application-level forecasts, and supplier-level benchmarking that are intentionally reserved for the full report package.
Strategic recommendations for 2026
- Lock partial raw-material coverage now. Given recent copper and resin price volatility, a hybrid hedging strategy combining medium-term contracts and spot positions reduces downside while retaining upside participation.
- Prioritize premium-grade capability. Investment in higher-temperature enamels and tighter geometric control yields better margin resilience as OEMs shift to more demanding motor architectures.
- Assess near-market capacity. For manufacturers serving high-growth EV clusters, proximity reduces landed costs and tariff exposure; evaluate brownfield expansion or JV options in target regions.
- Build regulatory and compliance agility. Allocate R&D and quality resources to accelerate qualification against IEC standards and evolving chemical restrictions to avoid lost sales windows.
- Use M&A selectively to acquire missing capabilities. Given the moderate top-five concentration, bolt-on acquisitions can rapidly add specialized grades, certification credentials, or regional manufacturing footprints.
How PW Consulting can accelerate your 2026 plan
Our report is designed to be decision-grade: actionable cost models, supplier shortlists, transaction screens, and regulatory roadmaps expedite strategy execution. For leadership teams evaluating capital allocation, procurement optimization, or M&A in 2026, the report serves as both the analytic backbone and the operational checklist to convert strategy into measurable outcomes.
To preserve the integrity of primary data and to encourage direct engagement with our full analysis, we have intentionally refrained from publishing the detailed segment-by-segment tables and supplier-level revenue figures in this briefing. The full report includes all granular forecasts, regional analyses, and downloadable financial models that underpin the recommendations summarized here.
Next steps
- Download the full Worldwide Rectangular Enameled Wire Market report for complete segmentation data, supplier scorecards, and the interactive financial model.
- Engage PW Consulting for a tailored workshop: we will map the report’s findings to your portfolio, run scenario stress-tests specific to your supply chain, and produce a 90-day execution roadmap.
PW Consulting remains committed to equipping clients with the granular, commercially actionable insights required to convert 2026 market opportunities into sustainable competitive advantage in the rectangular enameled wire value chain.
For detailed analysis of this topic, please visit the official page: Worldwide Retangular Enameled Wire Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com