

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Enzymes for Biofuels Market to Reach USD 1.89 Billion in 2025, Poised for 6.51% CAGR Through 2026–2032

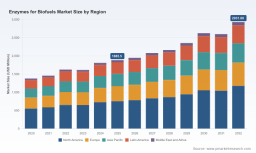
Worldwide Enzymes for Biofuels Market — Strategic Outlook 2026: What Global Energy and Industrial Leaders Need to Know
Executive preview
As energy transition pathways accelerate, enzymatic solutions for biofuels are moving from niche technical enablers to strategic levers for decarbonization, cost reduction and feedstock diversification. PW Consulting’s latest market study — built on a 2020–2025 historical baseline and projecting through 2026–2032 — quantifies this shift and translates it into decision-ready insight for executives, investors and policy teams preparing plans in 2026.
Worldwide Enzymes for Biofuels Market
The worldwide market for enzymes used in biofuel production grew from roughly USD 1.38 billion in 2020 to about USD 1.89 billion in 2025, and our forecast sees continued expansion to nearly USD 2.93 billion by 2032, reflecting a compound annual growth rate (CAGR) of 6.51% across the 2026–2032 projection window. These headline trajectories underline two simultaneous realities: steady baseline demand from established starch-based ethanol value chains, and accelerating upside from second‑generation (lignocellulosic) and enzymatic biodiesel routes as policy, feedstock innovation and enzyme engineering converge.
Worldwide Enzymes for Biofuels Market
Why this study matters for 2026 decision cycles
- Actionable timing (2026 as the inflection year): regulators and obligation frameworks set for 2026–2027 create a new planning horizon for procurement, capex and product development — our modeling maps those policy pivots to enzyme demand, margin outcomes and ROI windows.
- Risk-to-return triage for management teams: by quantifying technology, feedstock and market concentration risks, the report enables portfolio managers to prioritize investments with the best probability-adjusted returns.
- M&A and partnership surfacing: given the market’s concentrated supplier base, the analysis identifies capability gaps and high-value acquisition archetypes that can accelerate entry into advanced biofuels or broaden enzyme capability sets.
What the report contains — practical, consultative deliverables
This is not a catalog of numbers alone. The report is structured as a practitioner’s toolkit for 2026 action:
Worldwide Enzymes for Biofuels Market
- Market sizing and trenddrivers: end-to-end revenue trajectory from 2020 through our forecast horizon, with scenario modeling that isolates policy, raw material and technology adoption impacts on enzyme demand.
- Commercial and procurement playbooks: term structures, volume-flex clauses and pricing levers that buyers can use to mitigate volatility in enzyme input costs and raw material feedstocks.
- Technology readiness and value-chain roadmaps: comparative assessment of enzyme classes, process integration options, and likely deployment timelines for advanced cellulases and enzymatic transesterification at scale.
- Supply‑chain and input-cost stress tests: maps and simulations that show sensitivity to fermentation feedstock prices and the knock-on effects on manufacturer margins and cost pass-through to biofuel producers.
- Competitive and M&A diligence frameworks: profiles, capability matrices and acquisition target archetypes to accelerate internal evaluation and speed up diligence.
- Regulatory impact matrices and scenario playbooks: policy levers (including pending and published volumes under renewable fuel standards) translated into demand shocks and compliance cost curves.
- Customized advisory annexes: playbook modules for investors, midstream ethanol producers, integrated oil and gas companies evaluating biofuel conversion, and bioprocess equipment OEMs.
Competitive landscape — strategic implications of a concentrated supplier base
The enzyme-for-biofuels sector shows high market concentration, with our analysis indicating that the top three providers account for roughly two‑thirds of supply and the top five exceed four‑fifths of the market. That concentration has three practical effects for 2026 decision-making:
- Price and availability discipline: dominant suppliers can set commercial terms and prioritize contract fulfillment for strategic partners; buyers should prepare hedging and contracting strategies rather than rely on spot procurement.
- Innovation funnel control: large, integrated enzyme firms remain the primary investors in R&D, but targeted partnerships and licensing remain viable routes to access advanced capabilities quickly.
- Acquisition and counterparty risk: consolidation events or strategic exits can rapidly reconfigure competitive dynamics; monitoring M&A activity is essential for both suppliers and purchasers.
Key supplier profiles in the report synthesize market position, product strategy and strategic levers. Highlights include:
- Novonesis (formerly Novozymes) — a market leader offering comprehensive enzyme and yeast portfolios for both starch-based and fiber-based ethanol. Its strength is end-to-end process solutions (liquefaction, saccharification, biomass conversion) and sustainability positioning to reduce producers’ carbon footprints.
- Lallemand Biofuels & Distilled Spirits (LBDS) — following its acquisition of BASF’s bioenergy enzymes business in 2024, LBDS’s product set and developmental pipeline (including brand portfolios like Spartec®) enhance its relevance to grain processors and fuel ethanol producers.
- DuPont (Industrial Biosciences / IFF) — technology-driven offerings such as Accellerase emphasize lignocellulosic hydrolysis and starch processing efficiency; DuPont’s capabilities are optimized for scale deployments in corn- and cellulosic-based value chains.
- Regional and specialist players — firms like AB Enzymes, DSM‑Firmenich (Health & Biosciences), Codexis and a cohort of Indian, Japanese and North American specialists contribute differentiated capabilities: lower-cost formulations, engineered biocatalysts, lipase-driven biodiesel routes, and feedstock-integrated enzyme approaches.
The report examines how these providers compete across three dimensions: technical performance (e.g., activity per dose, thermostability), commercial model (licensing vs. supply vs. joint development), and geographic/service footprint (regional warehousing, on‑site formulation). For procurement and business development teams, knowing which suppliers excel on which dimension is a prerequisite to negotiating the right contract structure in 2026.
Market dynamics that will shape 2026 strategy
Our analysis synthesizes supply-side economics, policy drivers and technological evolution into a set of dynamics that should shape boardroom decisions in 2026:
- Raw‑material exposure: industrial enzyme manufacture depends heavily on fermentation feedstocks (glucose derived from corn or other starches). Raw material inputs account for a substantial share of manufacturing cost (industry estimates cluster in the 30–40% range). That creates a two‑way dependency: biomaterial producers influence enzyme costs, while enzyme demand competes with food and feed uses for the same commodities.
- Commodity price volatility: agricultural price swings materially affect enzyme margins and can create procurement discontinuities for biofuel producers. Scenario runs in the report show how different corn price trajectories translate into enzyme price pressure and, by extension, ethanol production economics.
- Regulatory acceleration for advanced biofuels: recent decisions on renewable fuel standards — including U.S. EPA volume requirements published for 2026–2027 — and global blending mandates create a predictable lift for cellulases and other enzymes that enable lignocellulosic ethanol. Policy certainty shortens investment payback horizons and alters capital allocation choices.
- Technological maturation and process integration: improvements in enzyme engineering, lower enzyme loading requirements, and novel process configurations (e.g., consolidated bioprocessing, enzymatic biodiesel production using lipases) are reducing operating costs and enabling new plant economics that were previously marginal.
Strategic recommendations for 2026
For executive teams preparing budgets, partnerships and M&A activity in 2026, the following priorities capture the highest-value, practical steps:
- Lock in supply through flexible long‑term agreements: prioritize contracts that incorporate volume flexibility, cost pass-through clauses tied to transparent indices, and built-in development pathways for next‑generation enzymes.
- Invest selectively in pilot commercialization of lignocellulosic pathways: allocate funding to demonstration projects with partners that provide enzyme co‑development — these projects will be the source of first-mover advantages as policy support matures.
- Hedge input exposure and diversify feedstock sources: develop feedstock diversification strategies and financial hedges that reduce sensitivity to single‑commodity price swings.
- Pursue capability gaps via bolt-on M&A or licensing: target mid‑sized, technology-focused enzyme firms or startups with novel biocatalysts or formulation expertise rather than broad horizontal consolidation; this approach preserves capital and accelerates access to differentiated performance.
- Embed regulatory scenario planning into capital allocation: stress-test investments against alternative RFS and global blending outcomes to avoid stranded capital in the event of slower-than-expected policy adoption.
How PW Consulting’s report supports execution
The study is designed to move leaders from insight to execution. Each chapter closes with specific decision frameworks — e.g., a procurement term checklist, a techno‑economic model template, and a target screening matrix for M&A. Methodologically, the work combines primary interviews with producers and suppliers, proprietary techno-economic modeling, and scenario sensitivity testing tied to regulatory timelines. Importantly, our public summary intentionally omits granular regional and application-level splits so that commercial clients can access full subsegment tables, supplier-by-supplier pricing scenarios and regional demand overlays through the full report package and advisory engagements.
Next steps
For firms that need to finalize 2026 procurement, capex or M&A decisions, the full report — and our accompanying advisory modules — deliver the granular inputs and bespoke scenario runs required for executable plans. Contact PW Consulting to commission tailored country or feedstock studies, supplier diligence projects, or integration roadmaps that convert the market’s macro trajectory into concrete commercial outcomes.
For detailed analysis of this topic, please visit the official page: Worldwide Enzymes for Biofuels Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com