

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting: Worldwide Arduino-Compatible Platform Market to Rise from USD 720 Million in 2025 to USD 1,250.05 Million by 2032 at an 8.19% CAGR
By pmarketresearch, 2026-07-17
Worldwide Arduino Compatible Platform Market — Strategic Preview for 2026 Decision-Makers
PW Consulting’s latest market study on the Worldwide Arduino Compatible Platform Market provides a strategic playbook for executives, product leaders, investors, and ecosystem partners preparing for 2026 and beyond. Built on a robust historical window (2020–2025) and a forward-looking forecast horizon (2026–2032), the report synthesizes quantitative forecasts and qualitative scenario analysis to surface practical actions that reduce execution risk and accelerate time-to-value. With the market growing at an expected compound annual growth rate (CAGR) of 8.19% from the 2025 base year, our analysis frames how the emerging inflection points in edge AI, hybrid compute architectures, and developer ecosystems will reshape competitive advantage.
Worldwide Arduino Compatible Platform Market
Macro Snapshot and What It Means for Strategy
Our base-year assessment (2025) and probability-weighted forecast through 2032 show sustained expansion driven by higher compute density at the edge, expanded use in industrial IoT and education, and broader adoption of Arduino-compatible ecosystems by OEMs and system integrators. The market’s projected growth trajectory is both an opportunity and a constraint: demand is expanding, but concentration metrics indicate room for both incumbents and well-positioned challengers. PW Consulting’s concentration analysis (CR3 and CR5 metrics) highlights a market where the top three and five players account for a meaningful yet not prohibitive share of revenue — creating a landscape that rewards smart partnerships, differentiated product portfolios, and developer engagement strategies.
Worldwide Arduino Compatible Platform Market
-
Growth dynamics: The market is expanding from the 2025 base and is expected to approximately reach mid-to-high triple-digit millions (USD, revenue unit: Million) by the end of the forecast window, reflecting the sustained demand for Arduino-compatible hardware that balances affordability with growing performance needs.
Worldwide Arduino Compatible Platform Market -
Concentration: CR3 and CR5 metrics show a market with moderate concentration — enough scale for leading vendors to shape standards and channels, but still open to nimble entrants and niche specialists focusing on form factor, performance, or vertical-tailored solutions.
Operational Value: What the Report Delivers
This report is designed to be directly operational for 2026 planning cycles. Rather than high-level hypothesis, PW Consulting provides a suite of decision-ready deliverables:
-
Executive dashboard with scenario-based revenue and margin implications under alternative hardware-cost and component-supply paths.
-
Probability-weighted demand models and interactive forecast sheets you can adapt to your product roadmap or regional rollout plan.
-
Go-to-market playbooks for channel, direct-to-education, and enterprise segments — including distributor selection frameworks and pricing-bundle levers tested against real-world use cases.
-
Supply-chain risk heatmaps and procurement hedging strategies for constrained MCU and wireless components.
-
M&A and partnership scoring matrices that help prioritize targets from development-tool vendors to high-margin niche-board makers.
-
Developer-ecosystem engagement templates and metrics for hackathons, SDK investments, and content strategies that drive adoption.
Competitive Landscape — Focused Briefs on Core Players
The market remains populated by a mix of legacy originators, community-driven hardware houses, and cost-focused manufacturers. Our report profiles the leading firms and analyzes recent moves that are changing competitive dynamics:
-
Arduino S.r.l. — The historic steward of the Arduino ecosystem has moved into new territory after strategic developments in 2025–2026. A significant corporate transition occurred in late 2025 when Qualcomm completed an acquisition, followed by the launch of hybrid Linux + real-time MCU offerings. In early 2026, Arduino (in collaboration with Qualcomm) broadened its edge AI and robotics credentials with new product introductions and developer programs. These moves accelerate a shift from hobbyist-first boards to platforms designed for perception, decision, and action at the edge — with important implications for partner selection, software stacks, and commercial licensing.
-
Seeed Studio — An OEM that prioritizes compact form factors and rapid sensor integration, with product families that emphasize modular connectors and developer convenience. Seeed’s approach lowers integration friction for IoT applications and shortens prototype-to-deployment cycles.
-
SparkFun Electronics and Adafruit Industries — Both U.S.-based companies combine strong community channels with distinct ecosystems (e.g., ecosystem-specific connectors, educational curricula, wearables). They remain influential in shaping maker and education demand and provide durable distribution channels for both boards and shields.
-
PJRC (Teensy series) — Positioned as a high-performance alternative within the Arduino-compatible universe, attractive to audio, fast-control, and compute-bound applications.
-
Elegoo and Keyestudio — Cost-effective manufacturers that supply starter kits and broad sensor catalogs for education and early-stage prototyping. Their scale in price-sensitive channels helps drive baseline volume and supports ecosystem experiments.
Across the competitive set, our analysis emphasizes three vectors that will determine winners in 2026: platform extensibility (hardware + software), developer mindshare, and tight supplier management for critical components.
Technology & Standards Dynamics — Practical Implications
Two technical and regulatory realities are shaping strategic options:
-
Standards and compatibility: Widespread adherence to prevalent form-factor and pinout standards continues to reduce integration risk for shield ecosystems and third-party modules. This means firms who invest in compatibility can capture downstream licensing and accessory revenue while preserving customer choice.
-
Trademark and IP considerations: Official trademark policies enable a thriving compatible-product market but impose naming and branding restrictions. Legally compliant third-party products can compete effectively provided they avoid naming that infringes on brand marks. This legal clarity should be part of any go-to-market risk assessment and supplier contract language.
Strategic Recommendations for 2026
PW Consulting prioritizes actions that balance speed to market with defensible differentiation. Our top recommendations:
-
Double down on edge AI capabilities where it aligns with your roadmap. If your product portfolio intersects with perception, robotics, or real-time decisioning, accelerate integration of hybrid compute platforms and secure preferential access to edge-optimized MCUs and SoCs.
-
Invest in developer velocity, not just marketing. Sponsor targeted developer contests, provide production-grade SDKs, and curate sample projects that map directly to enterprise use cases — converting hobbyist adoption into commercial proof points.
-
Build supply-chain resiliency into product economics. Hedge against component volatility with multi-sourcing and consider longer-term supplier agreements for critical components to protect margins.
-
Use partnerships strategically. For vendors without end-to-end systems competence, seek distribution and integration partnerships with established channel players in education and industrial automation to accelerate revenue and reduce GTM cost.
-
Apply IP and trademark discipline. Ensure product names, packaging, and marketing comply with trademark rules to avoid disruptive takedowns and channel friction.
Why PW Consulting’s Report is Timely
Transition events — platform-level acquisitions, hybrid board introductions, and amplified developer programs — create windows of opportunity for firms that move decisively. The 2026 planning cycle must reconcile immediate supply-and-demand realities with multi-year bets on compute, connectivity, and developer ecosystems. Our report translates market-scale forecasts and concentration metrics into executable roadmaps that reduce ambiguity and allocate capital to the highest-return initiatives.
How to Use This Preview — and What You’ll Find in the Full Report
This article is a strategic preview designed to show the depth of the analysis and the practicality of the recommendations while preserving the proprietary segmentation and granular forecasts that clients rely on. The full PW Consulting report includes region-, type-, and application-level forecasts, competitive benchmarks, proprietary scoring of M&A targets, downloadable financial model templates, and a library of primary-source interviews — all designed to be plugged directly into 2026 budgets and product plans.
-
Operational deliverables: downloadable Excel models, strategy playbooks, and supplier due-diligence checklists.
-
Decision tools: scenario navigator, sensitivity analysis, and go/no-go thresholds for product investments.
-
Actionable intelligence: priority vendor lists, partnership archetypes, and recommended KPIs for developer program ROI.
To access the full dataset, interactive models, and market segmentation that underpin these recommendations, please visit the PW Consulting report page for the Worldwide Arduino Compatible Platform Market. Purchasing the report unlocks the granular inputs and validated data required to finalize 2026 investment and operational plans.
PW Consulting brings a combination of industry-domain expertise, primary research, and strategy execution capability. Our Worldwide Arduino Compatible Platform Market study is structured to move teams from insight to impact during the 2026 planning and execution cycle.
For detailed analysis of this topic, please visit the official page: Worldwide Arduino Compatible Platform Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Graphene Chip Market to Expand at 24.5% CAGR — From USD 215 Million in 2025 to Nearly USD 1 Billion by 2032, Led by Asia Pacific (USD 84.3M)
By pmarketresearch, 2026-07-17
Graphene Chip Market: Strategic Imperatives for 2026 — PW Consulting Market Brief
Executive summary
PW Consulting’s newly released Graphene Chip Market report (base year 2025) frames graphene-enabled electronics as a rapidly scaling sub-market within the broader semiconductor and photonics ecosystem. After a six-year historical review (2020–2025), our baseline shows the market expanding from the low double-digit millions in 2020 to USD 215.0 Million (revenue unit: Million) in 2025. Under our central scenario, the market is forecast to grow at a 24.5% compound annual growth rate (CAGR) through a 2026–2032 forecast window, reaching just under USD 1.0 Billion (USD 996.85 Million) by 2032. The 2026 projection in the report — an early inflection point for commercial deployments — is USD 275.56 Million.
Graphene Chip Market
This press briefing presents the strategic takeaways that senior executives, technology investors, and corporate development teams should prioritize in 2026. In line with our “preview trailer” approach, we intentionally withhold granular regional and application-level splits from this summary to help readers assess strategic fit and then visit the full report for proprietary segmentation tables, unit economics, and vendor scorecards.
Graphene Chip Market
Why 2026 is a strategic inflection point
-
Maturing pilot lines and product launches. 2025–2026 activity shows conversion from lab demonstrations to pilot manufacturing and early commercial SKUs. Notable industry moves include wafer-scale production milestones and product introductions that shift graphene from specialty material to a component that can be designed into systems.
Graphene Chip Market -
Convergence of electronic and photonic integration. Developments in graphene photonics and interconnects point to differentiated value in high-speed communications, advanced sensing, and thermal management where traditional silicon approaches face scaling limits.
-
Policy and supply-chain reshaping. New export-control regimes and ongoing consolidation in foundry and equipment supply chains are changing the calculus for where to site capacity, which partners to engage, and how to manage inventory of critical materials and process tools.
Report contents — actionable modules
The full PW Consulting report is structured for decision makers who need executable insights, not just market forecasts. Key practical modules include:
-
Market-sizing and adoption scenarios: three forward-looking commercialization tracks (conservative, central, accelerated) with topline and unit forecasts by technology readiness level.
-
Technology readiness and integration playbooks: evaluation of GFETs, graphene interconnects, and thermal management architectures, including process roadmaps and recommended pilot-scale validation steps.
-
Manufacturing and cost-modeling toolkit: bottom-up cost curves for wafer-scale processing, foundry partnerships, and packaging pathways, plus sensitivity analysis for throughput and yield.
-
Supply-chain heatmap: critical equipment and raw-material dependency mapping, supplier risk scoring, and mitigation levers for constrained inputs.
-
Go-to-market and partner selection: OEM integration pathways, licensing templates, and partner-evaluation matrices to inform strategic alliances or M&A screening.
-
Regulatory and export-control playbook: jurisdictional implications, compliance checklists, and contingency plans for cross-border manufacturing and technology transfers.
-
Vendor and IP landscape: qualitative vendor benchmarking, patent-clustering insights, and a shortlist of strategic targets with supporting rationale.
Competitive landscape: what the leading players signal
The competitive field is still emerging, with a small set of specialist vendors progressing from materials and foundry services to device-level and system-level offerings. Our competitive analysis focuses on firms showing tangible manufacturing and commercialization milestones and identifies near-term strategic actions for incumbents and entrants.
-
Paragraf (Huntingdon, UK) — Paragraf’s commercial shift to silicon-wafer GFET processing and a recent product launch underscore a move toward mainstream semiconductor form factors. Their direct deposition approach and foundry-like service offering position them as a bridge between research platforms and volume-oriented supply. Strategic implication: system integrators should treat Paragraf as a candidate partner for early design-ins and as a supplier for pilot runs where contamination control and wafer compatibility are critical.
-
Graphenea (San Sebastian, Spain; US operations) — As a dedicated graphene foundry, Graphenea’s capabilities in CVD films and custom GFETs make them a natural partner for sensor OEMs and companies seeking repeatable material performance. Strategic implication: procurement teams will benefit from engaging Graphenea early to lock down film-specifications and co-develop reliability testing protocols.
-
Black Semiconductor (Aachen, Germany) — Focused on integrated graphene photonics and interconnects, Black Semiconductor’s progression toward a 300mm pilot line and automation partnerships signals ambition to serve hyperscale and telecom markets. Strategic implication: network and data-center OEMs should monitor their pilot outputs closely and consider joint validation programs around high-density interconnect performance.
-
Archer Materials (Sydney, Australia) — Working at the interface of quantum processors and biochips, Archer’s work demonstrates graphene’s cross-domain applicability. Strategic implication: R&D organizations in quantum and medical diagnostics should explore collaboration models that de-risk early-stage device integration.
-
Vorbeck Materials (Jessup, Maryland, USA) — With strength in conductive inks and composite components, Vorbeck is important for printed-electronics and hybrid integration use cases. Strategic implication: consumer-electronics OEMs and printed-sensor manufacturers should include Vorbeck in their supplier shortlist for form-factor-sensitive applications.
Our vendor analysis in the report also quantifies market concentration and competitive dynamics: the three largest players capture a meaningful—but not dominant—share of market value, while the top five represent a majority presence. This concentration profile suggests opportunities for both specialist suppliers and new entrants that can demonstrate superior integration economics or IP position.
Industry context and recent developments
-
Manufacturing milestones and product introductions in 2025–2026 are accelerating commercialization timelines. Examples include wafer-scale GFET production and pilot-line automation partnerships that tighten the link between materials science and fab-scale processes.
-
Regulatory shifts, including updated export-control lists, are increasing complexity for cross-border equipment and kit transfers. Corporates must embed compliance scenarios into their location and sourcing decisions.
-
Raw-material economics are improving: industrial-grade graphene nanoplatelets continue to decline in price as scaling occurs, which compresses component cost and supports broader end-market adoption.
-
Public-private consortia and multi-project wafer runs are actively lowering integration risk through shared pilot capacity and standards workstreams.
Strategic playbook for 2026 decision-makers
For executives making spend and partnership decisions this year, the following prioritized actions are derived from our scenario and sensitivity work:
-
Immediate (0–12 months) : Conduct disciplined pilot-vendor selection with contingency clauses; secure supply options for critical materials; initiate targeted IP and freedom-to-operate diligence for any planned integrations.
-
Near-term (12–24 months) : Co-fund pilot production runs with a selected foundry partner; standardize validation protocols across electrical, thermal, and reliability metrics; lock initial purchase agreements to hedge pricing and delivery risk.
-
Mid-term (24–60 months) : Decide on capacity strategy—build vs. partner—based on pilot yield roll-outs and TCO analyses; scale up integration efforts for products showing clear value capture; pursue M&A or joint-venture structures for securing proprietary process steps or unique materials.
Risk matrix — what to watch
-
Regulatory risk : Tightening export controls can affect equipment availability and cross-border transfer of process knowledge.
-
Supply-chain risk : Single-sourced process tools and specialty substrates remain a bottleneck in some manufacturing paths.
-
Technical integration risk : Yield and lifecycle reliability remain the primary technical gating items for system-level adoption.
-
Market adoption risk : End users will require demonstrable system-level ROI (throughput, energy, or form-factor) before switching from incumbent technologies.
How clients should use this report in 2026
Companies should treat the PW Consulting Graphene Chip Market report as a decision-support asset rather than a static forecast. Use it to:
-
Underpin capex and R&D budget allocations with scenario-ready financials and sensitivity analyses;
-
Prioritize pilot programs and vendor engagement based on quantified value-at-stake and integration complexity;
-
Frame M&A and partnership theses with vendor scorecards and IP-cluster mapping included in the full report;
-
Inform procurement and legal teams with a regulatory playbook tailored to cross-border supply and export control dynamics.
Next steps and how to obtain the full intelligence
This briefing deliberately outlines the strategic contours and operational levers that matter for 2026 while withholding the granular segmentation matrices, regional and application-level splits, and proprietary vendor scoring that are delivered in the complete report. PW Consulting clients and subscribers can access the full dataset, scenario toolkits, and tailored advisory workshops via our website and client portal.
For executives seeking a bespoke briefing—scenario workshops, workshop-facilitated vendor selection, or a bespoke due-diligence pack for potential investments—PW Consulting offers tailored advisory engagements to translate these market signals into executable programs.
Closing
Graphene-enabled chips have moved decisively from laboratory promise to early commercial reality. For companies that align product roadmaps, manufacturing intents, and regulatory strategies now, 2026 will be the year to secure optionality and competitive advantage as the market scales toward the billion-dollar horizon outlined in our forecast. PW Consulting’s full report provides the granular analytics and playbooks required to operationalize this insight.
For detailed analysis of this topic, please visit the official page: Graphene Chip Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Magnetic Carbon Nanofoam Market to Reach USD 73.88 Million by 2032, Growing at 6.22% CAGR (2026–2032) — North America Leads with USD 18.2M
By pmarketresearch, 2026-07-17
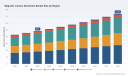
Worldwide Magnetic Carbon Nanofoam Market — Strategic Preview for 2026 Decision-Makers
As magnetic carbon nanofoam moves from laboratory curiosity toward early commercial deployments, strategic clarity will determine which organizations capture disproportionate value in the coming decade. PW Consulting’s new Worldwide Magnetic Carbon Nanofoam Market study (base year 2025; historical 2020–2025; forecast 2026–2032) synthesizes proprietary modeling, primary interviews and supply-chain validation to deliver a decision-grade intelligence package for 2026. This preview highlights the report’s most consequential, board-level takeaways while intentionally holding back granular segment-level tables and company-specific data to encourage direct access to the full study.
Worldwide Magnetic Carbon Nanofoam Market
Key macro takeaways you need now
-
Market scale and trajectory: The global magnetic carbon nanofoam market reached approximately USD 48.5 Million (USD Million unit, base year 2025) and is projected to expand to about USD 73.9 Million by 2032. Our base-case implies a compound annual growth rate of roughly 6.22% through the forecast horizon, reflecting steady commercialization across a set of high-value applications.
Worldwide Magnetic Carbon Nanofoam Market -
Recent momentum: After a measured build from 2020 to 2024, the market accelerated into 2025, with continued expansion expected in 2026 as pilot projects convert to low-volume production runs and early adopters refine integration pathways.
Worldwide Magnetic Carbon Nanofoam Market -
Concentration and competitive structure: Market concentration is moderate — the top three players account for roughly 38.4% of the market and the top five for around 52.1% — which signals both existing incumbent strength and meaningful room for new entrants that can differentiate on performance, cost or supply reliability.
Why 2026 is a strategic inflection point
2026 represents the first full year when several parallel vectors converge: cost reductions from scale-up, clearer regulatory pathways for advanced carbon materials, and growing industrial demand for compact, high-performance electromagnetic and catalytic solutions. For corporate decision-makers, this creates a narrow window to translate lab-level IP into defensible product platforms, secure supply relationships, and shape standards that will influence adoption economics for the rest of the decade.
What the report delivers — practical, executable intelligence
The PW Consulting report is structured as an action toolkit rather than a purely academic forecast. Key deliverables included in the full study are:
-
Validated market sizing and scenario forecasts (2026–2032), with sensitivity analyses for pricing, adoption rates and feedstock cost volatility.
-
Segment-level demand drivers and adoption roadmaps by application class, with quantified upside and downside scenarios (note: detailed segment tables are available in the full report).
-
Manufacturing and scale-up playbook — from pilot-line designs to capital intensity benchmarks and recommended process yields to reach target cost points.
-
Supply-chain heat map including critical inputs, choke points, and mitigation strategies (dual sourcing, backward integration, tolling partnerships).
-
Commercialization routes and go-to-market options: licensing vs. JV vs. captive production, with decision criteria tied to company capabilities and balance-sheet appetite.
-
Regulatory and sustainability checkpoints: lifecycle considerations, likely testing requirements, and reputational risk management steps needed before broad deployment.
-
Investment and M&A thesis: criteria for target screening, valuation sensitivities, and integration risks to watch during diligence.
-
Customer archetypes and procurement triggers: what end-users prioritize (performance, cost, reliability), and how procurement cycles vary across industries.
Competitive landscape — interpretation and implications
With a CR3 of ~38% and CR5 of ~52%, the market is neither a pure oligopoly nor highly fragmented. This structure produces three strategic implications for 2026:
-
Incumbent leverage exists: established players retain advantages in manufacturing know-how, quality control and pilot-to-scale transitions. For buyers, this means predictable supply but also potential price premiums.
-
Opportunity for challengers: differentiated performance (e.g., higher magnetic responsiveness, tailored microstructure for specific EM shielding profiles), lower total cost of ownership, or proprietary integration services can overcome incumbent advantages.
-
M&A and partnerships will matter: given the concentration levels, strategic acquisitions and JV models are the fastest path for mid-sized firms to acquire capability and market access without the time and capex burden of full greenfield scale-up.
Dominant market dynamics shaping value pools
Several cross-cutting trends determine who wins and who loses as the market grows:
-
Application-driven adoption: Demand originates from high-value applications where magnetic carbon nanofoam's combination of low density, tunable magnetic properties and surface area deliver distinctive performance advantages — particularly in electromagnetic interference shielding, environmental remediation catalysts and certain sensing functions. Timing and scale of demand differ across applications, which requires targeted commercial strategies rather than a one-size-fits-all approach.
-
Cost-to-performance curve: Early-stage production carries high per-unit costs. Commercial viability depends on pushing down costs through yield improvements, throughput gains and feedstock optimization. Companies that move the cost curve early will unlock much larger addressable opportunities.
-
Manufacturing complexity: Reproducibility and quality control at scale are non-trivial. Investment in process analytics, inline metrology and supply-chain redundancy will be differentiators for those seeking to serve sensitive industrial customers.
-
Regulatory and sustainability considerations: Lifecycle impacts, material safety, and end-of-life handling will shape procurement decisions for large industrial OEMs. Proactive engagement with regulators and adoption of third-party certifications can accelerate acceptance.
-
Standards and interoperability: Early movers can shape performance standards; firms that participate in standards committees will influence testing protocols and compliance thresholds, creating indirect barriers to late entrants.
Actionable strategic imperatives for 2026
Based on the models and interviews underpinning the report, PW Consulting recommends a prioritized set of actions for corporate leaders planning to act in 2026:
-
Set a clear go/no-go gate for commercialization by Q2 2026: require defined milestones around cost-per-unit, reproducibility, and at least one LOI from a credible OEM or systems integrator.
-
Invest in pilot-line capability with modular expansion: build capacity to validate process recipes at commercial throughput while preserving optionality for scale-up or exit via sale/JV.
-
Pursue targeted partnerships over broad distribution: align with a few strategic customers for co-development to de-risk applications and secure initial purchase commitments.
-
Lock down critical inputs and develop contingency plans: secure long-lead materials and consider toll-manufacturing arrangements to avoid early supply bottlenecks.
-
Adopt a layered IP strategy: protect core manufacturing know-how while using selective licensing to accelerate market adoption where appropriate.
-
Define sustainability and compliance roadmap: complete lifecycle assessments and third-party testing early to preempt procurement barriers with environmentally sensitive customers.
-
Align commercial incentives with customers: design pilot pricing and warranty structures that reduce buyer switching costs and build reference cases.
How PW Consulting helps translate insight into outcomes
Our practice blends sector specialists, process engineers and M&A advisors to help clients convert the study’s intelligence into concrete actions: bespoke due diligence, pilot-to-production roadmaps, negotiation support for JV or licensing agreements, and tailored commercial plays to win first-mover customers. The full report contains the granular segmentation, supplier lists, and company-level competitive benchmarking necessary to execute the recommendations outlined above.
Next steps for leaders who intend to act in 2026
If your 2026 plan includes investment, partnership, or a procurement strategy for magnetic carbon nanofoam, the most valuable immediate steps are:
-
Obtain the full PW Consulting study to access segment-level forecasts, supplier scoring, and the scenario matrices that drive capital allocation decisions.
-
Commission a short, focused technical audit to validate your processes against the manufacturing playbook in the report.
-
Schedule a strategic workshop with our industry team to convert the report’s high-level guidance into a 6–12 month execution plan tailored to your company’s capabilities and risk appetite.
Magnetic carbon nanofoam represents a distinctive emerging materials opportunity: modest market size today, but with concentrated pockets of high-margin demand and a clear pathway to scale. The choices made in 2026 — about partnerships, scale-up investments, IP posture and standards engagement — will determine who captures the majority of the value as the market matures through 2032. For full access to the report’s datasets, detailed segment analyses, and company-level competitive profiling, please refer to the PW Consulting publication page.
For detailed analysis of this topic, please visit the official page: Worldwide Magnetic Carbon Nanofoam Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Specialty Oxidant Market to Reach USD 4,567.02 Million by 2032, Growing at a 5.45% CAGR (2026–2032)
By pmarketresearch, 2026-07-17
Worldwide Specialty Oxidant Market — Strategic Outlook 2026: PW Consulting Release
Executive summary
PW Consulting’s new Worldwide Specialty Oxidant Market report provides corporate leaders with the strategic context and operational playbook they need to act confidently in 2026. The global specialty oxidant market reached an estimated USD 3,150.0 Million in our base year (2025) and is modeled to grow at a compound annual growth rate (CAGR) of 5.45% over the 2026–2032 forecast horizon, reaching roughly USD 4.57 Billion by 2032 under our central case. This growth reflects persistent demand from high-purity industrial applications, accelerated decarbonization investment, and shifting remediation and water-treatment priorities.
Worldwide Specialty Oxidant Market
Why 2026 is a strategic inflection point
-
Capacity rebalancing and localization: Several incumbent suppliers are completing targeted capacity investments or product launches that materially alter regional supply dynamics. These moves compress near-term arbitrage opportunities while creating new pathways for long-term differentiation based on product grade and sustainable credentials.
Worldwide Specialty Oxidant Market -
Feedstock and energy volatility: Production of key oxidants remains anchored to energy- and feedstock-intensive chemistries. Our analysis shows that AO-based hydrogen peroxide production is particularly exposed to natural gas, electricity, and anthraquinone carrier dynamics—risk factors that will drive margin divergence between low-cost incumbents and nascent low-carbon offerings.
Worldwide Specialty Oxidant Market -
Regulatory and logistics cost shock: Tightening regulation on high-strength peroxide grades (notably rules affecting explosives-precursor control in parts of Europe and adjacent regions) has increased distribution complexity and cost for certain grades. Commercial teams must factor these distribution overlays into 2026 pricing, contract design, and go-to-market plans.
Key market signals captured in the report
-
Market momentum: The market has demonstrated steady recovery and expansion since the 2020–2025 period. Our supply-demand modelling indicates structural growth driven by electronics-grade oxidants, remediation-focused persulfates, and an incremental premium for low-carbon H2O2.
-
Price and inventory indicators: Regional spot-price swings and inventory adjustments remain a leading indicator of near-term margins. For example, Indian industrial-grade hydrogen peroxide experienced meaningful price softening in Q3 2025 (reported regional reference bands) as inventories rebalanced—an early sign that demand segmentation is not uniform.
-
Concentration and competitive balance: Market concentration is moderate: the top-three and top-five suppliers account for meaningful shares, creating oligopolistic behaviors in certain product-grade bands and a fertile environment for targeted disintermediation or vertical integration plays.
Competitive landscape — what the leaders are doing
Our competitive profiling synthesizes public disclosures, plant-level capacity intelligence, product launches, and strategic signals from leading suppliers. Highlights include:
-
Nouryon — positioned as a specialty oxidant platform with a broad industry footprint. Recent product innovation with lower-carbon hydrogen peroxide variants signals an aggressive play to capture premium, sustainability-conscious customers in pulp & paper, mining, and water treatment.
-
Evonik — doubling down on high-purity specialty H2O2 for electronics and photovoltaics. A newly completed specialty-grade hydrogen peroxide plant in Leshan (trial production underway in 2026) introduces a sizeable, high-purity capacity that will reshape competitive dynamics in APAC for semiconductor-grade supply.
-
Solvay — continuing to expand high-purity output in China and to secure position in electronics and water-treatment markets via site-level capacity upgrades.
-
Arkema, BASF, Mitsubishi Gas Chemical, Kemira, Aditya Birla Chemicals and FMC — each leverages differentiated technologies or product portfolios (organic peroxides, persulfates, peracetic acid, specialty grades) to pursue vertical or specialty niches where margins and technical barriers are higher.
-
Market concentration metrics (CR3 and CR5) in our model underline a market where scale matters but where targeted product differentiation and local regulatory agility can outweigh pure scale in many commercial matchups.
Report contents — practical modules for decision-makers
PW Consulting’s report is built for action. The following functional modules translate market intelligence into executable initiatives for 2026:
-
Supply-demand and price modelling: plant-level capacity maps, utilization scenarios, and sensitivity runs tied to fuel and anthraquinone feedstock cost inputs.
-
Regulatory impact assessment: granular implications of transport and precursor controls across major trading corridors and how these change effective landed costs.
-
Feedstock risk dashboard: quantifies exposure to AO process inputs, anthracene price shocks (including observed uplifts), and electricity/gas cases across producer footprints.
-
Competitor matrix and capability heatmap: public and proprietary signals on new plants, product launches, JV structures, and low-carbon credentialing.
-
Commercial playbook: price architecture templates for long-term offtake, spot-inventory strategies, and customer segmentation that align grade, logistics, and contract tenor.
-
Operations & decarbonization pathways: CAPEX scheduling simulations for retrofit vs greenfield, and marginal abatement cost curves for electrification and feedstock switching.
-
M&A and partnership compass: targets and value-creation cases for bolt-on acquisitions, tolling agreements, and co-investment in localized high-purity capacity.
Strategic imperatives for 2026 — an executive checklist
-
Re-price with distribution overheads in mind. Incorporate regulatory-driven distribution adders into 2026 tariffs for certain grades and regions; short-term margin erosion will follow if not pre-priced.
-
Prioritize feedstock and energy hedges. Given the AO-process exposure to natural gas and anthraquinone carriers, procurement should implement layered hedges and strategic storage where cost-effective.
-
Invest selectively in specialty and low-carbon grades. Our market scenarios show higher-than-average margin expansion for certified low-carbon hydrogen peroxide and high-purity electronic grades—areas where first-mover investments (or offtake-linked partnerships) can secure durable premiums.
-
De-risk logistics and compliance. For product bands facing tightened precursor controls, create alternate distribution pathways (domestic production, controlled cross-border corridors, or compliant intermediated logistics) to avoid commercial disruptions.
-
Refine portfolio by channel: separate commodity H2O2 plays from specialty oxidant propositions (persulfates, organic peroxides, chlorites/chlorates) and align sales incentives and service models accordingly.
-
Use M&A to buy capability, not just capacity. Targets that provide analytics, local distribution, or specialty-formulation know-how are higher-value than undifferentiated tonnage buys.
Case signals you cannot ignore
-
Evonik’s Leshan plant (announced operational ramp in 2026) demonstrates how targeted, high-purity additions can alter regional tightness and pricing in electronics supply chains—buyers and competitors must respond to preserve continuity.
-
Nouryon’s low-carbon product launch shows how sustainability-labelled chemistry can command differentiated positioning across end markets—marketing and verification will become commercial gating criteria.
-
Supply shocks in AO feedstock markets (including significant anthracene price moves in 2025 in certain regions) show that producers with feedstock flexibility or alternative technology pathways enjoy structural advantage in margin resilience.
How PW Consulting helps
Our advisory services translate the report’s insights into a tailored roadmap for your organization. Services include plant-level scenario modelling, procurement hedging frameworks, product positioning workshops, and M&A diligence on target assets. For firms with exposure to electronics, remediation, water treatment, or pulp & paper end-markets, we provide rapid 8–12 week engagement packages that convert market intelligence into executable 90-day plans.
Call to action
This release intentionally presents high-level strategic takeaways while withholding the granular segmentation and per-region / per-application breakdown that underpin our modelling—these are available exclusively in the full report. Executives who need the underlying data tables, plant maps, price curves, and customer-level scenarios for 2026 decision-making should consult the full PW Consulting Worldwide Specialty Oxidant Market report or contact our industry team for a briefing.
PW Consulting — turning market complexity into strategic advantage for 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Worldwide Specialty Oxidant Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts Worldwide Portable Automotive Wi-Fi Routers Market to Top USD 1,556.3 Million by 2032
By pmarketresearch, 2026-07-17
Worldwide Portable Automotive Wi‑Fi Routers Market: PW Consulting Issues Strategic Briefing for 2026 Decision‑Makers
Executive summary
PW Consulting today publishes a strategic briefing drawn from our full market research report on the Worldwide Portable Automotive Wi‑Fi Routers market (base year 2025, historical review 2020–2025, forecast 2026–2032). The market has expanded rapidly from the low‑hundreds of millions in 2020 to an estimated USD 824.5 million in 2025, and is forecast to accelerate through the coming decade to surpass USD 1.5 billion by 2032. This trajectory corresponds to a compound annual growth rate of 9.51% over the 2026–2032 forecast window, reflecting robust demand from fleet telematics, passenger connectivity, mobile business models and the broader vehicle connectivity upgrade cycle.
Worldwide Portable Automotive Wi-Fi Routers Market
This briefing is designed as a “trailer” — to demonstrate the report’s analytical depth, practical frameworks and strategic utility for 2026 decision cycles — while deliberately withholding the core proprietary segmentation tables to drive readers to the full dossier for transaction‑grade intelligence.
Worldwide Portable Automotive Wi-Fi Routers Market
Why this report matters for 2026 corporate strategy
- Procurement & supplier selection: Source strategies must balance performance (5G NR, Wi‑Fi 6), ruggedization, and geopolitical risk. Our frameworks allow procurement teams to shortlist partners for trials without needing to comb through raw market share tables.
- Regulatory compliance & supply‑chain resilience: Emerging export controls and communications rules require rapid remediation and contractual safeguards. The report translates regulatory trajectories into operational checklists for product sourcing and warranty terms.
- Technology roadmap & product positioning: OEMs and tier‑1 suppliers need to align product roadmaps to multi‑network architectures (4G/5G, C‑V2X coexistence, Wi‑Fi versions) and in‑vehicle systems. We show the practical timing and staging strategies for feature rollouts.
- Commercial models & pricing: From subscription bundling to hardware‑as‑a‑service models, the brief includes pricing templates and TCO calculators to model three distinct go‑to‑market options.
- M&A and partnership screening: For strategic buyers, the report supplies screening criteria and a prioritized watchlist to identify acquisition or alliance targets consistent with scale and technology fit.
Key market dynamics and strategic implications
- Growth drivers: The dominant growth vectors are fleet modernization, passenger experience upgrades in transit and hospitality, embedded telematics for insurance and safety, and the proliferation of mobile commerce. These demand drivers are fueling device refresh cycles and after‑sales services that increase lifetime value and recurring revenue opportunities.
- Technology transition: The move from LTE‑centric designs to multi‑mode 5G NR routers and Wi‑Fi 6/6E capable access points is accelerating. Importantly, interoperability with vehicle networks (automotive Ethernet, GNSS, CAN/OBD interfaces) and edge compute platforms defines winners in enterprise deployments.
- Regulatory inflection points: Three recent policy moves materially shape risk and go‑to‑market timing. First, export control actions targeting certain Vehicle Connectivity System hardware/software require buyers and OEMs to validate vendor provenance and implement contractual warranties. Second, spectrum and V2X technical decisions (such as the finalized parameters for C‑V2X in the 5.9 GHz band) create clear testing and coexistence requirements for in‑vehicle Wi‑Fi. Third, jurisdictional telecom classifications for in‑car connectivity services (notably in parts of the EU) impose operator obligations that may change commercial terms and compliance costs. Our report converts each regulatory development into a practical set of mitigations and procurement clauses.
- Channel and product bifurcation: The market maintains a dual character: enterprise/ruggedized vehicle routers for fleets, transit and emergency services, and ultra‑portable consumer hotspots adapted for in‑car use. Each segment requires distinct certification, lifecycle management and support economics; mixing strategies without clear cost allocation is a common commercial mistake.
- Fragmentation & consolidation dynamics: Competitive intensity is concentrated among a mix of specialist industrial vendors, large network equipment manufacturers and consumer brands. The market is neither a commodity market nor a wholly fragmented niche — this makes precise partner selection and contractual SLAs critical for enterprise buyers.
Competitive landscape — what buyers need to know
- Sierra Wireless (Semtech): A leader in rugged vehicle routers and Vehicle Area Network (VAN) solutions. Their AirLink Pro series exemplifies designs engineered for extreme temperature, vibration and vehicular power environments while offering passenger Wi‑Fi capability.
- Cradlepoint (Ericsson): Focuses on purpose‑built 4G/5G mobile routers for vehicle deployments with integrated enterprise management and security features; recently promoted enhanced 5G/LTE vehicle routers emphasizing zero‑trust controls for transit fleets.
- Teltonika Networks: Provides compact, cost‑efficient 5G vehicle routers targeted at mobile businesses and fleet operators; recent deployments demonstrate effective integration with vehicle Ethernet infrastructure.
- NetModule (Belden), Perle Systems: Offer modular, automotive‑grade platforms geared to complex vehicle systems and regulatory compliance needs, positioning them well for public safety, transit and autonomous vehicle pilots.
- Huawei, ZTE, NETGEAR, TP‑Link, GL.iNet, GlocalMe and select OEM specialists: Span consumer to enterprise offerings, supplying hot‑spot style devices, portable routers and integrated OEM modules — valuable for channel reach but requiring specific procurement controls when serving regulated fleets or government buyers.
- Strategic insight: The competitive field divides into vendors optimized for rugged enterprise deployments and manufacturers focused on portable consumer experiences. Procurement teams should explicitly rate vendors on ruggedization, managed services, security posture, supply‑chain provenance and regulatory exposure rather than only unit price.
Recent developments to factor into 2026 plans
- Regulatory: The U.S. Bureau of Industry and Security implemented rules affecting Vehicle Connectivity System transactions — immediate supplier due diligence and contractual indemnities are now table stakes for government and commercial fleet deals.
- Standards: Regulatory finalization of C‑V2X technical parameters necessitates coexistence testing and roadmap alignment for vendors claiming vehicle communications capability.
- Commercial: Leading vendors have ramped promotions and deployments of 5G‑enabled vehicle routers with Wi‑Fi 6 features and enhanced security, signalling that product maturity and market readiness have reached an inflection point for scaled trials.
Report contents — the practical toolkit inside
The full PW Consulting report is organized as a modular decision toolkit designed for executives, product leads, procurement officers and investors. Key deliverables include:
Worldwide Portable Automotive Wi-Fi Routers Market
- Market sizing and forecast methodology with base‑case, fast‑adoption and conservative scenarios for 2026–2032.
- Demand driver mapping and use‑case economics across fleet, transit, passenger, retail and microbusiness applications.
- Regulatory impact assessment and a jurisdictional readiness index that converts policy moves into deployment timelines and additional compliance costs.
- Vendor evaluation matrix and procurement scorecard with technical, commercial and supply‑chain risk dimensions (vendor heatmaps rather than raw share tables are presented in the briefing document).
- TCO and pricing models for CAPEX vs OPEX productization, including subscription packaging scenarios and churn sensitivity analysis.
- Integration playbooks for OEMs and system integrators covering software‑defined connectivity, edge compute, security hardening and field service models.
- M&A and partnership screening tools that identify strategic fit by technology stack, route‑to‑market and regulatory footprint.
- Contractual templates and RFP clauses aligned to export control, warranty, software‑supply, and zero‑trust security requirements.
How to use the briefing in practice
- For procurement leaders: use the vendor scorecard and supply‑chain risk matrix to establish a two‑tier supplier strategy (strategic vs tactical) and to define PoC acceptance criteria tied to vehicle‑level KPIs.
- For product teams: adopt the technology roadmaps and feature prioritization matrix to align firmware and hardware roadmaps with carrier modernization timetables and C‑V2X coexistence tests.
- For corporate development and investors: leverage the M&A screening and valuation sensitivity models to identify targets that deliver either vertical integration in the vehicle stack or complementary managed‑service capabilities.
- For compliance teams: implement the report’s regulatory checklists into contract approval workflows and vendor onboarding to reduce remediation costs and avoid supplier disqualifications mid‑project.
Next steps & call to action
PW Consulting’s full Worldwide Portable Automotive Wi‑Fi Routers Market report contains the proprietary segmentation tables, granular competitive benchmarking, and downloadable financial models omitted from this briefing. Access to the complete dossier and bespoke advisory engagements will be essential for teams that must finalize sourcing, product roadmaps or M&A activity in 2026.
For an executive briefing, custom vendor deep‑dive, or to license the full report and Excel modeling package, visit PW Consulting’s market reports page or contact our advisory desk to schedule a strategy workshop. Our analysts are available to convert the report’s insights into an actionable 90‑day implementation plan tailored to your organization’s priorities.
For detailed analysis of this topic, please visit the official page: Worldwide Portable Automotive Wi-Fi Routers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: Worldwide Rubber Bulbs Market to Rise from USD 478.0 Million in 2025 to USD 650.5 Million by 2032 at a 4.5% CAGR
By pmarketresearch, 2026-07-17
Worldwide Rubber Bulbs Market — Strategic Outlook for 2026
As PW Consulting’s Senior Strategic Advisor and Chief Industry Analyst, I present an executive preview of our newest market intelligence product: the Worldwide Rubber Bulbs Market report (base year 2025). This briefing highlights the report’s strategic value for corporate decision-makers preparing plans and capital allocations for 2026. It synthesizes our top-line market view, competitive implications, and prioritized actions—while preserving detailed segment and regional tables for subscribers who obtain the full report.
Worldwide Rubber Bulbs Market
Top-line market context
Our independent sizing places the global rubber bulbs market at approximately USD 478.0 Million in 2025. Under our base-case outlook, the market is expected to expand at a compound annual growth rate (CAGR) of 4.5% over 2026–2032, with revenues approaching the mid‑six‑hundreds by the end of the forecast horizon. The industry remains moderately consolidated: the three largest suppliers account for roughly a third of market revenue, while the top five reach just under half—dynamics that shape pricing power, innovation investment and M&A opportunity.
Worldwide Rubber Bulbs Market
Why this matters for 2026 corporate strategy
- Revenue planning under margin pressure: Growth is steady but not runaway. Companies must reconcile volume-driven topline opportunities with cost-side risks—most notably raw material volatility and regulatory-driven compliance costs.
- Supply chain and sourcing risk: Raw material developments in 2025–26—most visibly swings in natural rubber prices and export policy shifts in producing countries—require rapid rethinking of sourcing strategies and supplier contracts.
- Regulatory exposure: Upstream chemical risk evaluations and shifting emissions rules increase compliance complexity for manufacturers. This will influence capital allocation for emissions controls, product reformulation, and certification timelines.
- Consolidation and differentiation: Market concentration metrics indicate room for acquisitive growth for mid‑sized players and specialization strategies for niche suppliers focused on medical or engineered applications.
Recent industry signals that change the playbook
- Raw material cost shock: Natural rubber benchmark levels firmed into 2026; benchmark pricing reached 216.20 USD cents/kg on April 29, 2026—an increase of nearly 28% year‑on‑year—adding immediate cost pressure across rubber‑dependent products.
- Price volatility trends: While benchmark indexes showed downward pressure through much of 2025, market tightness and supply considerations produced a reversal into early 2026—creating a two‑speed cost environment by material source and grade.
- Regulatory momentum: The U.S. legislative and regulatory layer is active—actions in 2025 targeted emission standards for rubber tire manufacturing, while agencies are progressing risk evaluations for chemicals used in plastics and rubber processing. These developments presage increased compliance and disclosure requirements for manufacturers.
- Trade and policy risk: Policy moves in producing nations to curb raw exports to stimulate local processing add another dimension to sourcing risk and near‑term input costs.
What the full PW Consulting report delivers (practical focus)
The report goes beyond high‑level forecasts. It is configured as a working toolset for commercial, procurement, and corporate development teams seeking to convert market insight into action. Key deliverables include:
Worldwide Rubber Bulbs Market
- End‑to‑end market model—transparent, auditable forecasting logic and downloadable assumptions that allow CFOs to stress‑test revenue scenarios against commodity swings.
- Scenario and sensitivity modules—base, downside (supply shock) and upside (accelerated demand) cases, with embedded sensitivity to raw material prices and regulatory cost pass‑through.
- Supplier and competitor benchmarking—profiles, manufacturing footprints, product capabilities, and commercial positioning for the principal players, enabling rapid counterparty assessment for procurement and M&A screening.
- Commercial playbooks—go‑to‑market recommendations by channel (OEM, medical/lab, industrial, consumer) with SKU rationalization and pricing tactics to protect margins under rising input costs.
- Procurement playbook—negotiation levers, contract clauses for price adjustments, hedging guidance and alternative material sourcing roadmaps to reduce exposure to single‑source suppliers and export restrictions.
- Regulatory risk matrix—impact scoring, compliance timelines and capital planning guidance tied to current agency initiatives and plausible policy scenarios.
- M&A and partnership screening—actionable shortlist of target profiles (capacity, certification, geographic footprint) aligned to the concentration and growth dynamics of the sector.
Competitive landscape — practical takeaways
The market is populated by a mix of specialized medical suppliers, engineered rubber extruders, and diversified component manufacturers. Our competitive analysis synthesizes public‑domain company profiles, product capabilities and strategic intent to help buyers and investors prioritize interactions.
- Danyang Fuli Rubber & Plastic Products Co., Ltd. (Danyang, China) — A specialist in suction bulbs and related medical rubber products. Strengths: focused medical product line, cost-competitive manufacturing. Strategic consideration: attractive supplier for OEM partnerships in volume medical and laboratory categories; assess quality systems and sterilization capabilities for higher‑value medical contracts. (rubber-bulb.com)
- Elastostar Rubber Corporation (USA) — Known for engineered silicone extrusions and bulb‑shape gaskets for industrial sealing. Strengths: customization, material science capabilities. Strategic consideration: potential partner for industrial OEMs seeking advanced sealing solutions or for joint development of silicone‑dominant designs as a hedge against natural rubber volatility. (elastostar.com)
- Simolex (USA) — Produces FDA‑food‑grade and high‑quality silicone bulbs and extrusions. Strengths: regulatory-compliant material expertise. Strategic consideration: opportunities in medical/consumer applications where regulatory clearance and food‑grade material are differentiators. (simolex.com)
- Ebco, Inc. (Elgin, Illinois, USA) — Supplier of engineered bulb seals for OEMs with global distribution. Strengths: broad OEM relationships and distribution reach. Strategic consideration: bolt‑on acquisition target for firms seeking to accelerate entry into North American OEM channels. (ebcoinc.com)
- VIP Rubber and Plastic Co. (USA) — Custom extrusions and molded products, including bulb profiles. Strengths: manufacturing flexibility and quick turn prototyping. Strategic consideration: useful for companies needing rapid product iteration and short lead‑time runs. (viprubber.com)
- Jiangyin Haihua Rubber & Plastic Co., Ltd. (China) — Producer of medical bulbs and rubber stoppers. Strengths: product breadth in medical components. Strategic consideration: supply diversification candidate for buyers balancing cost and certification needs.
- Narang Medical / GPC Medical Limited (India) — Exporter of medical bulbs and syringes. Strengths: export experience and cost positioning. Strategic consideration: alternative sourcing option given shifting trade policies in producing countries, with attention to quality systems for regulated markets.
- BOENMED (China) — Focused on ear bulb syringes made from medical‑grade materials. Strengths: niche product expertise; potential partner for white‑label or private‑label programs. (boenmedical.com)
Strategic imperatives for 2026 (prioritized)
- Actively diversify raw material supply and hedge selectively: Implement dual‑sourcing and hedging strategies for key elastomers; evaluate strategic inventory buffers for critical SKUs.
- Accelerate material substitution R&D: Target silicone or engineered elastomers where performance and regulation permit as a defensive play against natural rubber price shocks.
- Embed regulatory planning into product roadmaps: Allocate capital for chemical risk assessments and certification to avoid disruption from emerging agency mandates.
- Use M&A to secure mid‑market scale: Target acquisitions that add certified capacity, shorten supply chains, or provide access to premium channels (medical/OEM).
- Negotiate smarter commercial terms: Incorporate cost‑pass‑through clauses, indexed pricing, and minimum purchase commitments to balance supplier and buyer risk.
- Invest in traceability and quality systems: Demonstrable product provenance and sterilization/quality credentials create premium pricing opportunities in medical and food‑grade segments.
How to deploy the report in 90 days
- Week 1–2: Review the downloadable forecast model and stress test your product portfolio under a +25% raw material price scenario.
- Week 3–6: Run supplier health checks and create a prioritized supplier diversification plan informed by our supplier heatmap.
- Week 7–10: Finalize a regulatory compliance gap analysis for core SKUs and build a capital roadmap for necessary mitigation.
- Week 11–12: Brief the executive committee and update the three‑year strategic plan with quantified scenarios from the report.
Next steps and access
PW Consulting’s Worldwide Rubber Bulbs Market report is designed as a working intelligence asset for procurement, product and corporate development teams. The full publication contains the detailed segmentation, regional and end‑use breakdowns, and an interactive model that shows line‑by‑line revenue and margin impacts—information we intentionally reserve for report subscribers to preserve commercial value. For purchasing information, licensing queries or to arrange a tailored brief for your leadership team, please contact PW Consulting via our website.
In short: 2026 will be defined by tactical management of input cost pressure, proactive regulatory compliance, and selective consolidation or partnership moves. Entities that execute on the prioritized imperatives above will be best positioned to capture the steady market expansion our model predicts while protecting margins and operational continuity.
For detailed analysis of this topic, please visit the official page: Worldwide Rubber Bulbs Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Aircraft GSE & MRO Market to Expand from USD 120.5 Billion in 2025 to USD 175.29 Billion by 2032 at a 5.48% CAGR, Driven by USD 104.4B in MRO Services
By pmarketresearch, 2026-07-17
Worldwide Aircraft Ground Support Equipment (GSE) and MRO Market — Strategic Preview for 2026 Decision-Makers
Executive summary
PW Consulting’s newest market study, Worldwide Aircraft Ground Support Equipment (GSE) and MRO Market, synthesizes five years of historical behavior and seven years of forward-looking scenario analysis to equip executives with the actionable intelligence needed to make high-consequence decisions in 2026. The global market reached a pivotal scale in our base year (2025) and — under the central scenario modeled in the report — is projected to expand at a compound annual growth rate of 5.48% through the 2026–2032 forecast horizon, reaching materially higher total size by 2032. This trajectory reflects a combination of fleet recoveries, accelerated electrification rollouts, rising aftermarket demand and shifting commercial models such as rental and lifecycle services.
Worldwide Aircraft Ground Support Equipment (GSE) and MRO Market
Why 2026 is an inflection year
-
Capital cycles reset. Many airport operators, airlines and ground handlers are concluding multiyear maintenance and asset renewal programs initiated after the pandemic; 2026 is the year when incremental investments yield measurable operational and sustainability returns.
Worldwide Aircraft Ground Support Equipment (GSE) and MRO Market -
Electrification and infrastructure converge. Adoption of electric and hybrid GSE has moved from pilot to scale in pockets. Our study highlights that electrification is no longer a niche capex item — it requires coordinated power system planning, new procurement specifications and revised maintenance regimes.
Worldwide Aircraft Ground Support Equipment (GSE) and MRO Market -
Regulatory clarity is sharpening. International guidance bodies and regional regulators are converging on recommended practices for enhanced GSE safety, emissions reporting and autonomous operations. Decisions made in 2026 will lock in compliance pathways for the next decade.
Core market signals executives cannot ignore
-
Scale and growth: The market’s overall trajectory from the historical baseline through the forecast period demonstrates consistent expansion, creating both volume-led opportunities for OEMs and aftermarket growth for MRO providers.
-
Fragmentation with dominant niches: Market share is distributed — a meaningful proportion of demand is serviced by a broad base of specialized players even as a small number of global platform vendors capture a material share. This creates a two-track competitive landscape where scale advantages coexist with niche differentiation opportunities.
-
Energy and charging constraints are real: Large hub airports deploying electrified GSE may face peak power demands and annual electricity loads that require grid upgrades and sophisticated demand-management solutions. Our research cites operational examples where peak loading and megawatt-class planning became critical project drivers.
-
Technology bottlenecks persist on batteries and autonomy: Battery systems must satisfy safety, cycle-life and cold-weather performance requirements before full-scale replacement of legacy fossil-fueled fleets becomes universal. Similarly, autonomous/connected GSE is advancing rapidly, but interdependence with ATM, gate systems and ground safety regimes requires staged adoption.
Five strategic imperatives for 2026 planning
-
Plan energy infrastructure concurrently with fleet procurement. Treat charging and energy management as long-lead assets. Our electrification readiness modules show that failure to align procurement with site-level power capacity can add months and significant cost overruns to rollouts.
-
Shift from unit economics to lifecycle economics. The most value-accretive programs are those that couple acquisition decisions with MRO strategies, parts provisioning and telematics-driven predictive maintenance. Rental and managed-fleet models are reshaping working capital requirements for airlines and handlers.
-
Adopt a modular roadmap for autonomy. Begin with safety-enhancing driver-assist systems and telematics, then sequence higher autonomy modules. This minimizes operational disruption and aligns with evolving IATA recommended practices for testing and phased implementation.
-
Build supplier ecosystems, not just supplier lists. The shift to electric and automated GSE increases dependence on battery suppliers, power electronics integrators and local service partners. Strategic partnerships and captive rental/fl eet-management arrangements will be differentiators.
-
Embed regulatory modelling into procurement spec development. Regional programs — for example, state-level clean aviation initiatives and industry-wide safety recommendations — mean that procurement specs must be future-proofed against likely compliance requirements.
What the PW Consulting report delivers to executives
Our market study is designed as an operational toolkit for 2026 decision cycles, not merely a descriptive forecast. Key deliverables include:
-
Actionable scenario forecasts — base, upside and downside pathways with sensitivity levers tied to fleet utilization, electricity pricing and policy shocks.
-
CapEx and TCO models — configurable templates that compare diesel, hybrid and electric fleet economics under different duty cycles and energy price scenarios.
-
Electrification readiness assessments — checklist and sizing methodology for charging infrastructure and local grid upgrades, including demand-management options and on-site storage trade-offs.
-
MRO and aftermarket blueprints — staffing, parts stocking, depot design and predictive-maintenance playbooks tailored to different scale profiles.
-
Vendor benchmarking and procurement scorecards — a structured way to evaluate OEMs and service providers on performance, warranty/socialized risk, and retrofit pathways.
-
Regulatory mapping — alignment matrices that translate IATA guidance, regional programs and known survey initiatives into procurement and implementation checkpoints.
Competitive landscape — tactical takeaways
The competitive field combines global platform OEMs, specialized niche suppliers and diversified MRO giants. Several archetypes emerge:
-
Platform OEMs expanding electrified portfolios (e.g., manufacturers with towbarless tractors, loaders and bridge systems) — these players are pursuing integrated gate and ramp automation to capture higher-value systems work and recurring service revenue.
-
Component specialists and electrification enablers — firms focusing on GPUs, battery systems and charging/safety technologies are becoming critical partners to OEMs and operators as electrification accelerates.
-
MRO and lifecycle specialists — large MRO groups and aftermarket distributors are scaling capabilities to support fleet electrification, offering managed-services and retrofit programs that reduce operator risk.
Notable market movements highlighted in the study reinforce these archetypes: recent demonstrations of integrated gate and ramp automation, strategic partnerships to deploy electric GSE at scale in new geographies, new lithium-ion battery system introductions into the supply chain, and commercial rollouts of high-volume deicing and glycol transfer systems that materially affect turnaround operations and MRO planning.
Regulatory and technology items to model in 2026
-
IATA guidance on enhanced GSE and autonomous testing is maturing — incorporate recommended practices early to avoid retrofitting costs and to streamline certification paths.
-
Regional clean-air initiatives and survey programs will increasingly inform procurement eligibility and potential incentives; model these into investment cases for early movers.
-
Battery and safety constraints remain a gating factor for full electrification; expect incremental investments in battery management, weatherization, and depot fire-safety mitigations.
-
Energy systems planning is non-trivial at major hubs — peak load and annual energy consumption figures from exemplar airports demonstrate the scale of coordination required between airports, utilities and operators.
How 2026 executives should use this research
Procurement leaders, airport planners, finance chiefs and MRO heads should use the report to:
-
Rebase CapEx timelines using the report’s scenario outputs to align with funding cycles and sustainability targets.
-
Structure pilot programs around the report’s modular autonomy and electrification playbooks to de-risk scale-up.
-
Negotiate supplier agreements using our vendor scorecards and warranty-risk frameworks to preserve optionality for technology changes.
-
Create cross-functional implementation teams (energy, MRO, operations, procurement) using the report’s depot-design and charging-checklist templates to reduce integration friction.
Next steps
This preview is designed to demonstrate the practical depth and strategic orientation of PW Consulting’s analysis while preserving the full granularity and proprietary segment-level intelligence that support high-confidence decisions. For boards, investment committees and operational leaders embarking on GSE and MRO programs in 2026, the full study provides the underlying datasets, customizable financial models and procurement collateral necessary to move from strategy to execution.
Contact PW Consulting to obtain the complete Worldwide Aircraft Ground Support Equipment (GSE) and MRO Market report, access our scenario workbooks and schedule a briefing tailored to your organization’s 2026 decision calendar.
For detailed analysis of this topic, please visit the official page: Worldwide Aircraft Ground Support Equipment (GSE) and MRO Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide THRAP3 Antibody Market to Rise at 5.24% CAGR to USD 20.74 Million by 2032 — North America Leads with USD 5.59M (2025)
By pmarketresearch, 2026-07-17
Worldwide THRAP3 Antibody Market — Strategic Outlook for 2026 Decision-Makers
Executive synopsis
PW Consulting’s newest market intelligence brief on the Worldwide THRAP3 Antibody Market synthesizes proprietary modeling, primary interviews, and vendor-level validation audits to translate biochemical niche trends into boardroom-grade decision levers for 2026. The market has demonstrated steady expansion from an estimated USD 11.23 Million in 2020 to USD 14.50 Million in 2025 (base year). Our forecast model, built for scenario planning across 2026–2032, projects a compound annual growth rate (CAGR) of 5.24% and anticipates the overall market approaching roughly USD 20.74 Million by 2032. These macro trajectories create a pragmatic window for commercialization, portfolio rationalization, and targeted R&D investment for firms engaged in research reagents, antibody production, and reagent distribution.
Worldwide THRAP3 Antibody Market
Why this matters for 2026 strategy
-
Signal clarity: The THRAP3 antibody market is mature yet undersupplied in certain performance niches (e.g., application-specific validated reagents). A measurable, mid-single-digit CAGR positions the segment as a predictable adjunct to core biochemical reagents portfolios, attractive for bolt-on M&A and product line extensions.
Worldwide THRAP3 Antibody Market -
Capital allocation: Moderate, reliable growth supports staged investment—pilot-scale expansions and targeted validation campaigns in lieu of heavy-scale capacity builds.
Worldwide THRAP3 Antibody Market -
Commercial focus: The optimal 2026 commercial playbook emphasizes application-validated claims, streamlined regulatory positioning as research-use-only (RUO), and value-added services (custom conjugation, validated controls, lot-to-lot consistency guarantees).
Market dynamics and demand drivers
Demand for THRAP3 antibodies is driven by a steady research pipeline around transcriptional regulation and RNA-binding protein biology, coupled with broader investment in proteomics and cell biology toolkits. Academic funding cycles, translational research collaborations, and method adoption (e.g., immunohistochemistry and imaging workflows) create recurring demand patterns that are less volatile than early-stage therapeutic reagent segments.
Regulatory context is straightforward but consequential: leading vendors explicitly designate THRAP3 antibodies as research use only (RUO), not for diagnostic or therapeutic applications. This designation shapes go-to-market restrictions, claims, quality systems expectations, and the nature of commercial partnerships (e.g., distributors vs. clinical suppliers).
Supply-side realities and operational risk
-
Supplier differentiation is product-validation centric. Vendors that couple robust validation data (WB, IHC, IF, IP) with transparent antibody provenance and orthogonal evidence enjoy premium positioning among high-throughput labs and CROs.
-
Production constraints are manageable for most manufacturers, but reputational risk from antibody specificity failures is material. Rigorous internal QC, third-party validation, and open reproducibility data are non-negotiable elements for scale.
-
Distribution and inventory strategies must balance batch-level traceability with fast-turnaround service for academic customers—who continue to expect small-quantity, high-quality reagents.
Competitive landscape — capabilities, not shares
PW Consulting’s competitive mapping emphasizes competency clusters rather than raw market share, helping executives identify white-space and defensive priorities without disclosing granular segment splits.
-
Abcam (Cambridge, UK) — strengths: broad validation portfolio with multi-application support (e.g., western blot, IHC, ICC/IF); strong brand recognition and digital product presentation that supports reproducibility claims.
-
Santa Cruz Biotechnology (Dallas, TX, USA) — strengths: monoclonal offerings with emphasis on immunoprecipitation and imaging applications; legacy distribution channels in North American academic markets.
-
Proteintech Group (Rosemont, IL, USA) — strengths: deep polyclonal catalog and emphasis on lab-validated performance in WB, IHC and IP workflows; competitive supply resilience and customer service orientation.
-
Boster Biological Technology (Pleasanton, CA, USA) — strengths: monoclonal reagents targeted for WB and IHC; agile production capabilities and competitive lead times.
-
GeneTex (Irvine, CA, USA), Novus Biologicals (Centennial, CO, USA), OriGene Technologies (Rockville, MD, USA), and Sigma-Aldrich/Atlas Antibodies (St. Louis, MO, USA) — collectively represent breadth in polyclonal and rabbit-validated antibodies and established distribution footprints. Their product-validation claims and catalogue depth make them natural partners or benchmarks for entrant strategies.
Across the vendor set, differentiation is driven by validation depth (application coverage), supply reliability, data transparency and technical support. PW Consulting’s vendor scorecards quantify each of these dimensions to inform procurement, alliance, and acquisition targets.
What the PW Consulting report delivers — practical, actionable outputs
-
Forward-looking financial model (2026–2032) in editable Excel, enabling sensitivity analysis across adoption, price erosion, and validation success scenarios.
-
Demand-driver heatmaps and scenario-led forecasts that translate bench-level workflows into procurement volumes for research organizations and CROs.
-
Vendor benchmarking and supplier scorecards built on multi-criteria assessments (validation breadth, production resilience, digital data transparency, pricing posture, and go-to-market reach).
-
Go-to-market playbooks with tactical recommendations for entry, growth, and defense—covering channel mix (direct vs. distributor), pricing architecture, and sample/validation strategies.
-
Regulatory & claims primer focused on RUO designation implications, labeling best practices, and contract-language templates to reduce downstream compliance friction.
-
Operational risk map covering supply-chain bottlenecks, reagent quality failure modes, and mitigation playbooks (backup suppliers, multi-site validation, and batch-release criteria).
Strategic implications and recommended actions for 2026
For executives allocating capital and commercial attention in 2026, PW Consulting highlights four prioritized moves:
-
Prioritize validation-led product upgrades. Invest in orthogonal validation data (e.g., siRNA knockdown confirmation, orthogonal proteomics) and publicize raw datasets to reduce buyer uncertainty and enable premium pricing.
-
Execute targeted partnerships rather than broad capacity expansions. Co-development agreements with imaging-platform vendors, or exclusive content deals with key academic centers, yield disproportionate access to demand corridors.
-
Adopt a modular pricing and sample strategy. Offer low-cost exploratory sample sizes with paid, high-confidence vials backed by extended tech support and reproducibility guarantees to accelerate adoption in translational labs.
-
Use M&A selectively to acquire validation capabilities or digital assay-data assets. Acquiring validation-rich product lines or data repositories can compress time-to-premium positioning without broad production CAPEX.
How to use the report in boardroom decision cycles
We designed the report to slot directly into quarterly strategy reviews, M&A diligence, and commercial planning. Typical use cases include:
-
Commercial leaders: refine product roadmaps and prioritize validation investments where margin uplift is most likely.
-
M&A teams: screen targets using PW Consulting’s vendor scorecards and financial model to isolate acquisition candidates that accelerate market entry or close capability gaps.
-
Supply chain and operations: stress-test inventory and dual-sourcing plans against scenario outputs to ensure research continuity for key accounts.
Methodology and quality assurance
The PW Consulting forecast combines proprietary shipment and pricing datasets with a bottom-up synthesis of published vendor validations, distributor shipment trends and expert interviews across academic and commercial laboratories. We triangulated results with vendor disclosures and adjusted for RUO-specific market constraints. In keeping with our “trailer” principle, the public summary emphasizes strategic takeaways; the full report includes the underlying models, granular subsegment meshes and vendor-level tables.
Closing perspective
In 2026, the THRAP3 antibody market will reward organizations that move beyond catalog breadth to demonstrate reproducibility, application-specific utility and predictable supply. The segment’s mid-single-digit CAGR and stable demand base create room for focused investments—especially those that reduce buyer uncertainty and convert validation into a defensible commercial proposition. PW Consulting’s Worldwide THRAP3 Antibody Market report arms decision-makers with the models, vendor intelligence and action plans required to convert these market dynamics into measurable revenue and competitive advantage.
Next steps
For companies evaluating entry, expansion or acquisition in the THRAP3 antibody space, PW Consulting’s full report and accompanying Excel model provide the missing subsegment detail, vendor-by-vendor benchmarking and downloadable datasets necessary for execution. Visit PW Consulting’s report page to access the full dataset, scenario models, and proprietary vendor scorecards.
For detailed analysis of this topic, please visit the official page: Worldwide THRAP3 Antibody Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com