

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Graphene Chip Market to Expand at 24.5% CAGR — From USD 215 Million in 2025 to Nearly USD 1 Billion by 2032, Led by Asia Pacific (USD 84.3M)

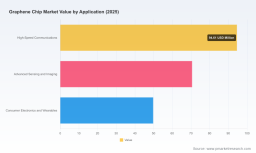
Graphene Chip Market: Strategic Imperatives for 2026 — PW Consulting Market Brief
Executive summary
PW Consulting’s newly released Graphene Chip Market report (base year 2025) frames graphene-enabled electronics as a rapidly scaling sub-market within the broader semiconductor and photonics ecosystem. After a six-year historical review (2020–2025), our baseline shows the market expanding from the low double-digit millions in 2020 to USD 215.0 Million (revenue unit: Million) in 2025. Under our central scenario, the market is forecast to grow at a 24.5% compound annual growth rate (CAGR) through a 2026–2032 forecast window, reaching just under USD 1.0 Billion (USD 996.85 Million) by 2032. The 2026 projection in the report — an early inflection point for commercial deployments — is USD 275.56 Million.
Graphene Chip Market
This press briefing presents the strategic takeaways that senior executives, technology investors, and corporate development teams should prioritize in 2026. In line with our “preview trailer” approach, we intentionally withhold granular regional and application-level splits from this summary to help readers assess strategic fit and then visit the full report for proprietary segmentation tables, unit economics, and vendor scorecards.
Graphene Chip Market
Why 2026 is a strategic inflection point
-
Maturing pilot lines and product launches. 2025–2026 activity shows conversion from lab demonstrations to pilot manufacturing and early commercial SKUs. Notable industry moves include wafer-scale production milestones and product introductions that shift graphene from specialty material to a component that can be designed into systems.
Graphene Chip Market -
Convergence of electronic and photonic integration. Developments in graphene photonics and interconnects point to differentiated value in high-speed communications, advanced sensing, and thermal management where traditional silicon approaches face scaling limits.
-
Policy and supply-chain reshaping. New export-control regimes and ongoing consolidation in foundry and equipment supply chains are changing the calculus for where to site capacity, which partners to engage, and how to manage inventory of critical materials and process tools.
Report contents — actionable modules
The full PW Consulting report is structured for decision makers who need executable insights, not just market forecasts. Key practical modules include:
-
Market-sizing and adoption scenarios: three forward-looking commercialization tracks (conservative, central, accelerated) with topline and unit forecasts by technology readiness level.
-
Technology readiness and integration playbooks: evaluation of GFETs, graphene interconnects, and thermal management architectures, including process roadmaps and recommended pilot-scale validation steps.
-
Manufacturing and cost-modeling toolkit: bottom-up cost curves for wafer-scale processing, foundry partnerships, and packaging pathways, plus sensitivity analysis for throughput and yield.
-
Supply-chain heatmap: critical equipment and raw-material dependency mapping, supplier risk scoring, and mitigation levers for constrained inputs.
-
Go-to-market and partner selection: OEM integration pathways, licensing templates, and partner-evaluation matrices to inform strategic alliances or M&A screening.
-
Regulatory and export-control playbook: jurisdictional implications, compliance checklists, and contingency plans for cross-border manufacturing and technology transfers.
-
Vendor and IP landscape: qualitative vendor benchmarking, patent-clustering insights, and a shortlist of strategic targets with supporting rationale.
Competitive landscape: what the leading players signal
The competitive field is still emerging, with a small set of specialist vendors progressing from materials and foundry services to device-level and system-level offerings. Our competitive analysis focuses on firms showing tangible manufacturing and commercialization milestones and identifies near-term strategic actions for incumbents and entrants.
-
Paragraf (Huntingdon, UK) — Paragraf’s commercial shift to silicon-wafer GFET processing and a recent product launch underscore a move toward mainstream semiconductor form factors. Their direct deposition approach and foundry-like service offering position them as a bridge between research platforms and volume-oriented supply. Strategic implication: system integrators should treat Paragraf as a candidate partner for early design-ins and as a supplier for pilot runs where contamination control and wafer compatibility are critical.
-
Graphenea (San Sebastian, Spain; US operations) — As a dedicated graphene foundry, Graphenea’s capabilities in CVD films and custom GFETs make them a natural partner for sensor OEMs and companies seeking repeatable material performance. Strategic implication: procurement teams will benefit from engaging Graphenea early to lock down film-specifications and co-develop reliability testing protocols.
-
Black Semiconductor (Aachen, Germany) — Focused on integrated graphene photonics and interconnects, Black Semiconductor’s progression toward a 300mm pilot line and automation partnerships signals ambition to serve hyperscale and telecom markets. Strategic implication: network and data-center OEMs should monitor their pilot outputs closely and consider joint validation programs around high-density interconnect performance.
-
Archer Materials (Sydney, Australia) — Working at the interface of quantum processors and biochips, Archer’s work demonstrates graphene’s cross-domain applicability. Strategic implication: R&D organizations in quantum and medical diagnostics should explore collaboration models that de-risk early-stage device integration.
-
Vorbeck Materials (Jessup, Maryland, USA) — With strength in conductive inks and composite components, Vorbeck is important for printed-electronics and hybrid integration use cases. Strategic implication: consumer-electronics OEMs and printed-sensor manufacturers should include Vorbeck in their supplier shortlist for form-factor-sensitive applications.
Our vendor analysis in the report also quantifies market concentration and competitive dynamics: the three largest players capture a meaningful—but not dominant—share of market value, while the top five represent a majority presence. This concentration profile suggests opportunities for both specialist suppliers and new entrants that can demonstrate superior integration economics or IP position.
Industry context and recent developments
-
Manufacturing milestones and product introductions in 2025–2026 are accelerating commercialization timelines. Examples include wafer-scale GFET production and pilot-line automation partnerships that tighten the link between materials science and fab-scale processes.
-
Regulatory shifts, including updated export-control lists, are increasing complexity for cross-border equipment and kit transfers. Corporates must embed compliance scenarios into their location and sourcing decisions.
-
Raw-material economics are improving: industrial-grade graphene nanoplatelets continue to decline in price as scaling occurs, which compresses component cost and supports broader end-market adoption.
-
Public-private consortia and multi-project wafer runs are actively lowering integration risk through shared pilot capacity and standards workstreams.
Strategic playbook for 2026 decision-makers
For executives making spend and partnership decisions this year, the following prioritized actions are derived from our scenario and sensitivity work:
-
Immediate (0–12 months) : Conduct disciplined pilot-vendor selection with contingency clauses; secure supply options for critical materials; initiate targeted IP and freedom-to-operate diligence for any planned integrations.
-
Near-term (12–24 months) : Co-fund pilot production runs with a selected foundry partner; standardize validation protocols across electrical, thermal, and reliability metrics; lock initial purchase agreements to hedge pricing and delivery risk.
-
Mid-term (24–60 months) : Decide on capacity strategy—build vs. partner—based on pilot yield roll-outs and TCO analyses; scale up integration efforts for products showing clear value capture; pursue M&A or joint-venture structures for securing proprietary process steps or unique materials.
Risk matrix — what to watch
-
Regulatory risk : Tightening export controls can affect equipment availability and cross-border transfer of process knowledge.
-
Supply-chain risk : Single-sourced process tools and specialty substrates remain a bottleneck in some manufacturing paths.
-
Technical integration risk : Yield and lifecycle reliability remain the primary technical gating items for system-level adoption.
-
Market adoption risk : End users will require demonstrable system-level ROI (throughput, energy, or form-factor) before switching from incumbent technologies.
How clients should use this report in 2026
Companies should treat the PW Consulting Graphene Chip Market report as a decision-support asset rather than a static forecast. Use it to:
-
Underpin capex and R&D budget allocations with scenario-ready financials and sensitivity analyses;
-
Prioritize pilot programs and vendor engagement based on quantified value-at-stake and integration complexity;
-
Frame M&A and partnership theses with vendor scorecards and IP-cluster mapping included in the full report;
-
Inform procurement and legal teams with a regulatory playbook tailored to cross-border supply and export control dynamics.
Next steps and how to obtain the full intelligence
This briefing deliberately outlines the strategic contours and operational levers that matter for 2026 while withholding the granular segmentation matrices, regional and application-level splits, and proprietary vendor scoring that are delivered in the complete report. PW Consulting clients and subscribers can access the full dataset, scenario toolkits, and tailored advisory workshops via our website and client portal.
For executives seeking a bespoke briefing—scenario workshops, workshop-facilitated vendor selection, or a bespoke due-diligence pack for potential investments—PW Consulting offers tailored advisory engagements to translate these market signals into executable programs.
Closing
Graphene-enabled chips have moved decisively from laboratory promise to early commercial reality. For companies that align product roadmaps, manufacturing intents, and regulatory strategies now, 2026 will be the year to secure optionality and competitive advantage as the market scales toward the billion-dollar horizon outlined in our forecast. PW Consulting’s full report provides the granular analytics and playbooks required to operationalize this insight.
For detailed analysis of this topic, please visit the official page: Graphene Chip Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com