

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
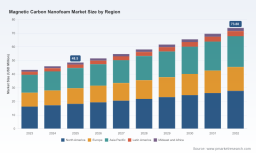
PW Consulting: Global Magnetic Carbon Nanofoam Market to Reach USD 73.88 Million by 2032, Growing at 6.22% CAGR (2026–2032) — North America Leads with USD 18.2M

Worldwide Magnetic Carbon Nanofoam Market — Strategic Preview for 2026 Decision-Makers
As magnetic carbon nanofoam moves from laboratory curiosity toward early commercial deployments, strategic clarity will determine which organizations capture disproportionate value in the coming decade. PW Consulting’s new Worldwide Magnetic Carbon Nanofoam Market study (base year 2025; historical 2020–2025; forecast 2026–2032) synthesizes proprietary modeling, primary interviews and supply-chain validation to deliver a decision-grade intelligence package for 2026. This preview highlights the report’s most consequential, board-level takeaways while intentionally holding back granular segment-level tables and company-specific data to encourage direct access to the full study.
Worldwide Magnetic Carbon Nanofoam Market
Key macro takeaways you need now
-
Market scale and trajectory: The global magnetic carbon nanofoam market reached approximately USD 48.5 Million (USD Million unit, base year 2025) and is projected to expand to about USD 73.9 Million by 2032. Our base-case implies a compound annual growth rate of roughly 6.22% through the forecast horizon, reflecting steady commercialization across a set of high-value applications.
Worldwide Magnetic Carbon Nanofoam Market -
Recent momentum: After a measured build from 2020 to 2024, the market accelerated into 2025, with continued expansion expected in 2026 as pilot projects convert to low-volume production runs and early adopters refine integration pathways.
Worldwide Magnetic Carbon Nanofoam Market -
Concentration and competitive structure: Market concentration is moderate — the top three players account for roughly 38.4% of the market and the top five for around 52.1% — which signals both existing incumbent strength and meaningful room for new entrants that can differentiate on performance, cost or supply reliability.
Why 2026 is a strategic inflection point
2026 represents the first full year when several parallel vectors converge: cost reductions from scale-up, clearer regulatory pathways for advanced carbon materials, and growing industrial demand for compact, high-performance electromagnetic and catalytic solutions. For corporate decision-makers, this creates a narrow window to translate lab-level IP into defensible product platforms, secure supply relationships, and shape standards that will influence adoption economics for the rest of the decade.
What the report delivers — practical, executable intelligence
The PW Consulting report is structured as an action toolkit rather than a purely academic forecast. Key deliverables included in the full study are:
-
Validated market sizing and scenario forecasts (2026–2032), with sensitivity analyses for pricing, adoption rates and feedstock cost volatility.
-
Segment-level demand drivers and adoption roadmaps by application class, with quantified upside and downside scenarios (note: detailed segment tables are available in the full report).
-
Manufacturing and scale-up playbook — from pilot-line designs to capital intensity benchmarks and recommended process yields to reach target cost points.
-
Supply-chain heat map including critical inputs, choke points, and mitigation strategies (dual sourcing, backward integration, tolling partnerships).
-
Commercialization routes and go-to-market options: licensing vs. JV vs. captive production, with decision criteria tied to company capabilities and balance-sheet appetite.
-
Regulatory and sustainability checkpoints: lifecycle considerations, likely testing requirements, and reputational risk management steps needed before broad deployment.
-
Investment and M&A thesis: criteria for target screening, valuation sensitivities, and integration risks to watch during diligence.
-
Customer archetypes and procurement triggers: what end-users prioritize (performance, cost, reliability), and how procurement cycles vary across industries.
Competitive landscape — interpretation and implications
With a CR3 of ~38% and CR5 of ~52%, the market is neither a pure oligopoly nor highly fragmented. This structure produces three strategic implications for 2026:
-
Incumbent leverage exists: established players retain advantages in manufacturing know-how, quality control and pilot-to-scale transitions. For buyers, this means predictable supply but also potential price premiums.
-
Opportunity for challengers: differentiated performance (e.g., higher magnetic responsiveness, tailored microstructure for specific EM shielding profiles), lower total cost of ownership, or proprietary integration services can overcome incumbent advantages.
-
M&A and partnerships will matter: given the concentration levels, strategic acquisitions and JV models are the fastest path for mid-sized firms to acquire capability and market access without the time and capex burden of full greenfield scale-up.
Dominant market dynamics shaping value pools
Several cross-cutting trends determine who wins and who loses as the market grows:
-
Application-driven adoption: Demand originates from high-value applications where magnetic carbon nanofoam's combination of low density, tunable magnetic properties and surface area deliver distinctive performance advantages — particularly in electromagnetic interference shielding, environmental remediation catalysts and certain sensing functions. Timing and scale of demand differ across applications, which requires targeted commercial strategies rather than a one-size-fits-all approach.
-
Cost-to-performance curve: Early-stage production carries high per-unit costs. Commercial viability depends on pushing down costs through yield improvements, throughput gains and feedstock optimization. Companies that move the cost curve early will unlock much larger addressable opportunities.
-
Manufacturing complexity: Reproducibility and quality control at scale are non-trivial. Investment in process analytics, inline metrology and supply-chain redundancy will be differentiators for those seeking to serve sensitive industrial customers.
-
Regulatory and sustainability considerations: Lifecycle impacts, material safety, and end-of-life handling will shape procurement decisions for large industrial OEMs. Proactive engagement with regulators and adoption of third-party certifications can accelerate acceptance.
-
Standards and interoperability: Early movers can shape performance standards; firms that participate in standards committees will influence testing protocols and compliance thresholds, creating indirect barriers to late entrants.
Actionable strategic imperatives for 2026
Based on the models and interviews underpinning the report, PW Consulting recommends a prioritized set of actions for corporate leaders planning to act in 2026:
-
Set a clear go/no-go gate for commercialization by Q2 2026: require defined milestones around cost-per-unit, reproducibility, and at least one LOI from a credible OEM or systems integrator.
-
Invest in pilot-line capability with modular expansion: build capacity to validate process recipes at commercial throughput while preserving optionality for scale-up or exit via sale/JV.
-
Pursue targeted partnerships over broad distribution: align with a few strategic customers for co-development to de-risk applications and secure initial purchase commitments.
-
Lock down critical inputs and develop contingency plans: secure long-lead materials and consider toll-manufacturing arrangements to avoid early supply bottlenecks.
-
Adopt a layered IP strategy: protect core manufacturing know-how while using selective licensing to accelerate market adoption where appropriate.
-
Define sustainability and compliance roadmap: complete lifecycle assessments and third-party testing early to preempt procurement barriers with environmentally sensitive customers.
-
Align commercial incentives with customers: design pilot pricing and warranty structures that reduce buyer switching costs and build reference cases.
How PW Consulting helps translate insight into outcomes
Our practice blends sector specialists, process engineers and M&A advisors to help clients convert the study’s intelligence into concrete actions: bespoke due diligence, pilot-to-production roadmaps, negotiation support for JV or licensing agreements, and tailored commercial plays to win first-mover customers. The full report contains the granular segmentation, supplier lists, and company-level competitive benchmarking necessary to execute the recommendations outlined above.
Next steps for leaders who intend to act in 2026
If your 2026 plan includes investment, partnership, or a procurement strategy for magnetic carbon nanofoam, the most valuable immediate steps are:
-
Obtain the full PW Consulting study to access segment-level forecasts, supplier scoring, and the scenario matrices that drive capital allocation decisions.
-
Commission a short, focused technical audit to validate your processes against the manufacturing playbook in the report.
-
Schedule a strategic workshop with our industry team to convert the report’s high-level guidance into a 6–12 month execution plan tailored to your company’s capabilities and risk appetite.
Magnetic carbon nanofoam represents a distinctive emerging materials opportunity: modest market size today, but with concentrated pockets of high-margin demand and a clear pathway to scale. The choices made in 2026 — about partnerships, scale-up investments, IP posture and standards engagement — will determine who captures the majority of the value as the market matures through 2032. For full access to the report’s datasets, detailed segment analyses, and company-level competitive profiling, please refer to the PW Consulting publication page.
For detailed analysis of this topic, please visit the official page: Worldwide Magnetic Carbon Nanofoam Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com