

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Aircraft GSE & MRO Market to Expand from USD 120.5 Billion in 2025 to USD 175.29 Billion by 2032 at a 5.48% CAGR, Driven by USD 104.4B in MRO Services

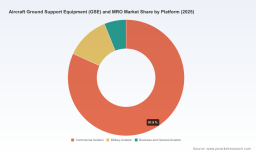
Worldwide Aircraft Ground Support Equipment (GSE) and MRO Market — Strategic Preview for 2026 Decision-Makers
Executive summary
PW Consulting’s newest market study, Worldwide Aircraft Ground Support Equipment (GSE) and MRO Market, synthesizes five years of historical behavior and seven years of forward-looking scenario analysis to equip executives with the actionable intelligence needed to make high-consequence decisions in 2026. The global market reached a pivotal scale in our base year (2025) and — under the central scenario modeled in the report — is projected to expand at a compound annual growth rate of 5.48% through the 2026–2032 forecast horizon, reaching materially higher total size by 2032. This trajectory reflects a combination of fleet recoveries, accelerated electrification rollouts, rising aftermarket demand and shifting commercial models such as rental and lifecycle services.
Worldwide Aircraft Ground Support Equipment (GSE) and MRO Market
Why 2026 is an inflection year
-
Capital cycles reset. Many airport operators, airlines and ground handlers are concluding multiyear maintenance and asset renewal programs initiated after the pandemic; 2026 is the year when incremental investments yield measurable operational and sustainability returns.
Worldwide Aircraft Ground Support Equipment (GSE) and MRO Market -
Electrification and infrastructure converge. Adoption of electric and hybrid GSE has moved from pilot to scale in pockets. Our study highlights that electrification is no longer a niche capex item — it requires coordinated power system planning, new procurement specifications and revised maintenance regimes.
Worldwide Aircraft Ground Support Equipment (GSE) and MRO Market -
Regulatory clarity is sharpening. International guidance bodies and regional regulators are converging on recommended practices for enhanced GSE safety, emissions reporting and autonomous operations. Decisions made in 2026 will lock in compliance pathways for the next decade.
Core market signals executives cannot ignore
-
Scale and growth: The market’s overall trajectory from the historical baseline through the forecast period demonstrates consistent expansion, creating both volume-led opportunities for OEMs and aftermarket growth for MRO providers.
-
Fragmentation with dominant niches: Market share is distributed — a meaningful proportion of demand is serviced by a broad base of specialized players even as a small number of global platform vendors capture a material share. This creates a two-track competitive landscape where scale advantages coexist with niche differentiation opportunities.
-
Energy and charging constraints are real: Large hub airports deploying electrified GSE may face peak power demands and annual electricity loads that require grid upgrades and sophisticated demand-management solutions. Our research cites operational examples where peak loading and megawatt-class planning became critical project drivers.
-
Technology bottlenecks persist on batteries and autonomy: Battery systems must satisfy safety, cycle-life and cold-weather performance requirements before full-scale replacement of legacy fossil-fueled fleets becomes universal. Similarly, autonomous/connected GSE is advancing rapidly, but interdependence with ATM, gate systems and ground safety regimes requires staged adoption.
Five strategic imperatives for 2026 planning
-
Plan energy infrastructure concurrently with fleet procurement. Treat charging and energy management as long-lead assets. Our electrification readiness modules show that failure to align procurement with site-level power capacity can add months and significant cost overruns to rollouts.
-
Shift from unit economics to lifecycle economics. The most value-accretive programs are those that couple acquisition decisions with MRO strategies, parts provisioning and telematics-driven predictive maintenance. Rental and managed-fleet models are reshaping working capital requirements for airlines and handlers.
-
Adopt a modular roadmap for autonomy. Begin with safety-enhancing driver-assist systems and telematics, then sequence higher autonomy modules. This minimizes operational disruption and aligns with evolving IATA recommended practices for testing and phased implementation.
-
Build supplier ecosystems, not just supplier lists. The shift to electric and automated GSE increases dependence on battery suppliers, power electronics integrators and local service partners. Strategic partnerships and captive rental/fl eet-management arrangements will be differentiators.
-
Embed regulatory modelling into procurement spec development. Regional programs — for example, state-level clean aviation initiatives and industry-wide safety recommendations — mean that procurement specs must be future-proofed against likely compliance requirements.
What the PW Consulting report delivers to executives
Our market study is designed as an operational toolkit for 2026 decision cycles, not merely a descriptive forecast. Key deliverables include:
-
Actionable scenario forecasts — base, upside and downside pathways with sensitivity levers tied to fleet utilization, electricity pricing and policy shocks.
-
CapEx and TCO models — configurable templates that compare diesel, hybrid and electric fleet economics under different duty cycles and energy price scenarios.
-
Electrification readiness assessments — checklist and sizing methodology for charging infrastructure and local grid upgrades, including demand-management options and on-site storage trade-offs.
-
MRO and aftermarket blueprints — staffing, parts stocking, depot design and predictive-maintenance playbooks tailored to different scale profiles.
-
Vendor benchmarking and procurement scorecards — a structured way to evaluate OEMs and service providers on performance, warranty/socialized risk, and retrofit pathways.
-
Regulatory mapping — alignment matrices that translate IATA guidance, regional programs and known survey initiatives into procurement and implementation checkpoints.
Competitive landscape — tactical takeaways
The competitive field combines global platform OEMs, specialized niche suppliers and diversified MRO giants. Several archetypes emerge:
-
Platform OEMs expanding electrified portfolios (e.g., manufacturers with towbarless tractors, loaders and bridge systems) — these players are pursuing integrated gate and ramp automation to capture higher-value systems work and recurring service revenue.
-
Component specialists and electrification enablers — firms focusing on GPUs, battery systems and charging/safety technologies are becoming critical partners to OEMs and operators as electrification accelerates.
-
MRO and lifecycle specialists — large MRO groups and aftermarket distributors are scaling capabilities to support fleet electrification, offering managed-services and retrofit programs that reduce operator risk.
Notable market movements highlighted in the study reinforce these archetypes: recent demonstrations of integrated gate and ramp automation, strategic partnerships to deploy electric GSE at scale in new geographies, new lithium-ion battery system introductions into the supply chain, and commercial rollouts of high-volume deicing and glycol transfer systems that materially affect turnaround operations and MRO planning.
Regulatory and technology items to model in 2026
-
IATA guidance on enhanced GSE and autonomous testing is maturing — incorporate recommended practices early to avoid retrofitting costs and to streamline certification paths.
-
Regional clean-air initiatives and survey programs will increasingly inform procurement eligibility and potential incentives; model these into investment cases for early movers.
-
Battery and safety constraints remain a gating factor for full electrification; expect incremental investments in battery management, weatherization, and depot fire-safety mitigations.
-
Energy systems planning is non-trivial at major hubs — peak load and annual energy consumption figures from exemplar airports demonstrate the scale of coordination required between airports, utilities and operators.
How 2026 executives should use this research
Procurement leaders, airport planners, finance chiefs and MRO heads should use the report to:
-
Rebase CapEx timelines using the report’s scenario outputs to align with funding cycles and sustainability targets.
-
Structure pilot programs around the report’s modular autonomy and electrification playbooks to de-risk scale-up.
-
Negotiate supplier agreements using our vendor scorecards and warranty-risk frameworks to preserve optionality for technology changes.
-
Create cross-functional implementation teams (energy, MRO, operations, procurement) using the report’s depot-design and charging-checklist templates to reduce integration friction.
Next steps
This preview is designed to demonstrate the practical depth and strategic orientation of PW Consulting’s analysis while preserving the full granularity and proprietary segment-level intelligence that support high-confidence decisions. For boards, investment committees and operational leaders embarking on GSE and MRO programs in 2026, the full study provides the underlying datasets, customizable financial models and procurement collateral necessary to move from strategy to execution.
Contact PW Consulting to obtain the complete Worldwide Aircraft Ground Support Equipment (GSE) and MRO Market report, access our scenario workbooks and schedule a briefing tailored to your organization’s 2026 decision calendar.
For detailed analysis of this topic, please visit the official page: Worldwide Aircraft Ground Support Equipment (GSE) and MRO Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com