

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Specialty Oxidant Market to Reach USD 4,567.02 Million by 2032, Growing at a 5.45% CAGR (2026–2032)

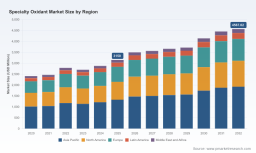
Worldwide Specialty Oxidant Market — Strategic Outlook 2026: PW Consulting Release
Executive summary
PW Consulting’s new Worldwide Specialty Oxidant Market report provides corporate leaders with the strategic context and operational playbook they need to act confidently in 2026. The global specialty oxidant market reached an estimated USD 3,150.0 Million in our base year (2025) and is modeled to grow at a compound annual growth rate (CAGR) of 5.45% over the 2026–2032 forecast horizon, reaching roughly USD 4.57 Billion by 2032 under our central case. This growth reflects persistent demand from high-purity industrial applications, accelerated decarbonization investment, and shifting remediation and water-treatment priorities.
Worldwide Specialty Oxidant Market
Why 2026 is a strategic inflection point
-
Capacity rebalancing and localization: Several incumbent suppliers are completing targeted capacity investments or product launches that materially alter regional supply dynamics. These moves compress near-term arbitrage opportunities while creating new pathways for long-term differentiation based on product grade and sustainable credentials.
Worldwide Specialty Oxidant Market -
Feedstock and energy volatility: Production of key oxidants remains anchored to energy- and feedstock-intensive chemistries. Our analysis shows that AO-based hydrogen peroxide production is particularly exposed to natural gas, electricity, and anthraquinone carrier dynamics—risk factors that will drive margin divergence between low-cost incumbents and nascent low-carbon offerings.
Worldwide Specialty Oxidant Market -
Regulatory and logistics cost shock: Tightening regulation on high-strength peroxide grades (notably rules affecting explosives-precursor control in parts of Europe and adjacent regions) has increased distribution complexity and cost for certain grades. Commercial teams must factor these distribution overlays into 2026 pricing, contract design, and go-to-market plans.
Key market signals captured in the report
-
Market momentum: The market has demonstrated steady recovery and expansion since the 2020–2025 period. Our supply-demand modelling indicates structural growth driven by electronics-grade oxidants, remediation-focused persulfates, and an incremental premium for low-carbon H2O2.
-
Price and inventory indicators: Regional spot-price swings and inventory adjustments remain a leading indicator of near-term margins. For example, Indian industrial-grade hydrogen peroxide experienced meaningful price softening in Q3 2025 (reported regional reference bands) as inventories rebalanced—an early sign that demand segmentation is not uniform.
-
Concentration and competitive balance: Market concentration is moderate: the top-three and top-five suppliers account for meaningful shares, creating oligopolistic behaviors in certain product-grade bands and a fertile environment for targeted disintermediation or vertical integration plays.
Competitive landscape — what the leaders are doing
Our competitive profiling synthesizes public disclosures, plant-level capacity intelligence, product launches, and strategic signals from leading suppliers. Highlights include:
-
Nouryon — positioned as a specialty oxidant platform with a broad industry footprint. Recent product innovation with lower-carbon hydrogen peroxide variants signals an aggressive play to capture premium, sustainability-conscious customers in pulp & paper, mining, and water treatment.
-
Evonik — doubling down on high-purity specialty H2O2 for electronics and photovoltaics. A newly completed specialty-grade hydrogen peroxide plant in Leshan (trial production underway in 2026) introduces a sizeable, high-purity capacity that will reshape competitive dynamics in APAC for semiconductor-grade supply.
-
Solvay — continuing to expand high-purity output in China and to secure position in electronics and water-treatment markets via site-level capacity upgrades.
-
Arkema, BASF, Mitsubishi Gas Chemical, Kemira, Aditya Birla Chemicals and FMC — each leverages differentiated technologies or product portfolios (organic peroxides, persulfates, peracetic acid, specialty grades) to pursue vertical or specialty niches where margins and technical barriers are higher.
-
Market concentration metrics (CR3 and CR5) in our model underline a market where scale matters but where targeted product differentiation and local regulatory agility can outweigh pure scale in many commercial matchups.
Report contents — practical modules for decision-makers
PW Consulting’s report is built for action. The following functional modules translate market intelligence into executable initiatives for 2026:
-
Supply-demand and price modelling: plant-level capacity maps, utilization scenarios, and sensitivity runs tied to fuel and anthraquinone feedstock cost inputs.
-
Regulatory impact assessment: granular implications of transport and precursor controls across major trading corridors and how these change effective landed costs.
-
Feedstock risk dashboard: quantifies exposure to AO process inputs, anthracene price shocks (including observed uplifts), and electricity/gas cases across producer footprints.
-
Competitor matrix and capability heatmap: public and proprietary signals on new plants, product launches, JV structures, and low-carbon credentialing.
-
Commercial playbook: price architecture templates for long-term offtake, spot-inventory strategies, and customer segmentation that align grade, logistics, and contract tenor.
-
Operations & decarbonization pathways: CAPEX scheduling simulations for retrofit vs greenfield, and marginal abatement cost curves for electrification and feedstock switching.
-
M&A and partnership compass: targets and value-creation cases for bolt-on acquisitions, tolling agreements, and co-investment in localized high-purity capacity.
Strategic imperatives for 2026 — an executive checklist
-
Re-price with distribution overheads in mind. Incorporate regulatory-driven distribution adders into 2026 tariffs for certain grades and regions; short-term margin erosion will follow if not pre-priced.
-
Prioritize feedstock and energy hedges. Given the AO-process exposure to natural gas and anthraquinone carriers, procurement should implement layered hedges and strategic storage where cost-effective.
-
Invest selectively in specialty and low-carbon grades. Our market scenarios show higher-than-average margin expansion for certified low-carbon hydrogen peroxide and high-purity electronic grades—areas where first-mover investments (or offtake-linked partnerships) can secure durable premiums.
-
De-risk logistics and compliance. For product bands facing tightened precursor controls, create alternate distribution pathways (domestic production, controlled cross-border corridors, or compliant intermediated logistics) to avoid commercial disruptions.
-
Refine portfolio by channel: separate commodity H2O2 plays from specialty oxidant propositions (persulfates, organic peroxides, chlorites/chlorates) and align sales incentives and service models accordingly.
-
Use M&A to buy capability, not just capacity. Targets that provide analytics, local distribution, or specialty-formulation know-how are higher-value than undifferentiated tonnage buys.
Case signals you cannot ignore
-
Evonik’s Leshan plant (announced operational ramp in 2026) demonstrates how targeted, high-purity additions can alter regional tightness and pricing in electronics supply chains—buyers and competitors must respond to preserve continuity.
-
Nouryon’s low-carbon product launch shows how sustainability-labelled chemistry can command differentiated positioning across end markets—marketing and verification will become commercial gating criteria.
-
Supply shocks in AO feedstock markets (including significant anthracene price moves in 2025 in certain regions) show that producers with feedstock flexibility or alternative technology pathways enjoy structural advantage in margin resilience.
How PW Consulting helps
Our advisory services translate the report’s insights into a tailored roadmap for your organization. Services include plant-level scenario modelling, procurement hedging frameworks, product positioning workshops, and M&A diligence on target assets. For firms with exposure to electronics, remediation, water treatment, or pulp & paper end-markets, we provide rapid 8–12 week engagement packages that convert market intelligence into executable 90-day plans.
Call to action
This release intentionally presents high-level strategic takeaways while withholding the granular segmentation and per-region / per-application breakdown that underpin our modelling—these are available exclusively in the full report. Executives who need the underlying data tables, plant maps, price curves, and customer-level scenarios for 2026 decision-making should consult the full PW Consulting Worldwide Specialty Oxidant Market report or contact our industry team for a briefing.
PW Consulting — turning market complexity into strategic advantage for 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Worldwide Specialty Oxidant Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com