

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting: E-Liquids Market to Reach USD 2.47B by 2032 at 12.58% CAGR
By pmarketresearch, 2026-07-23
E‑Liquids Market: Strategic Brief for 2026 Decision‑Making
PW Consulting’s latest E‑Liquids Market study provides a forward‑looking intelligence package designed to convert macro momentum into executable strategy for 2026. Built on a historical series (2020–2025) and a detailed forecast window (2026–2032), the research quantifies a robust recovery and growth trajectory — driven by product innovation, channel shifts, and a rapidly evolving regulatory landscape. The market, which stood at a mid‑2020s base of approximately USD 1.125 billion (base year 2025), is projected to expand at a compound annual growth rate of 12.58% through the forecast period, effectively more than doubling by the end of the horizon. This brief explains why the report is a strategic asset for executive teams while intentionally holding back the granular segment tables that appear in the full study.
E-Liquids Market
Why this report matters for 2026
-
Timing: 2026 is a pivot year. Recent regulatory decisions and commercial investments have created a bifurcated landscape where authorized, compliant offerings can gain privileged access to the largest consumer channels — while non‑compliant players face compounding market risks.
E-Liquids Market -
Clarity on scale and trajectory: With a clear historical base and a transparent growth model, leadership teams can assess horizon planning (capacity, working capital, pricing) against a defensible market size and growth curve.
E-Liquids Market -
Practicality: The report translates macro projections into operational levers — from SKU rationalization to plant footprint decisions — giving C‑suite and business unit leaders immediate, actionable choices rather than abstract forecasts.
-
Risk quantification: Regulatory shocks and channel closures are modeled in multiple scenarios; this allows management to simulate downside impacts and construct hedges ahead of material events.
What the full study delivers (practical highlights)
-
Proprietary market model with historical reconciliation (2020–2025) and scenario‑based forecasts through 2032.
-
Regulatory impact module that overlays country‑level policy changes on demand and price models.
-
Commercial playbooks for top‑line growth: channel segmentation, pricing archetypes, promotion elasticity and D2C rollouts.
-
Supply‑chain and manufacturing toolkit: capacity vs. demand maps, quality and compliance gating, and an investment case for brownfield/greenfield expansions.
-
M&A and partnership screening: shortlist of target archetypes, valuation multipliers under different integration synergies, and post‑deal 100‑day playbook templates.
-
Brand and SKU optimization framework: margin‑weighted SKU pruning, innovation road‑maps for flavor and format, and packaging/cost trade‑offs.
-
Investor and board‑ready slide decks and financial models for scenario planning.
Macro picture: growth trajectory and market structure
The market’s trajectory from 2020 through 2025 establishes a consistent expansion pattern that accelerates into the forecast window. From a modest base in the early 2020s, the sector advances to a mid‑2020s market size near the USD 1.125 billion mark, then climbs steadily under our central scenario to reach an estimated USD 2.47 billion by 2032 — the result of ongoing product substitution, new adult user uptake in permitted channels, and premiumization across certain formats. The implied compound annual growth rate of 12.58% across the forecast period encapsulates both structural growth (category adoption and device upgrades) and cyclical drivers (regulatory approvals and trade‑channel reconfiguration).
Concentration metrics indicate a market where leading players command a dominant share footprint: the top three firms hold a majority share, while the top five collectively account for a very substantial proportion of market value. This structure creates both defensive moats for incumbents and white‑space opportunities for well‑capitalized challengers that can differentiate on regulatory compliance, brand trust, or supply reliability.
Competitive landscape: strategic implications for incumbents and challengers
The competitive field is heterogeneous and can be usefully viewed in three clusters.
-
Big tobacco and diversified incumbents (e.g., Philip Morris International, British American Tobacco, Imperial Brands, Japan Tobacco International): These companies bring scale in regulatory affairs, distribution, and capital. Their global footprint and access to regulated channels make them natural beneficiaries of favorable product authorizations. Strategic priorities should focus on portfolio rationalization (emphasize compliant SKUs), supply chain resilience, and targeted premiumization to protect margin as unit volumes scale.
-
Pod and device specialists (e.g., JUUL Labs, Logic Technology Development, NJOY): These players compete on device design, nicotine delivery characteristics, and rapid go‑to‑market of new formats. The path forward rests on achieving regulatory clearances in priority markets, proving robust youth‑access prevention measures, and forging retailer partnerships that favor tested, authorized SKUs.
-
OEM/ODM and independent e‑liquid manufacturers (e.g., Hangsen, Vape Base Ltd, Ruthless Vapor, Mister‑E‑Liquid): These suppliers are pivotal to capacity and white‑label growth. Their competitive levers are formulation agility, manufacturing quality (USP‑grade inputs), and global distribution to independent retail. For contract manufacturers, the fastest route to growth is investment in compliant production lines, traceability systems, and customer co‑development programs with leading device OEMs.
Recent commercial and regulatory developments underscore these dynamics. The U.S. Food and Drug Administration’s authorization waves (including the May 2026 authorization of several Glas ENDS products) are reshaping retail assortment rules and elevating authorized product economics. Simultaneously, the roll‑out of duties and tax regimes (e.g., the UK’s Vaping Products Duty applications opened in April 2026) and state‑level compliance regimes are changing price floors and operating compliance costs across markets. Retail‑level activity — exemplified by trade shows and bespoke category spaces for e‑liquids — suggests continued vibrancy in independent and specialty channels even as mainstream shelf access tightens for authorized SKUs only.
Regulatory and policy dynamics to prioritize
-
Authorization scarcity in the U.S.: As of mid‑2026, only a limited set of ENDS products are legally marketed. This scarcity creates a two‑tier channel system where authorized brands can command better shelf access and lower trade resistance.
-
New tax instruments and duties: Emerging excise regimes will compress margins for lower‑end SKUs and create incentives for product reformulation or premiumization.
-
State and provincial compliance: Tighter manufacturer certification rules and directory requirements at sub‑national levels increase operating overhead for smaller producers and create an advantage for firms with compliance infrastructure.
-
Retail and channel compliance: Retailers are tightening sourcing controls — preference is given to products with clear regulatory pathways and documented quality systems.
Immediate strategic imperatives for 2026
-
Prioritize regulatory gating: Map your SKU set to regulatory pathways now. Accelerate clinical, toxicology and youth‑access mitigation evidence where required to pursue authorization slots.
-
Right‑size manufacturing: Use the report’s capacity model to decide whether to expand, outsource, or form tolling partnerships. Avoid capex commitment until you reconcile authorization probabilities across priority markets.
-
Portfolio triage and premiumization: Reallocate SKU and marketing dollars toward formats and flavors that align with permitted channels while pruning low‑margin assortments.
-
Channel hedging: Grow authorized direct channels (D2C with strong age‑verification) and maintain strategic relationships with specialty retail that can support niche innovation.
-
M&A and partnerships: Seek bolt‑on targets that bring capacity, compliance expertise, or access to authorized channels. Use the study’s acquisition filters to prioritize targets by integration complexity and payback horizon.
-
Operationalize compliance: Invest in batch traceability, supplier audits, and product stewardship programs to lower regulatory and reputational risk.
How to use the full PW Consulting report
This brief outlines the strategic contours you need to act now. The full report contains the missing detail critical to execution: granular regional demand curves, flavor and format segmentation, channel‑level price bands, elasticity matrices, supplier cost curves, and a prioritized list of commercially viable M&A targets. It also includes playbooks for market entry, a regulatory probability matrix, and downloadable financial models patched to our central and alternate scenarios.
For teams designing 2026 capital plans, go‑to‑market roadmaps, or M&A pipelines, the study serves as both a diagnostic and a transaction tool. PW Consulting stands ready to deliver tailored workshops that convert the report’s insights into a 90‑day action plan aligned to your P&L and balance sheet realities.
To access the complete segmentation tables, scenario outputs and company‑level benchmarking that underpin the strategic recommendations in this brief, visit the research page linked from PW Consulting’s E‑Liquids Market offering. The full dataset is where the operational levers live — and where your execution roadmap begins.
For detailed analysis of this topic, please visit the official page: E-Liquids Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Electronic Circuit Breaker Market to reach USD 10,835 Million by 2032 (5% CAGR)
By pmarketresearch, 2026-07-23
Electronic Circuit Breaker Market — Strategic Primer for 2026 Decision-Makers
As organizations accelerate electrification across industrial, transportation and building portfolios, electronic circuit breakers are becoming core components of modern power distribution and protection architectures. This executive primer, prepared by PW Consulting, synthesizes the high-level market signal and strategic implications from our comprehensive Electronic Circuit Breaker Market study (base year 2025, historical 2020–2025, forecast 2026–2032). It is designed to orient senior executives and investment committees on the opportunities and structural risks that should shape decisions in 2026 — while reserving detailed segment-level intelligence for the full report.
Electronic Circuit Breaker Market
Market snapshot: scale, trajectory and structure
The electronic circuit breaker market has demonstrated resilient expansion through the early 2020s and entered 2026 on a steady growth trajectory. On a consolidated basis the market reached approximately USD 7.7 billion in 2025 and is projected to grow at a compound annual growth rate (CAGR) of around 5.0% through 2032, culminating in a markedly larger addressable market by the end of the forecast window.
Electronic Circuit Breaker Market
Competitive concentration remains moderate: the top three firms control under half of the market, and the top five together account for roughly mid‑40s percent share. That dispersion preserves opportunities for technology differentiation, targeted regional plays, and partnerships — while also elevating the importance of scale and go‑to‑market efficiency for aspirant market leaders.
Electronic Circuit Breaker Market
Why this matters for 2026 strategic planning
- Investment timing : With a stable mid‑single-digit CAGR and clear secular tailwinds (electrification, renewable integration, automation), 2026 is a window to accelerate product development and channel expansion without expecting explosive near‑term demand shocks. Capital allocation should prioritize scalable digital features and modular architectures that unlock adjacent revenue streams.
- Portfolio prioritization : Firms must align product roadmaps to serve DC-intensive applications and smart distribution use cases while preserving modular designs for legacy AC deployments. Prioritization should be guided by an outcomes-based ROI model that factors in lifetime monitoring revenues and service contracts, not just initial hardware sales.
- Risk-adjusted M&A and partnerships : Moderate market concentration implies the M&A market will favour bolt-ons that provide technical or channel advantages rather than transformative consolidation. Strategic acquisitions should target sensor/telemetry software, power-electronics IP, or established relationships in high-growth verticals.
Competitive landscape — who is shaping the market
The market is anchored by incumbent electrical and automation leaders and a set of specialist manufacturers. These companies are competing across three vectors: switching performance and protection granularity, digital integration/monitoring, and system-level interoperability. Notable participants shaping technology and go‑to‑market dynamics include:
- Phoenix Contact (Blomberg, Germany) — Offers single‑channel electronic circuit breakers for low‑voltage DC applications with a focus on modular integration and customizable protection. Recent product updates have strengthened its position in DC feed‑in monitoring.
- Siemens (Munich, Germany) — Competing with solid‑state, high‑speed solutions for DC systems and emphasizing microsecond switch‑off performance for short‑circuit mitigation; their 2026 product introductions target precision protection in renewable and industrial setups.
- Eaton (Dublin, Ireland) — Leverages broad low‑voltage protection portfolios and smart‑grid positioning to push integrated solutions into industrial automation environments.
- Schneider Electric (Rueil‑Malmaison, France) — Focuses on converged hardware‑software breaker offerings with advanced monitoring and automation capabilities for commercial and utility adjacent markets.
- ABB (Zurich, Switzerland) — Combines electrification and automation strengths to serve smart manufacturing and DC microgrid integration use cases.
Recent product developments underscore an acceleration in both performance and connectivity. For example, Phoenix Contact extended its CAPAROC platform in mid‑2025 with enhanced Modbus/TCP communications for DC distribution monitoring, while Siemens launched a fully electronic solid‑state breaker in early 2026 emphasizing microsecond switching for short‑circuit reduction. These moves illustrate how product cycles are increasingly driven by digital and safety‑performance differentials rather than pure price competition.
Market dynamics and supply‑side considerations
- Component supply sensitivity — Electronic circuit breakers are component‑heavy devices. The availability and price of key semiconductors and passive components materially affect production costs and lead times. Recent disruptions in 2024–2025 have shown that suppliers and OEMs with multi‑sourced bill‑of‑materials strategies materially outperform peers on delivery reliability.
- Regulatory and certification drivers — Regulatory regimes remain a gating factor for market access. In North America, UL certification continues to be mandatory for many applications, and design roadmaps must allocate development cycles and testing budgets accordingly. Meanwhile, compatibility with established electrical codes for specific product lines is a continuing engineering constraint that benefits experienced incumbents.
- Trade and tariff volatility — Tariff actions introduced in 2025 have already affected pricing and supply chains for DC protection products. Companies should assume episodic trade volatility as a baseline scenario and embed mitigation options (regional inventory, alternate routing, contractual hedges) into procurement strategies.
What PW Consulting’s full report provides (practical, decision‑ready deliverables)
Our full Electronic Circuit Breaker Market report delivers the operational intelligence that procurement leaders, product chiefs and corporate strategy teams need to make confident 2026 choices. Key deliverables include:
- Validated market sizing and demand forecasts (2020–2032) with scenario variants that stress component disruptions, tariff shocks, and accelerated renewable penetration.
- Strategic segmentation frameworks that reveal high‑margin use cases, adjacent product bundling opportunities, and prioritized verticals for go‑to‑market deployment.
- Competitive intelligence dossiers on the leading OEMs (including recent product launches and roadmap indicators), plus a watchlist of emerging challengers and IP plays.
- Supply chain resilience playbook — supplier risk scoring, alternative sourcing tactics, and inventory optimization levers calibrated to the component‑level risk profile.
- Regulatory impact analysis with compliance timelines and testing cost estimates for major markets, plus recommendations for certification sequencing to minimize time‑to‑market friction.
- Commercial models and pricing elasticity experiments that map feature bundles to lifetime service revenue and channel economics.
- Actionable M&A and partnership criteria, including target screening filters and integration checklists tailored for technology and regional priorities.
Each module is accompanied by operational templates — e.g., an ROI calculator for embedded monitoring features and a sourcing contingency matrix — so teams can move from insight to execution without starting from first principles.
Recommended 90‑ to 180‑day actions for 2026
- Execute a rapid supplier stress test : Conduct a component‑level audit of lead times, single‑source risks and tariff exposure. Identify at least two mitigation levers for every high‑risk component (qualified alternates, buffer stock, contractual pass‑throughs).
- Prioritize digital retrofit pathways : Accelerate pilot deployments that retrofit monitoring/telemetry to installed breaker bases — proving recurring service revenues and differentiation while leveraging existing hardware footprints.
- Fast‑track certification timelines : For products targeting North America, align R&D and testing schedules to ensure UL certification pathways are locked in — this reduces launch slippage and commercial risk.
- Structure a disciplined M&A queue : Shortlist targets that provide missing software capabilities or channel access rather than purely hardware scale; define integration metrics and post‑deal value capture plans in advance.
- Design tariff‑aware pricing : Implement flexible pricing architecture and contract clauses that allow for cost pass‑throughs or hedging against tariff-driven input cost increases.
Conclusion — the strategic edge of informed timing
The electronic circuit breaker market presents a classic strategic inflection: steady, predictable growth at the market level contrasts with volatile inputs and rapidly evolving product expectations at the firm level. This creates an environment where well‑timed investments in digital integration, supply chain resilience, and certification readiness can deliver outsized returns in 2026 and beyond. PW Consulting’s full study provides the granular segmentation, company benchmarks and scenario models required to convert these high‑level imperatives into executable plans.
To preserve the commercial value of our segment‑level intelligence, we have intentionally withheld detailed regional and application splits from this primer. Access the full report for the complete datasets, proprietary segmentation matrices and executable templates that will equip your leadership for confident decisions in 2026.
For detailed analysis of this topic, please visit the official page: Electronic Circuit Breaker Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Cabin Air Quality Sensors to hit USD 4.24B by 2032 at 6.98% CAGR
By pmarketresearch, 2026-07-23
Automotive Cabin Air Quality Sensor Market: Strategic Preview for 2026 Decision Makers
As global mobility pivots toward electrification, connectivity and occupant-centric design, cabin air quality (CAQ) sensing has moved from a niche comfort feature to a strategic vehicle subsystem. This preview synthesizes the core strategic implications of PW Consulting’s comprehensive Automotive Cabin Air Quality Sensor Market study — published with a 2025 base year and a 2026–2032 forecast horizon — and explains why our findings should shape procurement, product development and partnership choices made in 2026. The full report delivers the underlying datasets, supplier scorecards and scenario-specific recommendations; here we surface the directional insights and the decision levers executives cannot afford to ignore.
Automotive Cabin Air Quality Sensor Market
Market snapshot: a clear growth runway
Our market model shows a sustained growth trajectory for cabin air quality sensing, reflecting widening regulatory pressure, rising consumer health awareness and increasing sensor content per vehicle — especially in electrified and premium segments. Using 2025 as the base year, the global market is modeled across 2020–2032 and forecasts a compound annual growth rate (CAGR) of 6.98% through the 2026–2032 period. By 2032 the market is projected to be noticeably larger than in 2025, presenting clear revenue expansion opportunities for system suppliers, OEMs and tier-one integrators that move early.
Automotive Cabin Air Quality Sensor Market
Why 2026 is a pivotal year for corporate strategy
- Regulatory inflection points: With the EU enforcing in‑cabin air quality standards since 2024 and multiple technical bodies publishing real‑world measurement and adaptive control standards in 2026, compliance timelines and testing protocols are converging. Companies must assume more stringent product validation and reporting requirements in upcoming vehicle homologation cycles.
- Technology convergence: CAQ sensing is no longer a one-dimensional PM sensor story. Multi‑parameter modules (PM, VOCs, CO2/equivalents, formaldehyde proxies) connected to adaptive HVAC and AI analytics are becoming the platform standard for OEMs seeking differentiated occupant health propositions.
- OEM architecture decisions: Integrators must choose between sensor-as-module suppliers, platform partnerships with HVAC vendors, and in-house sensor development. Each route has different margin, IP and supply-chain exposure implications that should be resolved in 2026 procurement cycles.
- Electrified vehicle priorities: EV buyers place a premium on cabin comfort and perceived health benefits; battery electrification also changes HVAC energy budgets, making energy‑aware CAQ strategies (sensor-driven filtration and circulation) an ROI lever for vehicle range managers and feature packages.
Key dynamics shaping supplier and OEM strategies
- Standards and test methods: The appearance of SAE technical papers in 2026 addressing real‑time CAQ impacts, adaptive HVAC strategies and interior material emissions underscores that test methodologies will be standardized soon. Suppliers that align early with SAE and regulatory testbeds will reduce time-to-market friction for their OEM customers.
- Regulatory enforcement: National and regional regulations — exemplified by existing limits in some markets for interior formaldehyde — will drive baseline CAQ functionality as a compliance requirement rather than an optional comfort feature in many vehicle classes.
- Sensor performance and lifecycle: Advances in MEMS, laser-based particulate sensing and multi-parameter electrochemical/metal-oxide gas sensing are improving accuracy and durability expectations. Suppliers that can demonstrate long-life calibration stability and low maintenance will win OEM specification slots in 2026–2027 programs.
- Data and service layer monetization: CAQ data combined with telematics and cabin occupancy sensing enables new services — predictive filter replacement, air-quality-as-a-service for shared mobility operators, or health-oriented alerts. Strategy teams must balance privacy/regulatory constraints with monetization models.
- Supply-chain resilience: Materials and sub-component sourcing remains a strategic risk. Vertical integration or multi-sourcing strategies for critical sensing elements and CO2/VOC detectors will reduce program risk for OEMs launching in the 2027–2029 model years.
Competitive landscape — what the majors are doing (high‑level)
The supplier ecosystem is composed of large multi-domain automotive suppliers, specialized sensor manufacturers and system integrators. While a number of established players compete for OEM mandates, the market remains sufficiently open for new entrants with differentiated technology or platform approaches.
Automotive Cabin Air Quality Sensor Market
- Robert Bosch GmbH (Gerlingen, Germany): Leveraging decades of automotive sensor integration and HVAC system relationships, Bosch offers advanced cabin air quality modules positioned for passenger vehicles and EVs. Their scale and OEM relationships make them a go‑to for platform-level integration.
- Denso Corporation (Tokyo, Japan): Denso is advancing VOC detection capabilities and tighter HVAC integration. Its supplier role to several global OEM programs gives it priority in specification discussions for comfort and air‑quality packages.
- Valeo (Paris, France): Valeo’s smart sensor platforms emphasize OEM integration and real‑time pollutant detection. Their recent platform announcements highlight a focus on software-enabled differentiation for fleet and fleet-service applications.
- Honeywell International Inc. (Charlotte, USA): Honeywell’s 2025 introduction of an AI-enabled sensor module for EVs signals a push into analytics-enabled filtration control and adaptive systems — positioning them at the intersection of sensor hardware and edge analytics.
- Amphenol Corporation (Wallingford, USA): Amphenol’s recent sensor series targets improved accuracy and durability for global OEMs, reinforcing their role as a reliable tier‑one supplier for volume programs.
- Hella GmbH (Lippstadt, Germany): Hella continues to supply vehicle electronics and CAQ sensors with an emphasis on integration into passenger vehicle networks and comfort subsystems.
- Sensirion AG (Stäfa, Switzerland): As a specialist in particulate matter sensing, Sensirion’s partnerships (notably a 2025 co‑development announced with an OEM group) show the strategic value of combining sensor IP with OEM system engineering.
- Cubic Sensor and Instrument Co., Ltd. (Wuhan, China): Focused on PM sensors with long-life claims, Cubic targets specific regional OEMs and cost-sensitive programs where lifecycle durability is a key procurement criterion.
Recent vendor activity through 2025 — including AI-enabled modules, strategic OEM co‑development agreements and multi‑year supplier contracts — indicates that 2026 OEM sourcing rounds will favor suppliers who can demonstrate validated system performance, regulatory test compliance and software/hardware co‑development capabilities.
Strategic levers for buyers and suppliers in 2026
- For OEMs and mobility operators: Re-evaluate CAQ sensor sourcing as part of powertrain‑agnostic feature packs. Require verification test protocols aligned to emerging SAE methods. Consider bundling CAQ data into connected services to recover unit costs while navigating privacy regulation.
- For sensor suppliers: Prioritize robust calibration strategies, long‑term drift testing and formal compliance evidence. Differentiate on integration ease (API/ECU interfaces), life‑cycle cost and co‑development support for HVAC calibration and filter optimization.
- For tier‑one integrators and software providers: Build platform propositions that combine multi‑parameter sensing with adaptive HVAC control and predictive maintenance. Demonstrate energy trade‑offs for EV range optimization tied to CAQ control strategies.
- For investors and corporate strategy teams: Target M&A or partnership activity in specialists who bring either unique sensing IP, proven OEM programs, or strong software/analytics stacks that can be embedded quickly into vehicle platforms launched 2027–2029.
What PW Consulting’s full report contains (practical components)
Our in‑depth study is designed as an executional playbook for 2026 decisions. Key deliverables include:
- Granular market model (historical 2020–2025 / forecast 2026–2032) with scenario variants keyed to regulatory tightening and EV adoption curves.
- Technology roadmap outlining sensor modalities (PM, VOCs, CO2 proxies, formaldehyde indicators), expected cost and performance trajectories, and integration timelines.
- Regulatory and standards mapping with timing implications for homologation and OEM procurement windows.
- Supplier benchmarking and scorecards covering product breadth, system integration capabilities, software assets and program wins.
- Use‑case playbooks for passenger cars, commercial vehicles and shared mobility — including implementation checklists, OPEX/CAPEX tradeoff templates and data monetization options.
- Supply‑chain risk heatmaps and mitigation strategies, plus supplier shortlists for different procurement strategies (cost, performance, resilience).
- Commercial negotiation guides, sample technical specifications and test protocol alignment templates that accelerate supplier selection.
How to use these insights in 90 / 180 / 360 day plans
- 90 days: Update procurement RFQs to include multi‑parameter performance metrics and SAE-aligned test requirements; initiate pilot engagements with one hardware and one software partner.
- 180 days: Finalize supplier selections for 2027 programs, negotiate long‑lead components with secondary suppliers, and begin integration of CAQ data into vehicle telematics/UX designs.
- 360 days: Lock software/hardware co‑development milestones into program timelines, validate systems in homologation testbeds and prepare go‑to‑market packages for differentiated CAQ features.
Final thoughts — the strategic payoff
By 2026, cabin air quality sensing will be a material contributor to vehicle differentiation, regulatory compliance and new data-driven services. Firms that treat CAQ primarily as a commoditized sensor purchase will miss opportunities in software-driven differentiation, aftermarket/servicing revenue and regulatory-aligned product positioning. Conversely, suppliers and OEMs that coordinate product, software and regulatory strategies now will capture both near-term program wins and durable platform value through 2032.
PW Consulting’s full Automotive Cabin Air Quality Sensor Market report delivers the datasets, supplier insights and tactical tools required to convert this market trajectory into measurable revenue and competitive advantage. For access to the model, scorecards and actionable annexes, please visit our report page or contact your PW Consulting analyst.
For detailed analysis of this topic, please visit the official page: Automotive Cabin Air Quality Sensor Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: TCB Bonder Market to Surge at 18.31% CAGR, Reaching USD 679.93M by 2032
By pmarketresearch, 2026-07-23
TCB Bonder Market — 2026 Strategic Outlook: A PW Consulting Preview
As PW Consulting’s lead industry analyst, I present a concise, strategy-focused preview of our new TCB (thermocompression) Bonder Market study. This briefing distills the study’s executive implications for enterprise decision-makers planning 2026 capital, product, and M&A strategies. It demonstrates the analytical depth of our full report while intentionally withholding granular regional and application breakdowns — the precise data tables and vendor scorecards are available in the full report for subscribers and clients.
TCB Bonder Market
Market Trajectory: What the macro numbers tell you
Thermocompression bonder demand has entered a high-growth phase driven by advanced packaging requirements, medical-device miniaturization, and rising adoption in photonics and high-performance compute subsystems. On a market-wide basis, the industry more than doubled in size during the 2020–2025 historical period and reached a clear inflection point in 2025. From this base year, our modelling shows the market expanding at a sustained, high-teens compound annual growth rate (CAGR) over the 2026–2032 forecast window — a rise that translates into roughly threefold market scale by the end of the decade under the baseline scenario.
TCB Bonder Market
Why these headline figures matter for 2026 planning: growth at this magnitude compresses the typical technology adoption curve, shortens payback windows for automation investments, and moves supplier selection from “nice to have” to strategic gatekeeping for manufacturing competitiveness. Capital allocation decisions taken in 2026 will either secure capacity and capabilities for the next product cycle, or risk being priced out or capacity-constrained as demand accelerates.
TCB Bonder Market
Strategic themes that will shape 2026 decisions
-
From throughput to tolerance: Buyers are no longer solely focused on cycle time; sub-micron placement accuracy and repeatable heat-and-pressure profiles are now equally critical for advanced multi-die constructs and hybrid bonding workflows.
-
Regulatory and premium markets: Medical and other regulated end-markets command differentiated system specifications and documentation practices, driving willingness to pay for medical-grade platforms and certified suppliers.
-
Concentration and counterparty risk: The market exhibits meaningful concentration at the top end of the supplier base. That amplifies supply-side bargaining power for market leaders, and raises the premium for qualification programs and long-term service commitments with those vendors.
-
Modularity as optionality: Platforms that permit modular upgrades (automation, vision systems, thermal controls) are valuable for firms balancing near-term costs against long-term capability needs.
Regulatory and medical-device dynamics — operational implications
Medical-device applications represent a strategically important, higher-margin segment for TCB equipment. These customers require stringent documentation, lot traceability, and facility-level qualifications aligned with Class II/III device manufacturing. For suppliers, that translates into extended qualification cycles, premium pricing, and long-term service contracts. For buyers, it means procurement timelines must factor in regulatory lead times and validated change-control processes — delaying a decision by a few quarters can impose months of lost time for product launches in regulated portfolios.
Competitive landscape: what to watch in supplier selection
The competitive map is anchored by a set of specialized equipment vendors delivering differentiated value propositions. Our report profiles each vendor not merely by headline claims but by tested performance metrics, field yield evidence, and aftermarket responsiveness. High-level competitive themes include: ultra-fine pitch thermomechanical control, sub-micron placement and high-throughput die attach systems, large-panel support for new form factors, and niche offerings tailored to medical/photonic device makers.
-
Kulicke & Soffa Industries, Inc. (Willow Grove, PA, USA) — APAMA™ PLUS series and advanced thermo-compression platforms focusing on ultra-fine pitch interconnects with precise heat-and-pressure control for high-density assembly. ( https://www.kns.com/)
-
ASMPT Amicra (Singapore) — NOVA Pro die attach systems emphasizing die placement accuracy and short cycle times for high-volume TCB production. ( https://www.asmpt.com/)
-
BE Semiconductor Industries N.V. (BESI) (Duiven, Netherlands) — Thermocompression systems proven in volume for advanced flip chip and die bonding (CoWoS, HBM) deployments. ( https://www.besi.com/)
-
Toray Engineering Co., Ltd. (Japan) — Flip chip bonders supporting TCB, DAF, and hybrid bonding across wafer and large-panel formats up to substantial panel sizes. ( https://www.toray-eng.com/)
-
Palomar Technologies (Carlsbad, CA, USA) — 3880-II Die Bonder series applying thermocompression processes for ultra-precise applications in medical devices and photonics. ( https://www.palomartechnologies.com/)
These vendors illustrate distinct go-to-market approaches: platform breadth and field volume, high-precision niche offerings, and large-panel capability. In the full study we map supplier strengths against key procurement criteria (precision, throughput, regulatory readiness, upgrade path, total cost of ownership), enabling an apples-to-apples shortlist for different buyer archetypes.
Market structure and implications for partnerships and M&A
Market concentration indicators show the top-tier incumbents control a majority share of the addressable market. That dynamic creates both barriers and opportunities: suppliers seeking to scale may find M&A or partnership the fastest route to augment capability stacks, while buyers may seek bundled procurement deals to secure preferential lead times and pricing. For private equity and strategic acquirers, the TCB sector presents consolidation potential — particularly in automation, in-line inspection, and aftermarket services where scale drives margin expansion.
What the full PW Consulting report delivers (high-level)
Our full TCB Bonder Market study goes beyond headline forecasts to provide hands-on tools for decision-making. Highlights include:
-
Detailed market sizing and scenario-based financial models (baseline, upside, downside) covering 2026–2032, with sensitivity levers for cycle time, yield improvement, and pricing pressure.
-
Supplier benchmarking matrices and vendor scorecards that evaluate performance across technical, commercial, and service dimensions — calibrated for medical, HVM consumer, and specialty photonics use cases.
-
Purchase-and-qualification playbooks: step-by-step templates for RFQs, factory acceptance testing (FAT) criteria, and change-control protocols for regulated environments.
-
Capital allocation frameworks that translate market growth and lead-time risk into CAPEX phasing options and ROI timeframes suitable for CFO-level decision making.
-
Operational ramp plans including spare-parts forecasting, yield-debugging sequences, and workforce skilling pathways to minimize time-to-volume.
Note: the granular regional and application splits, as well as sensitive vendor performance scores, are intentionally omitted from this preview. The full datasets and appendices are available to subscribers and advisory clients, and are essential for transaction-level or plant-level decisions.
Actionable recommendations for 2026 (prioritized)
-
Re-evaluate CAPEX timing now: Given the high growth trajectory, organizations should model a near-term tranche of procurement to secure capacity while preserving optionality for subsequent upgrades.
-
Lock in regulatory-ready vendors where medical exposure exists: If your roadmap includes regulated device launches, prioritize suppliers with documented medical-device qualifications and material traceability workflows.
-
Negotiate service and spare-part commitments up-front: Service availability and spares can become strategic chokepoints in periods of demand growth; multi-year SLAs and consignment strategies mitigate risk.
-
Pilot hybrid/large-panel workflows early: Conduct focused pilots with vendors that support hybrid bonding and larger panel sizes to validate process windows before full-scale investment.
-
Design for modularity: Favor platforms that enable staged automation and feature upgrades to spread CAPEX and align with evolving product roadmaps.
Signals to monitor through 2026
-
Supplier lead-time movements and backorder levels — early indicators of capacity tightness.
-
Field yield trends for early hybrid bonding deployments — yielding improvements materially affect unit economics.
-
Regulatory guidance updates for medical manufacturing — any tightening will increase qualification cost and schedule risk.
-
Announcements of strategic partnerships or M&A among equipment suppliers — these can rapidly shift bargaining dynamics.
Each of the above signals is incorporated into our scenario models and vendor risk matrices in the full report; these tools translate observed signals into quantified impacts on margin, time-to-volume, and product launch schedules.
Closing — why access the full study
2026 is a pivot year. The macro growth profile, concentrated supplier base, and the rising regulatory and technical demands together create both outsized opportunity and asymmetric risk. PW Consulting’s TCB Bonder Market study is designed to convert market-level forecasts into operational and financial decisions: from supplier selection and CAPEX phasing to regulatory qualification strategy and M&A screening.
If your 2026 plan includes investments in thermocompression bonding capability — whether to support advanced packaging, medical devices, or photonics — the full report supplies the granular segmentation, vendor scorecards, and scenario-playbook required to act with conviction. Contact PW Consulting or visit our TCB Bonder Market page to access the complete analysis, datasets, and client-only decision tools.
For detailed analysis of this topic, please visit the official page: TCB Bonder Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Underlayment Market to Reach USD 1,935.6M in 2025 at 4.8% CAGR
By pmarketresearch, 2026-07-23
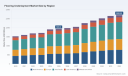
Flooring Underlayment Market — Strategic Outlook for 2026 Decision-Makers
Executive overview
As PW Consulting’s senior industry analyst, I present a focused strategic primer to orient executive teams, corporate development groups, and portfolio managers preparing for a critical planning window in 2026. Our new market study uses 2025 as the base year and traces historical performance from 2020–2025, then projects out across 2026–2032. The global flooring underlayment market—measured in USD Million—has expanded steadily since 2020 and, based on our modeling, is expected to continue growing at a compound annual growth rate (CAGR) of approximately 4.8% through 2032.
Flooring Underlayment Market
This briefing highlights why this research matters now, where structural growth and risk converge, and how the report’s practical modules equip leaders to make informed capital, product, and commercial decisions in 2026. In keeping with our “trailer” approach, we signal analytical depth while reserving the full granular tables and interactive models for the full report.
Flooring Underlayment Market
Why this research matters for 2026 planning
- Reliable macro trajectory: After pandemic-era dislocations, the underlayment market regained momentum through 2023–2025. By the 2026 planning cycle, companies need clarity on sustainable demand drivers versus transient surges. Our base-year benchmarking and 2026–2032 forecast provide that macro view.
- Cost and input risk are front and center: Polyethylene foam—the primary feedstock for the largest underlayment type—links industry margins directly to crude oil and refinery cycles. Procurement, hedging, and product re-specification are strategic levers that will shape 2026 P&Ls.
- Warranty and standards shape product design: Resilient flooring manufacturers enforce strict installation tolerances (e.g., maximum cumulative underlayment thickness constraints). Product innovation must balance acoustic/moisture performance with dimensional limits to avoid voided warranties—an operational detail with immediate commercial implications.
- Margin pressure from logistics and trade: Tariff volatility and transport surcharges for imported foams, rubber, and cork have introduced a new layer of cost unpredictability. Executives must plan sourcing and regional footprint adjustments in response.
What our full report delivers (practical, actionable modules)
The study is designed as an operating manual for decision-makers, not just a descriptive market summary. Key actionable elements include:
Flooring Underlayment Market
- Forward-looking demand scenarios (base, upside, downside) for 2026–2032 with sensitivity to energy price shocks, trade disruptions, and durable-goods substitution trends.
- Detailed cost-stack modeling that isolates raw material, conversion, freight, and tariff impacts—enabling rapid re-pricing and margin simulation for alternative formulations.
- Go-to-market playbooks for OEMs, private-label manufacturers, and specialty suppliers—covering channel priorities, specification strategies, and installer economics.
- M&A and partnership scorecards: vintage multiples, strategic fit matrices, and integration risk checklists tailored to underlayment assets and adjacent capabilities (acoustics, moisture mitigation, recycled-material processing).
- Operational playbooks for capacity planning and CAPEX timing—anchored to supply normalization scenarios and the sector’s evolving recycling ecosystem.
- Regulatory and warranty compliance matrix with design thresholds that protect OEM warranties while maximizing product differentiation.
Competitive landscape — who matters and why
The market structure displays a moderate concentration: the top three players account for a meaningful share of market capacity, with the top five representing a larger consolidated footprint. This balance creates opportunities for both scale-driven incumbents and technically nimble challengers.
- MP Global Products — Known for acoustic fiber underlayments (QuietWalk brand) and an early mover in integrating recycled content. Their value proposition emphasizes acoustic performance, moisture protection, and sustainability—attributes resonating with both renovation and multi-family residential demand.
- Leggett & Platt Flooring Products — The largest U.S. player in carpet cushion and hard-surface underlayment. Their scale and formulation breadth (foam, rubber, others) give them cost and channel advantages, particularly in private-label supply to major flooring brands.
- Pak-Lite, Inc. — A dominant private-label specialist for floating floors, with deep capabilities in bespoke performance ratings (IIC/STC/Delta). Their bespoke focus makes them a preferred supplier for retailers and OEMs seeking specification control without heavy capex.
- Wise Flooring Products LLC — A U.S.-made, recyclable-product differentiator targeting sustainability-conscious channels. They illustrate how “Made-in” positioning and circular-material messaging can command premium placements in specified projects.
- FloorMuffler — Offers a blended portfolio (XLPP foam, recycled-fiber, rubber) with product lines addressing acoustic and moisture concerns for vinyl, laminate, and hardwood—an example of product-line breadth supporting diverse retail and installer channels.
- Cyg Tefa and other Asia-based suppliers — Represent high-density IXPE/XPE foam capabilities, cost-competitive manufacturing, and strong LVP/laminate alignment. Their trade exposure amplifies sensitivity to tariffs and freight congestion trends.
- Chinese and regional manufacturers — Several professional manufacturers expand capacity and product types to serve global OEMs and private-label partners; competitive dynamics will hinge on quality certification, logistics economics, and the ability to meet warranty-sensitive specs.
Recent industry moves underscore strategic priorities for 2026:
- New product introductions (e.g., premium acoustic solutions with enhanced stability and moisture protection) signal a push toward higher-value underlayments that address end-user comfort and lifecycle performance.
- Promotions highlighting recycled materials reflect growing buyer willingness to trade cost for sustainability credentials—especially in B2B specification channels and commercial projects.
- Regional product showcases and trade participation indicate continued demand growth in emerging LVP and laminate markets, but also point to distribution gaps that incumbents can exploit.
Market dynamics that will drive boardroom moves in 2026
- Raw material volatility: Polyethylene foam pricing remains the single largest input risk; it is correlated to crude oil cycles and refinery capacity. Companies should stress-test margins against oil-price scenarios and consider strategic inventory, alternative feedstocks, or long-term purchasing arrangements.
- Regulatory and technical constraints: Flooring system warranties impose practical limits (e.g., cumulative thickness tolerances). Product development must prioritize thin-profile high-performance solutions to avoid disqualification from major floorcovering warranties.
- Transport and tariff pressure: Escalating import surcharges for foam, rubber, and cork mean regional sourcing and nearshoring strategies can materially affect landed costs and service levels.
- Recycling and supply normalization: The post-2023 stabilization of recycled rubber and natural cork supplies has enabled selective capacity investments. Suppliers that lock-in circular-material feedstocks gain both ESG credentials and a buffer against petrochemical swings.
- Installation economics: Labor and moisture mitigation requirements alter the total installed cost. Manufacturers that simplify installation or partner with installer networks can win specification share even at modest price premiums.
Strategic moves we recommend for 2026
- Prioritize product sets that combine thin profiles, acoustic performance, and moisture mitigation—this triad addresses warranty constraints while matching buyer preferences in residential and commercial refurbishments.
- Adopt a mixed sourcing model: combine regional manufacturing for warranty-sensitive, high-service customers with offshore cost advantages for commoditized SKUs. Use tariff-pass-through frameworks in contracts to reduce margin shock.
- Invest selectively in recycled-material lines where procurement can secure feedstock at scale; these products support differentiated pricing and improve resilience against petrochemical swings.
- Build installer-aligned value propositions—training, bundled moisture systems, and labor-saving product formats—to lower total installed cost and accelerate spec acceptance among flooring contractors.
- Use our scenario-based valuation templates to evaluate M&A targets: prioritize manufacturing assets with quality certifications and incumbent customer lists rather than pure capacity plays vulnerable to margin compression.
How to use the full PW Consulting study
The complete report provides the raw and modeled data—annual market totals, supply-demand balances, cost curves, and heat-mapped opportunity zones—that underpin the recommendations summarized above. If you are preparing 2026 budgets, a product roadmap, or evaluating acquisition targets, the study equips you to:
- Quickly quantify the revenue and margin impact of alternative sourcing and product strategies under multiple macro scenarios.
- Compare competitive positioning across formulation, channel, and geographic axes without re-building industry models in-house.
- Prioritize R&D and CAPEX to align with warranty-driven product specs and installer economics that will determine share shifts through 2028–2030.
Closing — the strategic moment
The flooring underlayment market has entered a phase where product-level engineering, supply-chain agility, and installer economics will determine winners more than scale alone. With a 2025 base and an explicit 2026–2032 forecast horizon at ~4.8% CAGR, executives have an opportunity in 2026 to lock in advantaged positions—whether through targeted product innovation, tactical nearshoring, or acquisition of specification-focused assets.
PW Consulting’s full study contains the data tables, regional demand matrices, and playbooks required to convert the strategic imperatives outlined here into executable plans. For access to the complete dataset, segment breakdowns, and downloadable modeling tools, please consult the full report on our website.
For detailed analysis of this topic, please visit the official page: Flooring Underlayment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Plating Equipment Market to Hit USD 279.35M by 2032 at 6.5% CAGR
By pmarketresearch, 2026-07-23
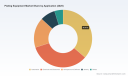
Plating Equipment Market — Strategic Preview for 2026 Decision‑Making
As PW Consulting’s senior strategy team, we present a concise, decision‑focused preview of our full Plating Equipment Market study. This brief is designed as a strategic trailer: it delivers rigorous, data‑grounded context and clear implications for 2026 capital, product and supply‑chain choices — while intentionally withholding granular segment-level tables and region/application breakdowns to preserve the commercial value of the full report.
Plating Equipment Market
Market snapshot: the macro trajectory
The plating equipment market has demonstrated steady expansion through the 2020–2025 historical window and is projected to continue this momentum across our 2026–2032 forecast horizon. On a consolidated basis (USD, revenue unit: Million), the market reached a notable scale in the base year (2025) and expands at a compound annual growth rate of roughly 6.5% across the forecast period. By 2032 the market is materially larger than in 2025, reflecting a combination of demand tailwinds from electronics, automotive electrification, and industrial refurbishment, together with technology replacement cycles and regulatory-driven retrofit spending.
Plating Equipment Market
Two structural metrics matter for strategy formation: (1) market concentration is moderate — the top three players account for under one third of the market while the top five approach four tenths — indicating meaningful room for regional specialists, technology‑led entrants and M&A to reshape shares; and (2) growth is broad‑based but unevenly driven by distinct end‑markets and technology adoption curves (which we analyze in the full study).
Plating Equipment Market
Near‑term drivers and 2026 strategic imperatives
-
CapEx timing and phasing: For executive teams planning mid‑cycle capacity investments in 2026, the confluence of steady demand growth and accelerating regulatory compliance costs argues for staged capital deployment. Targeted upgrades that prioritize wastewater treatment and closed‑loop chemistries reduce long‑term OPEX and limit regulatory exposure — especially where effluent rules have recently tightened.
-
Supply‑chain and raw material risk management: Elevated copper and specialty metal prices, combined with evolving export controls on strategic inputs, are compressing margins and increasing lead‑time volatility for plating line components. Buyers should build dual‑sourcing strategies, consider nearshoring critical assemblies, and lock in strategic hedges on key commodities to reduce price‑sensitivity in 2026 budgets.
-
Automation to mitigate labor constraints: Labor shortages and rising labor costs in finishing operations are driving a rapid shift toward robotic integration, modular automated lines and remote process control. Investment in automation not only reduces operating costs but also improves process repeatability and environmental compliance — a clear priority for high‑mix, low‑volume customers such as aerospace and luxury jewelry manufacturers.
-
Regulatory and sustainability compliance as product enablers: New effluent and emissions standards are creating both a compliance burden and a commercial opportunity. Vendors who can package low‑waste chemistries, efficient wastewater management and compliance service offerings into turnkey solutions will win faster adoption and command premium positioning.
-
Technology differentiation and aftermarket services: Incremental equipment performance improvements — e.g., advanced agitation systems, process sensors, and selective/brush plating innovations — are increasingly monetized through service contracts, spare parts and consumable supply agreements. Companies that align equipment roadmaps with long‑duration service revenue models will enhance lifetime value.
Competitive landscape — patterns and strategic postures
The competitive field features established chemical/equipment integrators, specialist equipment OEMs and a network of regional system integrators. Key players profiled in our research illustrate three dominant archetypes:
-
Integrated chemistry + equipment leaders (platform plays): Firms that combine plating chemistries with turnkey equipment and process know‑how are positioned to capture higher margins through system solutions and recurring chemical supply. These incumbents leverage R&D in low‑waste chemistries and cross‑industry packaging to penetrate adjacent applications.
-
Specialist OEMs focused on selective & on‑site systems: Companies that dominate brush and selective plating systems serve aftermarket repair and niche industrial use cases. Their strength lies in portability, responsiveness and application know‑how — making them attractive partners for MRO networks and service‑led business models.
-
Turnkey integrators and automation vendors: Providers specializing in automated lines, conveyors and tailored finishing suites win in high‑volume, high‑automation customer segments. Their competitive advantage is delivering predictable throughput, regulatory compliance and integration with MES/Industry 4.0 stacks.
Recent vendor activity points to how competition will unfold in 2026. Suppliers are emphasizing sustainable chemistries and packaging at trade events, and the market is witnessing product innovations (e.g., new barrel geometries and modular line components) aimed at improving yield and reducing waste. These moves indicate an industry pivot where new product introductions are as much about environmental performance and serviceability as about nominal throughput gains.
What the full PW Consulting report delivers (practical, operational content)
Our comprehensive study is organized to serve decision‑makers tasked with investment approvals, procurement strategy and business development. The deliverables include:
- Macro sizing and detailed forecasts (historical 2020–2025, baseline 2025, and 2026–2032 scenarios) with sensitivity analysis under alternative demand and commodity price shocks.
- Scenario planning templates for CapEx phasing and ROI under regulatory tightening and raw material inflation assumptions.
- Technology roadmaps and adoption curves, showing where automation, selective plating and low‑waste chemistries intersect with key end markets.
- Go‑to‑market playbooks for OEMs and systems integrators — including pricing strategies, bundling approaches for equipment + chemistry + service and recommended channel models.
- M&A and partnership decision frameworks, with valuation multipliers, integration risk checklists and target screening criteria tailored to both regional consolidators and capability buyers.
- Procurement and supplier resilience playbooks: dual‑sourcing templates, vendor scorecards and inventory/consumption models to mitigate commodity exposure.
- Compliance checklists and implementation roadmaps for wastewater and emissions management aligned to new regulatory baselines.
How leading companies are positioning (high‑level profiles)
-
Atotech (Berlin): A platform player integrating plating chemistries with turnkey equipment; active in advanced PCB/packaging and sustainable surface finishing. Recent trade show activity underscores their emphasis on integrated solutions for electronics and automotive supply chains.
-
Technic Inc. (Cranston, RI): Known for specialty chemistry and brush systems; strong in selective electroplating and industrial decorative applications. Their product breadth supports both in‑line and repair‑oriented use cases.
-
SIFCO ASC (Cleveland, OH): Specialist in on‑site brush plating and repair systems, serving aerospace and heavy industry segments where field repair capability is mission‑critical.
-
KOCH Finishing Systems (Chicago): A turnkey automation and surface finishing provider; recent product introductions highlight innovations in barrel geometries and process performance.
-
Becker Industries, Allied Plating Supplies, A Brite Company, IPT LLC: These vendors represent the ecosystem of regional suppliers, chemical and kit providers, and line integrators that feed OEMs and end users. Their proximity to customers and responsive service models are distinguishing assets.
Industry noise and systemic risks to factor into 2026 planning
- Regulatory shifts: Recent effluent limitation updates require capital and process changes for many operators — factor compliance CAPEX into 2026 budgets.
- Raw material pressure: Record highs in key anode and specialty metal prices have compressed margins; commodity hedges and supplier partnerships are essential risk mitigants.
- Geopolitical supply constraints: Export controls and trade measures affecting critical components and rare earths can create sudden sourcing constraints — scenario‑based continuity plans are advised.
- Labor and automation dynamic: Persistent labor shortages are accelerating the ROI case for automation investments that would previously have been deferred.
How to use this preview to make better decisions in 2026
- Executive teams should convert the macro growth profile and concentration metrics into a prioritized set of initiatives: immediate compliance upgrades, medium‑term automation projects, and longer‑term product/market plays.
- Procurement must adopt a two‑track approach: lock in strategic supply agreements for critical inputs now, while qualifying secondary suppliers to reduce single‑source risk.
- R&D and product leaders should align roadmaps to sustainability and service models — packaging low‑waste chemistries with remote monitoring and service contracts will be a competitive differentiator.
- Corporate development should use the moderate concentration landscape to pursue bolt‑on acquisitions that add regional market access or unique technical capabilities, rather than large transformative buys.
Closing — where this preview fits and next steps
This preview synthesizes the high‑level market trajectory, competitive archetypes and decision‑critical implications for 2026. It is intentionally focused on strategic signals rather than the granular segment tables and regional/application splits that commercial teams rely on for execution. If you are preparing 2026 budgets, vendor evaluations or an M&A shortlist, the full PW Consulting Plating Equipment Market report provides the granular segmentation, downloadable datasheets, company profiles, scenario models and implementation templates you will need.
Contact PW Consulting to access the complete study and the companion decision‑support toolkit that operationalizes these insights into executable 90‑ to 180‑day plans.
For detailed analysis of this topic, please visit the official page: Plating Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Fatigue Machine Market to Grow at 6.2% CAGR (2026–2032)
By pmarketresearch, 2026-07-23
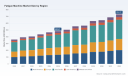
Fatigue Machine Market 2026: Strategic Preview for Corporate Decision-Makers
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present a targeted preview of our latest Fatigue Machine Market study — an executive-grade reconnaissance intended to shape capital allocation, procurement, and R&D priorities in 2026. This overview demonstrates the analytical depth of the full report while preserving the high-resolution segmentation and proprietary models that we reserve for clients and subscribers.
Fatigue Machine Market
Why this market matters in 2026
Fatigue testing equipment is a foundational enabler across industries where cyclic loading determines product safety, longevity, and certification: aerospace structures, automotive durability programs, additive manufacturing qualification, medical-device verification, and materials R&D. After a steady recovery through the early 2020s, the global fatigue machine market reached a meaningful inflection by our 2025 base year and is set to expand through the forecast horizon. Our blended market model, calibrated to historical performance and near-term indicators, shows mid-single-digit compound annual growth (CAGR of 6.2%) across the 2026–2032 interval. That growth reflects a combination of rising test program intensity, regulatory tightening, and technology migration toward higher-throughput, digitally instrumented test systems.
Fatigue Machine Market
High-level market dynamics
- Growth trajectory : From the post-2020 recovery into 2025, unit and spend momentum were driven by renewed capital programs and higher testing volumes tied to electrification, lightweighting, and additive manufacturing validation. Our forecast carries that momentum through 2032, with the market expanding materially from the 2025 baseline to a substantially larger addressable spend by the end of the period.
- Concentration : The sector shows moderate concentration: the top three vendors account for under half of market revenues, and the top five approach half the market. This structure rewards organizations that combine product breadth with global service footprints but still leaves meaningful space for regional and niche specialists.
- Margin pressure and operational scale : Input-cost volatility and competitive pricing pressure persist as structural headwinds. Manufacturers with integrated supply chains and scale economies — who can also invest in digital services and aftermarket support — are better positioned to defend margins.
- Regulatory and standards tailwinds : Evolving procurement requirements and standards are directing buyers toward certified, specification-compliant fatigue testing systems. Events such as ASTM symposia and sector-specific guidance (including recent handbook updates addressing additive-manufactured parts) are reshaping qualification workflows and raising minimum technical requirements for test platforms.
Key demand drivers in 2026
- Electrification and composite adoption : New powertrain systems and composite-structured components increase the complexity of fatigue programs — demanding multi-axis, higher-capacity, and thermal-cycling capable machines.
- Additive manufacturing validation : Guidance documents and qualification frameworks for printed parts are expanding fatigue testing requirements, from coupon-level characterization to component-scale durability tests.
- R&D intensity and time-to-certification pressure : Accelerated product development cycles are prompting investments in automated, high-throughput fatigue cells and integrated data platforms to shorten iteration times.
- Service and lifetime testing : OEMs and Tier-1 suppliers increasingly outsource or co-invest in specialized test programs, favoring vendors that bundle predictive analytics, sensor suites, and long-term maintenance contracts.
Technology shifts to watch
- Actuation diversity : Servo-hydraulic, electrodynamic, linear motor, and electromagnetic actuation technologies continue to coexist, with selection driven by frequency range, load capacity, and test fidelity requirements. Hybrid systems and modularity are emerging as differentiators for organizations balancing flexibility and capital efficiency.
- Sensor and data integration : Advances in high-fidelity sensors and real-time analytics — highlighted at recent industry symposia — are increasing the value of test programs beyond pass/fail outcomes, enabling predictive maintenance and materials modeling.
- Automation and cell orchestration : Biaxial and multi-axis systems, combined with automated specimen handling and integrated environmental chambers, are becoming table stakes for high-throughput labs, especially in EV and aerospace supply chains.
Competitive landscape — what the full report reveals
Our competitive assessment centers on established global vendors and regional challengers. The full study contains detailed capability maps, go-to-market playbooks, and supplier scorecards; below we summarize strategic positions without disclosing proprietary benchmarking scores.
Fatigue Machine Market
- MTS Systems Corporation — A long-standing leader known for servohydraulic and electrodynamic platforms across high-cycle and thermo-mechanical applications. Its strength lies in integrated system packages and deep vertical credentials in aerospace and automotive testing programs.
- ADMET, Inc. — Focused on modular and standards-compliant solutions, ADMET positions itself for labs that require flexible configurations for ASTM/ISO-aligned fatigue regimes and calibration services.
- ZwickRoell Group — A European innovator with a growing emphasis on automated and biaxial systems tailored to composites and high-capacity applications. Recent product introductions underscore an intent to capture advanced EV and battery-structure testing work.
- Instron — Offers a broad portfolio spanning servohydraulic, servo-electric, and linear motor-driven machines. Its integrated software and digital services make it attractive to customers seeking end-to-end test-data workflows.
- Shimadzu Corporation — Combines hydraulic and electromagnetic machines with servopulser capabilities, supporting quick-cycle durability testing and sudden-load simulations.
- Chinese OEMs (Testron, Laryee, Shanghai Bairoe) — These vendors provide cost-competitive servo-hydraulic and electronic systems with increasingly capable sensors and localized service. Their presence is most pronounced in price-sensitive segments and regional lab networks.
Recent vendor activity validates these dynamics: MTS showcased solutions at a major mobility tradeshow in 2025; ZwickRoell launched a next-generation biaxial system targeting EV battery composites in early 2026; and General Atomics completed an unprecedented long-duration aircraft fatigue campaign, illustrating the scale and complexity of contemporary test programs. Meanwhile, ASTM’s symposia continue to spotlight sensor and measurement advances that will be embedded into the next generation of fatigue fixtures and instrumentation.
How PW Consulting’s research helps corporate decision-makers in 2026
Our full Fatigue Machine Market report is designed as a decision-support toolkit for three principal audiences: equipment OEMs, corporate procurement and test-lab managers, and investors evaluating supply-chain plays. We translate market intelligence into immediate actions and risk mitigations.
- For OEMs and product leaders : We provide a prioritized technology roadmap, supplier benchmarking, and modularity strategies that clarify where to invest in R&D versus partnership. Our analysis highlights which actuation and sensing combinations will command price premiums and service stickiness.
- For procurement and test-lab managers : We deliver checklists for specification alignment with evolving standards, lifecycle cost models, and outsourcing vs. insourcing decision frameworks. These tools help lock in procurement terms that minimize total cost of ownership while ensuring compliance with tightening regulatory criteria.
- For investors and corporate strategy : We present a competitive playbook and M&A heat map, identifying the types of capabilities that generate defensible margins — from service contracts and digital analytics to multi-axis automation and thermal cycling cells.
Report contents — practical, operational, and actionable
The complete PW Consulting report includes:
- Market sizing and calibrated forecast model for 2026–2032 with sensitivity scenarios and downside/upside drivers.
- Commercial and technological segmentation analysis (frequency classes, actuation types, applications and regional demand patterns) with downloadable data tables and scenario-specific revenue splits.
- Vendor benchmarking covering product portfolios, service footprints, pricing bands, go-to-market motions, and risk exposure (supply chain, input-cost sensitivity).
- Procurement playbook and specimen-level specification templates aligned to current ASTM/ISO/NASA guidance.
- Case studies documenting recent complex test programs, including multi-year aerospace and unmanned platform programs.
- Strategic recommendations and a two-year implementation roadmap for suppliers and test labs looking to optimize for 2026 commercial cycles.
Importantly, while this preview communicates key implications and strategic pathways, the granular segmentation splits and the underlying financial model are intentionally omitted here to preserve client advantage. These deliverables are included in the full report and accompanied by an interactive model workbook and proprietary scoring rubric.
What to do next — three immediate actions for leaders in 2026
- Audit your test-capability roadmap : Re-evaluate whether your current portfolio (actuation range, environmental control, data capture) aligns with foreseeable standards-driven requirements and customer qualification timelines.
- Negotiate service-first procurement : Shift contract terms toward outcome-linked service agreements and data-platform access, which protect against price competition and provide recurring revenue opportunities for suppliers.
- Prioritize sensor and data integration : Invest in higher-fidelity instrumentation and analytics that deliver predictive insights; this increases test-program value and can shorten certification cycles.
Closing perspective
The fatigue machine market in 2026 is not just a hardware story; it is a systems and data story where testing platforms are extensions of product development, certification, and quality assurance ecosystems. Companies that rethink test capabilities as a strategic asset — coupling modular hardware with sensor-rich telemetry and lifecycle service models — will capture disproportionate value. PW Consulting’s full Fatigue Machine Market study equips leaders with the granular, operational intelligence needed to execute those moves, from procurement specifications to M&A screening.
For executives, program managers, and investors ready to convert insight into action, the comprehensive report includes the models, supplier scorecards, and implementation templates required to make defensible, high-impact decisions in 2026. Access to the full dataset and the interactive forecast model is available on our report page.
For detailed analysis of this topic, please visit the official page: Fatigue Machine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Automotive Door Handles Market to hit USD 5,334.6M by 2032 (4.5% CAGR)
By pmarketresearch, 2026-07-23
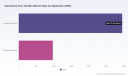
Automotive Door Handles Market — Strategic Outlook for 2026 Decision Makers
As original equipment manufacturers (OEMs), Tier‑1 suppliers and private equity investors set budgets and product roadmaps for 2026, the modest-looking door handle is emerging as a focal point for competitive differentiation, compliance risk and cost pressure. PW Consulting’s latest market study shows the global automotive door handles market reached approximately USD 3.94 billion in 2025 (base year) and is projected to expand at a compound annual growth rate (CAGR) of 4.5% through the 2026–2032 forecast window, reaching roughly USD 5.33 billion by 2032. This paper summarizes the strategic implications of those macro trends and previews the operational playbook contained in our full report — sufficient to inform boardroom debate, but intentionally withholding granular splits and segment tables to encourage direct access to the complete dataset and models.
Automotive Door Handles Market
Why this research matters for 2026 decisions
-
Product architecture is in flux. The interplay between minimalistic exterior design, aerodynamic regulation, and advanced access systems (keyless, facial, and mobile) forces suppliers and OEMs to choose between proven mechanical designs, hybrid mechanical-electronic solutions, and fully integrated mechatronic modules.
Automotive Door Handles Market -
Regulation is a near-term design driver. Upcoming mandates will materially affect mechanical design requirements, testing regimes and qualification timelines — with one prominent market moving to require manual release hardware on electronic door handles from January 1, 2027. That pivot creates rework risk for programs scheduled for launch in 2026–2027 and makes early compliance planning imperative.
Automotive Door Handles Market -
Manufacturing complexity is rising. The broader move to flush-mounted and sensor‑integrated handles increases reliance on precision molding, specialized surface coatings and multi‑material assemblies. Suppliers that have mastered these capabilities gain both margin and specification control.
-
Sustainability and ESG are procurement gates. New OEM qualification requirements around lifecycle carbon, recyclable materials, and supplier traceability are filtering out non‑compliant vendors; procurement teams must embed ESG metrics in supplier scorecards before 2026 contract rounds.
What the PW Consulting report delivers — practical, actionable content
-
Executive synthesis: concise strategic scenarios (base case, regulatory shock, accelerated EV adoption) that map to P&L and program schedules for 2026–2028.
-
Macro market sizing and trajectory: a validated historical series (2020–2025) and a transparent forecasting model (2026–2032) with sensitivity toggles for fuel price, EV penetration and regulatory cost adders.
-
Technology and design roadmaps: comparative assessment of mechanical, hybrid and mechatronic architectures highlighting cost, NVH, manufacturability, and IP exposure for each path.
-
Supply chain and cost breakdowns: bill‑of‑materials (BOM) templates, labor and overhead benchmarks, and scenario-based cost pressure analysis (including specialized coatings and tooling for flush‑mounted solutions).
-
Regulatory compliance playbook: test plans, qualification timelines, and design checklists tied to jurisdictional requirements — including emergency release hardware and OEM qualification changes.
-
Competitive benchmarking: qualitative and tactical profiles of the major suppliers, their channel footprints, core capabilities and likely strategic moves through 2027.
-
M&A and partnership guide: deal typologies (capability tuck‑ins vs scale consolidation), valuation sensitivities and integration checklists specific to door handle assets and mechatronic subsystems.
-
Commercial negotiation templates: risk sharing clauses, warranty frameworks and co‑investment structures that reconcile program timing and tooling cost allocations with OEM launch cadence.
Competitive landscape — companies and strategic signals
The market is characterized by a mix of global Tier‑1 integrators, specialist component manufacturers and nimble regional players. The competitive field is concentrated enough that top vendors exert price and specification influence, yet fragmentation at the module and regional supplier tiers creates room for targeted entry and consolidation plays.
-
Huf Hulsbeck & Fürst GmbH & Co. KG (Velbert, Germany) — The incumbent leader. Huf’s full spectrum of rotational, parallel deployable and flush solutions, combined with embedded passive entry sensors and mechatronics, positions it to lead integrated access system programs. Recent strategic partnerships to shore up supply chain and innovation strengths indicate a platform play: buyers should expect Huf to push for module‑level specs and longer contractual commitments.
-
Magna International Inc. (Aurora, Canada) — A systems integrator that bundles mechanical and electronic door handle functions into broader door modules. Magna’s SmartAccess demonstrations underscore its push to move beyond parts supply toward software and actuator subsystems. OEMs seeking single‑vendor module accountability will continue to find Magna attractive.
-
Kiekert AG (Heiligenhaus, Germany) — Specialist in locking systems and power closing actuators. Kiekert’s mechatronic portfolio supports improved access comfort and safety — a valuable plug‑in for suppliers lacking locking or actuation expertise.
-
Aisin Seiki Co., Ltd. (Kariya, Japan) — Supplier with deep OEM relationships and proven keyless entry and closure modules. Aisin’s strong integration with major Japanese OEMs makes it a strategic partner for programs prioritizing durability and just‑in‑time supply models.
-
U‑Shin Ltd. (Tokyo, Japan) — Known for flush designs and a strong presence in Asian OEM supply chains. U‑Shin’s mix of outside/inside handles and locksets provides a lower‑risk path for programs focused on regional platforms.
-
WITTE Automotive GmbH (Velbert, Germany) — Exterior handle specialist. WITTE’s recent concept collaboration that integrated facial authentication and automatic opening without a traditional handle signals a forward‑looking product strategy aimed at OEMs pursuing minimalist exteriors and premium access UX.
-
Minda VAST Access Systems Pvt. Ltd. (Pune, India) — A regional player specializing in cost‑competitive access systems with a growing export footprint. For OEMs targeting emerging markets, partners like Minda VAST provide an important balance of cost, localization and security features.
Recent developments: tactical implications
-
WITTE’s concept car collaboration demonstrates how sensor fusion (biometrics) can be used to remove conventional handle geometry. While design‑forward, such approaches face regulatory and aftermarket repairability questions; OEMs must weigh design premium vs. serviceability and retrofit costs.
-
Huf’s strategic partnership to strengthen supply chain resilience is emblematic of a broader industry response: suppliers are consolidating toolrooms, sharing innovation platforms and co‑investing in qualification assets to shorten time‑to‑market and de‑risk program launches.
-
Magna’s public showcases of SmartAccess modules are a reminder that module‑level competition is intensifying. Suppliers that can offer validated mechatronic stacks (mechanics, electronics, actuators, software) will command higher program margins and longer OEM engagement cycles.
-
Regulatory moves — especially those that mandate mechanical release or restrict fully hidden/electronic‑only handles — create a timing window in 2026 to redesign vehicle programs and align production tooling. Delays in response will translate directly to cost overruns and potential non‑compliance penalties.
Strategic choices for executives in 2026
-
Immediate (0–9 months): run scenario planning for regulatory shocks, reforecast 2026 CAPEX for tool rework, and initiate supplier ESG audits tied to upcoming OEM qualification rounds. Where programs touch jurisdictions with new mandates, accelerate design freeze milestones or budget contingency for mechanical release additions.
-
Near term (9–24 months): prioritize qualification of at least one secondary supplier for critical mechatronic components, and form targeted partnerships with sensor and coating specialists. Revisit BOMs to identify high‑impact cost drivers — coatings, multi‑material assemblies and electronics — and pursue design‑to‑cost exercises with preferred suppliers.
-
Strategic (24+ months): consider M&A to secure missing capabilities (locking systems, actuation, biometric authentication), or pursue exclusive module agreements with integrated players to lock in specs and margins. Build a sustainability roadmap that maps material substitutions and carbon accounting to supplier scorecards.
How PW Consulting supports your 2026 agenda
Our full study provides the data, templates and decision tools procurement, product and corporate development teams need to execute the choices above. Deliverables include a downloadable forecasting model, supplier heatmaps, BOM benchmarking, regulatory compliance matrices by jurisdiction, and a deal‑structuring playbook for supplier consolidation. We also offer tailored advisory packages: rapid compliance audits, supplier due diligence for M&A, and implementation support for cross‑functional product launches.
This article is a strategic preview. For the granular regional, type and application breakdowns, scenario sensitivity tables, and supplier scorecards that underpin these recommendations, please visit the PW Consulting research portal to access the full Automotive Door Handles Market report and the accompanying data pack.
For detailed analysis of this topic, please visit the official page: Automotive Door Handles Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com