

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Cabin Air Quality Sensors to hit USD 4.24B by 2032 at 6.98% CAGR

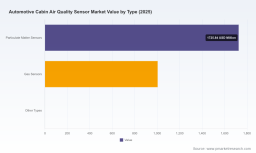
Automotive Cabin Air Quality Sensor Market: Strategic Preview for 2026 Decision Makers
As global mobility pivots toward electrification, connectivity and occupant-centric design, cabin air quality (CAQ) sensing has moved from a niche comfort feature to a strategic vehicle subsystem. This preview synthesizes the core strategic implications of PW Consulting’s comprehensive Automotive Cabin Air Quality Sensor Market study — published with a 2025 base year and a 2026–2032 forecast horizon — and explains why our findings should shape procurement, product development and partnership choices made in 2026. The full report delivers the underlying datasets, supplier scorecards and scenario-specific recommendations; here we surface the directional insights and the decision levers executives cannot afford to ignore.
Automotive Cabin Air Quality Sensor Market
Market snapshot: a clear growth runway
Our market model shows a sustained growth trajectory for cabin air quality sensing, reflecting widening regulatory pressure, rising consumer health awareness and increasing sensor content per vehicle — especially in electrified and premium segments. Using 2025 as the base year, the global market is modeled across 2020–2032 and forecasts a compound annual growth rate (CAGR) of 6.98% through the 2026–2032 period. By 2032 the market is projected to be noticeably larger than in 2025, presenting clear revenue expansion opportunities for system suppliers, OEMs and tier-one integrators that move early.
Automotive Cabin Air Quality Sensor Market
Why 2026 is a pivotal year for corporate strategy
- Regulatory inflection points: With the EU enforcing in‑cabin air quality standards since 2024 and multiple technical bodies publishing real‑world measurement and adaptive control standards in 2026, compliance timelines and testing protocols are converging. Companies must assume more stringent product validation and reporting requirements in upcoming vehicle homologation cycles.
- Technology convergence: CAQ sensing is no longer a one-dimensional PM sensor story. Multi‑parameter modules (PM, VOCs, CO2/equivalents, formaldehyde proxies) connected to adaptive HVAC and AI analytics are becoming the platform standard for OEMs seeking differentiated occupant health propositions.
- OEM architecture decisions: Integrators must choose between sensor-as-module suppliers, platform partnerships with HVAC vendors, and in-house sensor development. Each route has different margin, IP and supply-chain exposure implications that should be resolved in 2026 procurement cycles.
- Electrified vehicle priorities: EV buyers place a premium on cabin comfort and perceived health benefits; battery electrification also changes HVAC energy budgets, making energy‑aware CAQ strategies (sensor-driven filtration and circulation) an ROI lever for vehicle range managers and feature packages.
Key dynamics shaping supplier and OEM strategies
- Standards and test methods: The appearance of SAE technical papers in 2026 addressing real‑time CAQ impacts, adaptive HVAC strategies and interior material emissions underscores that test methodologies will be standardized soon. Suppliers that align early with SAE and regulatory testbeds will reduce time-to-market friction for their OEM customers.
- Regulatory enforcement: National and regional regulations — exemplified by existing limits in some markets for interior formaldehyde — will drive baseline CAQ functionality as a compliance requirement rather than an optional comfort feature in many vehicle classes.
- Sensor performance and lifecycle: Advances in MEMS, laser-based particulate sensing and multi-parameter electrochemical/metal-oxide gas sensing are improving accuracy and durability expectations. Suppliers that can demonstrate long-life calibration stability and low maintenance will win OEM specification slots in 2026–2027 programs.
- Data and service layer monetization: CAQ data combined with telematics and cabin occupancy sensing enables new services — predictive filter replacement, air-quality-as-a-service for shared mobility operators, or health-oriented alerts. Strategy teams must balance privacy/regulatory constraints with monetization models.
- Supply-chain resilience: Materials and sub-component sourcing remains a strategic risk. Vertical integration or multi-sourcing strategies for critical sensing elements and CO2/VOC detectors will reduce program risk for OEMs launching in the 2027–2029 model years.
Competitive landscape — what the majors are doing (high‑level)
The supplier ecosystem is composed of large multi-domain automotive suppliers, specialized sensor manufacturers and system integrators. While a number of established players compete for OEM mandates, the market remains sufficiently open for new entrants with differentiated technology or platform approaches.
Automotive Cabin Air Quality Sensor Market
- Robert Bosch GmbH (Gerlingen, Germany): Leveraging decades of automotive sensor integration and HVAC system relationships, Bosch offers advanced cabin air quality modules positioned for passenger vehicles and EVs. Their scale and OEM relationships make them a go‑to for platform-level integration.
- Denso Corporation (Tokyo, Japan): Denso is advancing VOC detection capabilities and tighter HVAC integration. Its supplier role to several global OEM programs gives it priority in specification discussions for comfort and air‑quality packages.
- Valeo (Paris, France): Valeo’s smart sensor platforms emphasize OEM integration and real‑time pollutant detection. Their recent platform announcements highlight a focus on software-enabled differentiation for fleet and fleet-service applications.
- Honeywell International Inc. (Charlotte, USA): Honeywell’s 2025 introduction of an AI-enabled sensor module for EVs signals a push into analytics-enabled filtration control and adaptive systems — positioning them at the intersection of sensor hardware and edge analytics.
- Amphenol Corporation (Wallingford, USA): Amphenol’s recent sensor series targets improved accuracy and durability for global OEMs, reinforcing their role as a reliable tier‑one supplier for volume programs.
- Hella GmbH (Lippstadt, Germany): Hella continues to supply vehicle electronics and CAQ sensors with an emphasis on integration into passenger vehicle networks and comfort subsystems.
- Sensirion AG (Stäfa, Switzerland): As a specialist in particulate matter sensing, Sensirion’s partnerships (notably a 2025 co‑development announced with an OEM group) show the strategic value of combining sensor IP with OEM system engineering.
- Cubic Sensor and Instrument Co., Ltd. (Wuhan, China): Focused on PM sensors with long-life claims, Cubic targets specific regional OEMs and cost-sensitive programs where lifecycle durability is a key procurement criterion.
Recent vendor activity through 2025 — including AI-enabled modules, strategic OEM co‑development agreements and multi‑year supplier contracts — indicates that 2026 OEM sourcing rounds will favor suppliers who can demonstrate validated system performance, regulatory test compliance and software/hardware co‑development capabilities.
Strategic levers for buyers and suppliers in 2026
- For OEMs and mobility operators: Re-evaluate CAQ sensor sourcing as part of powertrain‑agnostic feature packs. Require verification test protocols aligned to emerging SAE methods. Consider bundling CAQ data into connected services to recover unit costs while navigating privacy regulation.
- For sensor suppliers: Prioritize robust calibration strategies, long‑term drift testing and formal compliance evidence. Differentiate on integration ease (API/ECU interfaces), life‑cycle cost and co‑development support for HVAC calibration and filter optimization.
- For tier‑one integrators and software providers: Build platform propositions that combine multi‑parameter sensing with adaptive HVAC control and predictive maintenance. Demonstrate energy trade‑offs for EV range optimization tied to CAQ control strategies.
- For investors and corporate strategy teams: Target M&A or partnership activity in specialists who bring either unique sensing IP, proven OEM programs, or strong software/analytics stacks that can be embedded quickly into vehicle platforms launched 2027–2029.
What PW Consulting’s full report contains (practical components)
Our in‑depth study is designed as an executional playbook for 2026 decisions. Key deliverables include:
- Granular market model (historical 2020–2025 / forecast 2026–2032) with scenario variants keyed to regulatory tightening and EV adoption curves.
- Technology roadmap outlining sensor modalities (PM, VOCs, CO2 proxies, formaldehyde indicators), expected cost and performance trajectories, and integration timelines.
- Regulatory and standards mapping with timing implications for homologation and OEM procurement windows.
- Supplier benchmarking and scorecards covering product breadth, system integration capabilities, software assets and program wins.
- Use‑case playbooks for passenger cars, commercial vehicles and shared mobility — including implementation checklists, OPEX/CAPEX tradeoff templates and data monetization options.
- Supply‑chain risk heatmaps and mitigation strategies, plus supplier shortlists for different procurement strategies (cost, performance, resilience).
- Commercial negotiation guides, sample technical specifications and test protocol alignment templates that accelerate supplier selection.
How to use these insights in 90 / 180 / 360 day plans
- 90 days: Update procurement RFQs to include multi‑parameter performance metrics and SAE-aligned test requirements; initiate pilot engagements with one hardware and one software partner.
- 180 days: Finalize supplier selections for 2027 programs, negotiate long‑lead components with secondary suppliers, and begin integration of CAQ data into vehicle telematics/UX designs.
- 360 days: Lock software/hardware co‑development milestones into program timelines, validate systems in homologation testbeds and prepare go‑to‑market packages for differentiated CAQ features.
Final thoughts — the strategic payoff
By 2026, cabin air quality sensing will be a material contributor to vehicle differentiation, regulatory compliance and new data-driven services. Firms that treat CAQ primarily as a commoditized sensor purchase will miss opportunities in software-driven differentiation, aftermarket/servicing revenue and regulatory-aligned product positioning. Conversely, suppliers and OEMs that coordinate product, software and regulatory strategies now will capture both near-term program wins and durable platform value through 2032.
PW Consulting’s full Automotive Cabin Air Quality Sensor Market report delivers the datasets, supplier insights and tactical tools required to convert this market trajectory into measurable revenue and competitive advantage. For access to the model, scorecards and actionable annexes, please visit our report page or contact your PW Consulting analyst.
For detailed analysis of this topic, please visit the official page: Automotive Cabin Air Quality Sensor Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com