

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Fatigue Machine Market to Grow at 6.2% CAGR (2026–2032)

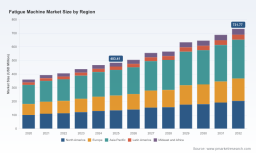
Fatigue Machine Market 2026: Strategic Preview for Corporate Decision-Makers
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present a targeted preview of our latest Fatigue Machine Market study — an executive-grade reconnaissance intended to shape capital allocation, procurement, and R&D priorities in 2026. This overview demonstrates the analytical depth of the full report while preserving the high-resolution segmentation and proprietary models that we reserve for clients and subscribers.
Fatigue Machine Market
Why this market matters in 2026
Fatigue testing equipment is a foundational enabler across industries where cyclic loading determines product safety, longevity, and certification: aerospace structures, automotive durability programs, additive manufacturing qualification, medical-device verification, and materials R&D. After a steady recovery through the early 2020s, the global fatigue machine market reached a meaningful inflection by our 2025 base year and is set to expand through the forecast horizon. Our blended market model, calibrated to historical performance and near-term indicators, shows mid-single-digit compound annual growth (CAGR of 6.2%) across the 2026–2032 interval. That growth reflects a combination of rising test program intensity, regulatory tightening, and technology migration toward higher-throughput, digitally instrumented test systems.
Fatigue Machine Market
High-level market dynamics
- Growth trajectory : From the post-2020 recovery into 2025, unit and spend momentum were driven by renewed capital programs and higher testing volumes tied to electrification, lightweighting, and additive manufacturing validation. Our forecast carries that momentum through 2032, with the market expanding materially from the 2025 baseline to a substantially larger addressable spend by the end of the period.
- Concentration : The sector shows moderate concentration: the top three vendors account for under half of market revenues, and the top five approach half the market. This structure rewards organizations that combine product breadth with global service footprints but still leaves meaningful space for regional and niche specialists.
- Margin pressure and operational scale : Input-cost volatility and competitive pricing pressure persist as structural headwinds. Manufacturers with integrated supply chains and scale economies — who can also invest in digital services and aftermarket support — are better positioned to defend margins.
- Regulatory and standards tailwinds : Evolving procurement requirements and standards are directing buyers toward certified, specification-compliant fatigue testing systems. Events such as ASTM symposia and sector-specific guidance (including recent handbook updates addressing additive-manufactured parts) are reshaping qualification workflows and raising minimum technical requirements for test platforms.
Key demand drivers in 2026
- Electrification and composite adoption : New powertrain systems and composite-structured components increase the complexity of fatigue programs — demanding multi-axis, higher-capacity, and thermal-cycling capable machines.
- Additive manufacturing validation : Guidance documents and qualification frameworks for printed parts are expanding fatigue testing requirements, from coupon-level characterization to component-scale durability tests.
- R&D intensity and time-to-certification pressure : Accelerated product development cycles are prompting investments in automated, high-throughput fatigue cells and integrated data platforms to shorten iteration times.
- Service and lifetime testing : OEMs and Tier-1 suppliers increasingly outsource or co-invest in specialized test programs, favoring vendors that bundle predictive analytics, sensor suites, and long-term maintenance contracts.
Technology shifts to watch
- Actuation diversity : Servo-hydraulic, electrodynamic, linear motor, and electromagnetic actuation technologies continue to coexist, with selection driven by frequency range, load capacity, and test fidelity requirements. Hybrid systems and modularity are emerging as differentiators for organizations balancing flexibility and capital efficiency.
- Sensor and data integration : Advances in high-fidelity sensors and real-time analytics — highlighted at recent industry symposia — are increasing the value of test programs beyond pass/fail outcomes, enabling predictive maintenance and materials modeling.
- Automation and cell orchestration : Biaxial and multi-axis systems, combined with automated specimen handling and integrated environmental chambers, are becoming table stakes for high-throughput labs, especially in EV and aerospace supply chains.
Competitive landscape — what the full report reveals
Our competitive assessment centers on established global vendors and regional challengers. The full study contains detailed capability maps, go-to-market playbooks, and supplier scorecards; below we summarize strategic positions without disclosing proprietary benchmarking scores.
Fatigue Machine Market
- MTS Systems Corporation — A long-standing leader known for servohydraulic and electrodynamic platforms across high-cycle and thermo-mechanical applications. Its strength lies in integrated system packages and deep vertical credentials in aerospace and automotive testing programs.
- ADMET, Inc. — Focused on modular and standards-compliant solutions, ADMET positions itself for labs that require flexible configurations for ASTM/ISO-aligned fatigue regimes and calibration services.
- ZwickRoell Group — A European innovator with a growing emphasis on automated and biaxial systems tailored to composites and high-capacity applications. Recent product introductions underscore an intent to capture advanced EV and battery-structure testing work.
- Instron — Offers a broad portfolio spanning servohydraulic, servo-electric, and linear motor-driven machines. Its integrated software and digital services make it attractive to customers seeking end-to-end test-data workflows.
- Shimadzu Corporation — Combines hydraulic and electromagnetic machines with servopulser capabilities, supporting quick-cycle durability testing and sudden-load simulations.
- Chinese OEMs (Testron, Laryee, Shanghai Bairoe) — These vendors provide cost-competitive servo-hydraulic and electronic systems with increasingly capable sensors and localized service. Their presence is most pronounced in price-sensitive segments and regional lab networks.
Recent vendor activity validates these dynamics: MTS showcased solutions at a major mobility tradeshow in 2025; ZwickRoell launched a next-generation biaxial system targeting EV battery composites in early 2026; and General Atomics completed an unprecedented long-duration aircraft fatigue campaign, illustrating the scale and complexity of contemporary test programs. Meanwhile, ASTM’s symposia continue to spotlight sensor and measurement advances that will be embedded into the next generation of fatigue fixtures and instrumentation.
How PW Consulting’s research helps corporate decision-makers in 2026
Our full Fatigue Machine Market report is designed as a decision-support toolkit for three principal audiences: equipment OEMs, corporate procurement and test-lab managers, and investors evaluating supply-chain plays. We translate market intelligence into immediate actions and risk mitigations.
- For OEMs and product leaders : We provide a prioritized technology roadmap, supplier benchmarking, and modularity strategies that clarify where to invest in R&D versus partnership. Our analysis highlights which actuation and sensing combinations will command price premiums and service stickiness.
- For procurement and test-lab managers : We deliver checklists for specification alignment with evolving standards, lifecycle cost models, and outsourcing vs. insourcing decision frameworks. These tools help lock in procurement terms that minimize total cost of ownership while ensuring compliance with tightening regulatory criteria.
- For investors and corporate strategy : We present a competitive playbook and M&A heat map, identifying the types of capabilities that generate defensible margins — from service contracts and digital analytics to multi-axis automation and thermal cycling cells.
Report contents — practical, operational, and actionable
The complete PW Consulting report includes:
- Market sizing and calibrated forecast model for 2026–2032 with sensitivity scenarios and downside/upside drivers.
- Commercial and technological segmentation analysis (frequency classes, actuation types, applications and regional demand patterns) with downloadable data tables and scenario-specific revenue splits.
- Vendor benchmarking covering product portfolios, service footprints, pricing bands, go-to-market motions, and risk exposure (supply chain, input-cost sensitivity).
- Procurement playbook and specimen-level specification templates aligned to current ASTM/ISO/NASA guidance.
- Case studies documenting recent complex test programs, including multi-year aerospace and unmanned platform programs.
- Strategic recommendations and a two-year implementation roadmap for suppliers and test labs looking to optimize for 2026 commercial cycles.
Importantly, while this preview communicates key implications and strategic pathways, the granular segmentation splits and the underlying financial model are intentionally omitted here to preserve client advantage. These deliverables are included in the full report and accompanied by an interactive model workbook and proprietary scoring rubric.
What to do next — three immediate actions for leaders in 2026
- Audit your test-capability roadmap : Re-evaluate whether your current portfolio (actuation range, environmental control, data capture) aligns with foreseeable standards-driven requirements and customer qualification timelines.
- Negotiate service-first procurement : Shift contract terms toward outcome-linked service agreements and data-platform access, which protect against price competition and provide recurring revenue opportunities for suppliers.
- Prioritize sensor and data integration : Invest in higher-fidelity instrumentation and analytics that deliver predictive insights; this increases test-program value and can shorten certification cycles.
Closing perspective
The fatigue machine market in 2026 is not just a hardware story; it is a systems and data story where testing platforms are extensions of product development, certification, and quality assurance ecosystems. Companies that rethink test capabilities as a strategic asset — coupling modular hardware with sensor-rich telemetry and lifecycle service models — will capture disproportionate value. PW Consulting’s full Fatigue Machine Market study equips leaders with the granular, operational intelligence needed to execute those moves, from procurement specifications to M&A screening.
For executives, program managers, and investors ready to convert insight into action, the comprehensive report includes the models, supplier scorecards, and implementation templates required to make defensible, high-impact decisions in 2026. Access to the full dataset and the interactive forecast model is available on our report page.
For detailed analysis of this topic, please visit the official page: Fatigue Machine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com