

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting: Rice Bran Oil Market Set to Grow at 7.1% CAGR Through 2032
By pmarketresearch, 2026-07-30
Rice Bran Oil Market: Strategic Imperatives for 2026 — A PW Consulting Preview
As PW Consulting’s Senior Strategy Advisor and Head of Industry Analysis, I present a condensed, high-signal preview of our comprehensive Rice Bran Oil Market study. This briefing is designed to orient executive teams, corporate strategists, and investors as they prepare 2026 budgets and tactical roadmaps. It highlights the market’s macro trajectory, key structural dynamics, regulatory flashpoints, and competitive postures — while intentionally preserving the granular segmentation tables and detailed financials for the full report.
Rice Bran Oil Market
Market trajectory at a glance
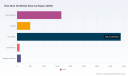
The rice bran oil market has moved from a modest, regionally concentrated commodity towards a higher-value ingredient class with diversified end-use pull. On a macro level, the market’s historical growth between 2020 and 2025 reveals steady expansion, and our base-year assessment (2025) positions the market at approximately USD 6.3 billion (million-unit basis). Under our central forecast, the market grows at a compound annual growth rate (CAGR) of 7.1% across the 2026–2032 forecast window, reaching roughly USD 10.2 billion by 2032.
Rice Bran Oil Market
These headline figures matter for strategy because they quantify an opportunity that is both scaleable and premiumizing: scale for supply-chain investments and premium margins for product and brand differentiation. The directionality is clear — buyers, processors, and brand owners must adopt a multi-dimensional approach that balances cost-competitiveness with regulatory compliance and product innovation.
Rice Bran Oil Market
Why 2026 is a catalytic year
- Regulatory inflection points: 2025–2026 has seen active regulatory scrutiny and standards activity impacting trade flows and acceptance criteria for refined rice bran oil. These developments will materially influence trade routes, quality specifications, and due-diligence requirements for exporters and importers.
- Premiumization and health positioning: Rising consumer demand for functional oils — and a notable share of new product launches leveraging fortified or functional rice bran oil formulations — is creating differentiated value pools beyond commodity cooking oil margins.
- Consolidation pressure and fragmentation: Market concentration metrics indicate a partially consolidated supplier base: our analysis shows that the top three players capture a meaningful slice of the market, and the top five widen that footprint. This creates both competitive opportunities for scale players and niche openings for specialized producers.
Demand drivers and structural supply dynamics
Rice bran oil’s unique position — derived as a by-product of white rice milling — underpins its economics and supply behavior. This origin creates specific strategic considerations:
- Linked supply chains: Availability is synchronized with rice milling cycles and regional paddy output. Supply interruptions or rice price volatility therefore cascade into raw material feedstock cost and availability.
- Value-upgrading potential: Technological differences in extraction and refining (physical refining, solvent extraction, patented processes) yield significant variance in oil quality attributes, notably oryzanol retention and free fatty acid profiles. Producers with proprietary refining or extraction methods can command better margins and access to nutraceutical channels.
- Demand diversification: While culinary use remains foundational, the fastest-growing pockets are in nutraceuticals, functional formulations, and branded consumer-packaged goods — areas where margins and brand equity converge.
Regulatory and compliance watchlist
Regulatory developments are a near-term, high-probability risk that must be actively managed:
- European-level notifications related to process contaminants and permissible residuals have created immediate trade re-checks and heightened testing requirements for exporters. This places a premium on traceability and analytical controls within processing chains.
- Several national standards bodies in key markets have updated edible oil specifications, which raises the bar for certification and market entry for smaller processors.
- For companies exporting at scale, proactive engagement with standards-setting agencies and investment in lab capabilities for glycidyl esters, 3-MCPD and other markers is essential to avoid shipment rejections and reputational costs.
Competitive landscape — strategic profiles
The competitive map combines legacy edible oil processors, specialized rice bran oil houses, and global oil & fat processors. Our competitive review highlights strategic positioning across capability, channel reach, and technical differentiation. Below are concise, actionable sketches of representative players analyzed in the full study.
- Specialized refiners with IP-driven processes: Producers using patented physical refining processes that preserve oryzanol and other bioactives occupy a defensible niche. These firms are best positioned to supply the high-margin nutraceutical and fortified food segments.
- Integrated rice value players: Firms with backward integration into rice milling and solvent extraction can optimize raw material capture and cost, better control quality, and scale volumes for commodity channels while selectively upgrading product lines for premium channels.
- Branded consumer players: Some firms combine branded retail presence with industrial channels, using marketing campaigns to expand household penetration and defend shelf economics against established vegetable oil brands.
- Global ingredient processors: Large multinational oil processors participate to secure raw feedstocks and leverage global trading networks, particularly when securing long-term contracts for food formulators and industrial buyers.
These competitive archetypes interact with two important market realities: (1) top-three and top-five market concentration levels reflect both opportunity for consolidation and tactical alliances; and (2) newer entrants with technological differentiation can rapidly scale via export partnerships and co-manufacturing.
Recent industry signals
- Trade shows and industry associations remain active channels for product innovation exchange and B2B contracting; key events in 2025–2026 reinforced cross-border buyer interest and technical partnerships.
- Targeted marketing campaigns by major branded players indicate renewed emphasis on consumer education and demand stimulation for rice bran oil as a healthier oil choice in select geographies.
- Standard-setting initiatives in some developing markets have tightened specifications, creating first-mover advantages for compliant exporters and a market access barrier for less-capitalized processors.
- Analyst tracking shows a material share of new launches in the category leaning on functional/fortified claims — a practical signal for R&D and marketing teams to prioritize value-added formulations.
What this means for 2026 decisions — five strategic plays
- Invest in compliance and traceability: Short-cycle investments in testing labs, supplier audits, and traceability systems reduce shipment rejection risk and support premium placements in regulated markets.
- Prioritize high-value product development: Allocate R&D and go-to-market resources towards fortified and functional formulations where consumer willingness-to-pay supports higher margins.
- Develop supply-side resilience: Secure bilateral sourcing agreements with mill operators, diversify feedstock origination across crop cycles, and consider tolling or co-processing partnerships to manage raw-material seasonality.
- Consider strategic M&A or alliances: The mid-market remains fertile for bolt-on acquisitions that add refining IP, export capacity, or branded channels. Alliances with specialty ingredient firms can accelerate entry into nutraceutical and functional segments.
- Adopt scenario-based pricing models: Use mid-term scenario planning to stress-test procurement strategies against regulatory shocks, raw material price inflation, and trade disruptions.
Report contents — practical and executable
Our full Rice Bran Oil Market study is structured to be directly operational for executive teams and strategy functions. Core deliverables include:
- Topline market model with historical series and a 2026–2032 forecast (base year 2025), with sensitivity scenarios.
- Segment-level demand models and TAM/SAM/SOM frameworks (regional, product type, and application analyses) — note: granular split tables and discrete segment values are reserved for the full report to preserve the integrity of our proprietary modeling.
- Competitive vendor matrix and capability scorecards, including technical process comparisons, export footprints, and channel strength assessments.
- Regulatory impact analysis and an actionable compliance playbook tailored to export-oriented processors and branded companies.
- Commercial playbooks for premiumization, co-manufacturing, and B2B contracting with a recommended sequencing of initiatives tied to CAPEX and OPEX implications.
How to use this preview — recommended next steps
- For corporate strategists: use the headline growth trajectory and scenario recommendations to stress-test your 2026 capital allocation and product roadmap prioritization.
- For procurement and operations leaders: initiate supplier due-diligence escalations where export compliance risk is material, and model tolling or integration options to hedge seasonality.
- For investors and M&A teams: identify targets that combine proprietary refining capability with export-ready compliance; the value uplift potential is highest where IP and market access intersect.
- For R&D and marketing: re-benchmark product pipelines against the demonstrated consumer pull for functional/fortified formulations and realign launches to capture premium shelf space.
PW Consulting’s full Rice Bran Oil Market report provides the quantitative granularity and executable templates required to convert the macro opportunity into board-level decisions and operational plans. This preview outlines what’s strategically material for 2026; the full study supplies the precise segmentation matrices, firm-level market shares, and actionable financial models that will enable implementation.
To obtain the complete report and our proprietary models, which include the full regional/application breakouts and company-level revenue estimates, contact PW Consulting’s market intelligence desk or visit our report access page. Our team is prepared to deliver an executive briefing tailored to your organization’s role in the rice bran oil value chain.
For detailed analysis of this topic, please visit the official page: Rice Bran Oil Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: TPU Paint Protection Film Market Poised for 5.8% CAGR through 2032
By pmarketresearch, 2026-07-30
TPU Type Paint Protection Film Market — Strategic Outlook for 2026 Decision Makers
As corporates, OEMs, private equity investors, and strategic suppliers prepare plans for 2026 and beyond, understanding the trajectory of the thermoplastic polyurethane (TPU) Paint Protection Film (PPF) market is imperative. PW Consulting’s new market study delivers an actionable intelligence package tailored to those decisions. Below we summarize the study’s strategic value, the non-obvious dynamics shaping 2026 choices, and the practical playbook elements that will influence winners and laggards in a market that is consolidating even as it grows.
TPU Type Paint Protection Film Market
High-level market context
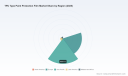
Our analysis uses 2025 as the base year and draws on a 2020–2025 historical series to project the market through 2026–2032. The TPU PPF market documented steady expansion in the historical window and is forecast to continue growing at a compound annual growth rate (CAGR) of 5.8% over the 2026–2032 horizon. From the early-decade baseline to the 2025 base, volume‑and‑value momentum is clear; our forecast extrapolates that trajectory into multiple strategic scenarios out to 2032. Importantly, while headline growth is moderate and predictable, the value capture dynamics are being actively reshaped by raw materials, regulatory friction, service models, and product innovation.
TPU Type Paint Protection Film Market
Why this study matters for 2026 planning
- Tactical capital allocation: The market’s predictable CAGR enables disciplined capital planning — but only if companies account for margin volatility driven by premium raw materials and certification costs. The report provides sensitivity models that quantify the impact of raw material mix changes and warranty commitments on unit economics.
- Go‑to‑market and channel choices: The landscape is bifurcating between branded premium channels (OEM partnerships, certified installers) and lower-cost aftermarket/volume players. Our workbench helps decide where to invest — exclusive OEM supply agreements, branded retail distribution, or decentralized installation networks.
- M&A and partnership prioritization: Market concentration metrics suggest meaningful room for strategic consolidation and capability buys (product formulation, coating tech, installer networks). We map which capability gaps most improve value capture.
- Regulatory and compliance readiness: Certification timelines and geographic regulatory demands are a gating factor for market entry and pricing. Our regulatory checklist minimizes time‑to‑market risk for 2026 launches.
Core dynamics reshaping value pools
- Raw materials premiumization: Premium TPU formulations using specialty polyols (for example, polycaprolactone-based polyols) materially raise product cost but deliver superior optical clarity, self-healing and longevity. The report models the trade-offs between premium pricing elasticity and increased BOM (bill of materials) cost.
- Regulatory and compliance tailwinds: Certifications such as REACH in Europe, VOC controls under EPA guidance, and national polymer standards (e.g., BIS) are not just compliance items — they are commercial differentiators. The study details certification pathways and expected time & cost to compliance across major markets.
- Service and warranty as purchase drivers: Extended warranty programs and installer certification are emerging as decisive factors in buyer choice. We quantify the lifetime value uplift from warranty extensions versus the incremental cost of enhanced QA and materials.
- Product innovation and differentiation: Color PPFs, hydrophobic coatings, and next-gen self-healing chemistries are expanding addressable use-cases. The report evaluates which innovations are likely to penetrate mainstream demand in the short and medium term.
Competitive landscape — who matters and why
Market leadership today is a mix of global chemical majors, specialized PPF brands, and agile regional manufacturers. The competitive profile in our study balances capability mapping with commercial moves observed through 2024–2026.
TPU Type Paint Protection Film Market
- Lubrizol (Cleveland, Ohio) — Leveraging polymer expertise, Lubrizol’s recent investments in localized TPU production underline a strategy to control upstream quality and supply continuity. Their 2025 ESTANE TPU production line launch is emblematic of moves to shorten supply chains and support OEM-level specifications.
- 3M (St. Paul, Minnesota) — A legacy brand with deep materials science and channel reach, 3M’s extension of warranty terms signals a push to cement premium positioning and reduce purchase friction in key markets. Their scale allows aggressive R&D and customer support programs.
- XPEL (Dallas, Texas) — As a channel-focused PPF specialist, XPEL’s OEM collaborations and customization programs demonstrate the strategic value of direct-to-OEM commerce, especially in the EV segment where OEM-branded accessories are high-margin add-ons.
- Evol V (Fort Lauderdale, Florida) — Product innovation through differentiated aesthetics and surface technologies (Dry‑X™, self-healing finishes, hydrophobic treatments) highlight how mid-sized players can create niche leadership and command premium pricing.
- Regional Chinese and Indian players — A cluster of Guangzhou‑based firms and Indian manufacturers are pursuing cost leadership, rapid local certification, and aggressive distribution. Their presence accelerates price competition in certain channels but also expands overall market accessibility.
Our competitive concentration analysis indicates that the market is materially concentrated among a small set of leading suppliers, implying that tactical moves by any of the top players (capacity, warranty, OEM tie-ups) can move value pools across the chain.
Recent developments that should shape 2026 strategies
- Localized TPU capacity additions and white papers from polymer providers that accelerate specification standardization.
- New product releases that combine color, hydrophobicity, and self-heal features — these broaden use-cases beyond scratch protection into customization and aesthetic preservation.
- Strategic OEM partnerships and direct-order programs, demonstrating a shift from purely aftermarket to integrated OEM accessory channels.
- Warranty enhancements and installer training programs that increase total cost of service but also raise barriers to entry.
- Trade show activity and product launches in key markets highlighting both demand growth and intensifying competition.
What PW Consulting’s full report provides (practical, actionable deliverables)
- Robust market sizing and a transparent forecasting model (base year 2025; historical 2020–2025; forecast 2026–2032) with scenario toggles for raw material shocks, policy shifts, and rapid EV adoption curves.
- Go‑to‑market playbooks for OEM, distributor, and installer routes — including channel economics, pricing levers, and contract templates.
- Competitive heatmaps and capability matrices that identify acquisition targets and partnership fits based on technology, channel, and geography.
- Regulatory and compliance roadmap for REACH, EPA VOCs, BIS and other jurisdictional requirements — including estimated timelines and cost buckets.
- Product benchmarking across performance, warranty, and cost-to-produce, plus supplier selection frameworks for materials and co‑manufacturing.
- Installer enablement and certification blueprint — training curriculum, certification criteria, and monetization pathways to scale certified-install networks.
- Risk register and mitigation playbook covering supply-chain fragility, price pass-through mechanics, and reputational risks from failed installations.
Concrete strategic recommendations for 2026
- Prioritize upstream relationships with TPU resin suppliers or secure offtake contracts to stabilize input costs for premium formulations.
- Pursue targeted OEM partnerships or exclusive accessory programs in the EV and premium vehicle segments — these yield higher ASPs and customer lifetime value.
- Differentiate through warranty and installer certification rather than competing solely on price; our ROI models show warranty-driven demand growth outperforms short-term price cuts.
- Invest in product variants (color, hydrophobic, self-heal) where your distribution network can monetize aesthetic upsells — these variants have disproportionate margin potential.
- Build regulatory readiness into product development cycles; early REACH and VOC compliance unlocks premium channels in Europe and North America.
- For investors and M&A teams: target bolt-on acquisitions that provide formulation IP, proprietary coatings, or established installer networks to accelerate go‑to‑market.
How to use this intelligence
Use the study as the operational foundation for budget cycles, product roadmaps, and M&A diligence in 2026. The quantitative forecasts and scenario models enable precise capex sizing, while the playbooks reduce time-to-market for certification and channel rollout. For boards and executive committees, the study converts market trends into prioritized initiatives with clear P&L and balance-sheet implications.
Next steps — obtain the full dataset and proprietary splits
This overview highlights the material strategic implications of the TPU Type Paint Protection Film market through 2026 and beyond. PW Consulting’s full report contains the granular regional and application splits, company revenue benchmarking, price-by-product curves, and supplier-level shipment schedules that underpin the summarized recommendations above. To unlock the detailed inputs and interactive forecasting models required to finalize 2026 plans, please consult our publication page and request access to the complete dataset.
For detailed analysis of this topic, please visit the official page: TPU Type Paint Protection Film Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: 2‑Methyl‑1,3‑Propanediol Market Poised at USD 145 Million in 2025
By pmarketresearch, 2026-07-30
2-Methyl-1,3-Propanediol Market: Strategic Outlook for 2026 Decision-Makers
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present a concise, high-impact perspective on the 2-Methyl-1,3-Propanediol (MPDiol) market geared specifically to inform executive choices in 2026. This short-form brief highlights the structural forces, commercial levers, and competitive dynamics that will determine winners and losers as the market transitions from mid-cycle consolidation to selective growth. It deliberately surfaces the analytical framework and strategic implications while reserving granular segmentation numbers for the full report—your tactical guide to executing with confidence.
2-Methyl-1, 3-Propanediol Market
Executive summary: what this study delivers for near-term strategic decisions
- Validated market trajectory and scenario-ready forecasts anchored on a comprehensive historical baseline (2020–2025), a 2026 decision point, and a forward-looking horizon to 2032.
- A clear assessment of concentration and power: a highly concentrated supplier base governs pricing, availability, and margin capture, creating both barriers and targeted opportunities for market participants.
- Actionable playbooks for commercial, procurement, and investment teams—covering contract structures, capacity strategies, and product & grade prioritization—designed for 12–24 month execution cycles starting in 2026.
- Regulatory and feedstock risk matrices, including recent regulatory developments and their near-term commercial consequences.
Market trajectory and macro view
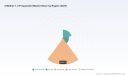
Our analysis uses 2025 as the base year, with an empirically grounded historical series from 2020–2025 and a forecast window spanning 2026–2032. The MPDiol market has demonstrated steady, low-single-digit growth through the historical period and continues on a moderate upward trajectory into the forecast horizon. The compound annual growth rate (CAGR) applied for the forecast period is 3.0%, reflecting a mature specialty-chemical market where demand gains are driven by performance-led applications rather than commodity volume expansion.
2-Methyl-1, 3-Propanediol Market
Key macro takeaways for 2026 planning:
2-Methyl-1, 3-Propanediol Market
- The market has expanded materially since 2020, and while growth is not exponential, it is reliable—supporting disciplined capacity investments and specialty-mix optimization.
- Near-term upside is linked to engineered-resin demand, coatings performance upgrades, and selected specialty chemical applications; downside is concentrated in cyclical end-markets such as discretionary automotive and capital-intensive construction segments.
Market structure and concentration
MPDiol is supplied predominantly by a small set of global chemical producers with integrated production capabilities and advanced purification technologies. The market exhibits a high degree of concentration among the leading suppliers, a structural feature with important implications:
- Pricing dynamics are supplier-driven: incumbents with scale and integration can defend margins through flexible upstream sourcing and premium-grade product offerings.
- Commercial negotiation power rests with a few large producers, increasing the strategic value of long-term offtake agreements and backward-integration strategies for downstream players.
- High concentration improves predictability of supply in normal cycles but creates single-point risks during plant outages or feedstock disruptions—risk scenarios that demand contingency planning in 2026 procurement playbooks.
Demand dynamics and end-use themes
Demand remains anchored in polyester resin systems—both unsaturated polyester for composites and polyester variants for high-performance coatings—supported by polyurethane applications and specialty plasticizers. The performance attributes of MPDiol (elevated functionality, improved toughness, formulation flexibility) make it attractive where end-product performance commands a premium.
Critical demand-side drivers to monitor in 2026:
- Composite adoption in lightweighting and infrastructure repairs—incremental gains in wind, marine, and selected automotive niches support steady resin demand.
- Coatings and specialty paints—formulation upgrades that emphasize durability and reduced VOCs continue to favor tailored polyester chemistries incorporating MPDiol.
- Shift toward specialty grades and higher-purity streams as formulators extract margin through performance differentiation, increasing the value of purification-capable suppliers.
- Regulatory signals that expand permissible uses or change acceptance in adjacent markets—creating occasional demand spurts that favor nimble suppliers and well-prepared buyers.
Regulatory & feedstock dynamics that will matter in 2026
Two technical-regulatory factors will particularly influence strategy in the near term.
- Regulatory permissibility: Recent exemptions approved by a major regulator in mid-2024 broadened acceptable inert ingredients in certain pesticidal formulations. Such rulings can open adjacent white-space demand for specialty solvents and intermediates, contingent on formulators adapting product specifications. Executives should track approvals and time product qualification processes accordingly.
- Feedstock and process dependencies: Commercial MPDiol production relies on hydroformylation routes converting allyl alcohol (and related intermediates) using carbon monoxide and hydrogen. This creates concentrated feedstock exposure—availability, pricing, and vendor reliability for allyl alcohol and synthesis gas components will directly influence cost curves and spot availability.
Competitive landscape: who matters and why
The market is served by established specialty-chemical companies that combine global supply footprints, technology depth, and customer-facing formulation support. Key participants include long-tenured incumbents and integrated producers with differentiated capabilities:
- LyondellBasell Industries: Offers MPDiol under branded formulations and operates dedicated sites with downstream channel expertise. Its execution strength lies in integrated supply chains and branded customer engagements.
- DuPont de Nemours: Focuses on capacity investments and high-purity grades, aiming at value capture in specialty polyester and engineered applications. Strategy emphasizes quality differentiation and selective capacity growth.
- OXEA GmbH: Utilizes integrated manufacturing and purification know-how to serve quality-sensitive coatings and resin markets across Europe and beyond.
- BASF SE: Positions MPDiol within a broader performance-materials portfolio, enabling cross-selling into adhesives, coatings, and engineered resin systems backed by global application support.
- Dow Inc.: Leverages hydroformylation expertise and broad polymer chemistry capabilities to serve polyester, polyurethane, and personal-care supply chains.
- Perstorp Holding AB: Invests in bio-based process advancements, aligning with sustainability-seeking customers and specialty-coatings applications.
For 2026, the strategic advantage will accrue to players who combine flexible feedstock strategies, grade/purity differentiation, and application support services. New entrants face material technical and commercial barriers; meaningful disruption will likely come from targeted bio-based or purification-led innovations rather than broad-scale commoditization.
Risks, shocks, and scenario planning
Executives must model three interdependent risk vectors when setting 2026 strategies:
- Regulatory shocks—unexpected changes in permissible uses or product stewardship requirements can create short-term surges or sudden demand erosions in certain end-markets.
- Feedstock interruptions—supply-chain constraints for allyl alcohol or synthesis gas can propagate quickly due to limited alternative production routes, amplifying price volatility.
- Concentration-related outages—given the clustered supply base, plant outages at a major supplier can tighten spot markets rapidly; contingency capacity or diversified sourcing agreements are vital mitigants.
What the full PW Consulting report contains (practical tools for 2026)
- Detailed market model (historical 2020–2025; base year 2025; forecast 2026–2032) with scenario toggles for macroeconomic sensitivity, feedstock shocks, and regulatory outcomes.
- Segment and regional demand maps with quantitative splits and growth levers—(note: segmented values are intentionally withheld from this preview and are available in the full report).
- Supplier benchmarking and capability heatmaps, including grade-specific purification capacity, logistics resilience, and innovation pipelines.
- Price-curve and margin simulations tied to feedstock cost inputs (allyl alcohol, CO/H2), plus procurement playbooks for lock-in and flexible-sourcing arrangements.
- M&A and partnership playbook: valuation heuristics, integration risk checklists, and a prioritized list of strategic targets by capability gap.
- Regulatory tracker and impact assessment—mapping recent rulings, such as the mid-2024 inert-ingredient exemptions, to product qualification pathways and addressable market expansion.
How executives should act in 2026
- Prioritize supply resilience: negotiate multi-year offtakes with staggered take-or-pay elements, and identify dual-source strategies for feedstock-sensitive inputs.
- Allocate investment to specialty grades: deploy modest capital to raise purification capability or co-develop high-purity streams with incumbent suppliers to capture formulation-driven margins.
- Embed regulatory intelligence into commercial planning: accelerate qualification timelines for new authorized uses and align technical dossiers to anticipated regulatory shifts.
- Hedge feedstock exposure: where feasible, pursue hedging instruments or backward integration options to stabilize input cost volatility.
- Consider partnership over greenfield: given high concentration and capital intensity, joint ventures or toll-manufacturing agreements can be lower-risk pathways to secure capacity.
In sum, the MPDiol market presents a pragmatic growth story: steady expansion, concentrated supply, and selective pockets of premiumization. For 2026, the imperative is not to chase volume blindly but to orchestrate supply-security, product differentiation, and regulatory readiness. The full PW Consulting study converts these imperatives into executable steps, models, and negotiation playbooks tailored for procurement, commercial, and corporate development teams.
Next steps
PW Consulting’s full report contains the complete datasets, segmented forecasts, and tactical annexes necessary to operationalize the above recommendations. For decision-makers preparing budgets, procurement strategies, product roadmaps, or M&A assessments in 2026, our report is designed as the single-source analytical and tactical companion.
For detailed analysis of this topic, please visit the official page: 2-Methyl-1, 3-Propanediol Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Diamond Core Drilling Market to Reach USD 335.98 Million by 2032, 6.6% CAGR
By pmarketresearch, 2026-07-30
Diamond Core Drilling Market — Strategic Preview for 2026 Decision-Makers
Executive snapshot
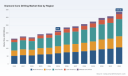
Diamond core drilling sits at the intersection of exploration intensity, infrastructure ambition, and equipment innovation. Our PW Consulting Diamond Core Drilling Market study (base year 2025; historical window 2020–2025; forecast 2026–2032) finds the sector expanding at a mid-single-digit pace — a compound annual growth rate of 6.6% across the forecast horizon. After recovering from cyclical volatility during the early 2020s, the market reached a new inflection point in 2025. Under our central scenario, the market trajectory accelerates through 2032, underpinned by stronger exploration programs, selective infrastructure projects, and a rising attachment of automation and aftermarket services to core drilling packages.
Diamond Core Drilling Market
Why this matters for 2026 corporate strategy
For executives planning capex, procurement, M&A or product roadmaps in 2026, the study provides three tangible strategic values:
Diamond Core Drilling Market
- Demand-risk calibration: a validated top-line forecast sequence (2020–2025 historical series plus 2026–2032 projections) enables treasuries and strategy teams to stress-test budgets and financing under alternative recovery and commodity scenarios.
- Competitive positioning: a granular competitive framework (company archetypes, capability maps and aftermarket exposure) helps boardrooms decide whether to invest in organic R&D, pursue bolt‑on acquisitions, or partner for regional market access.
- Operational resilience: supplier risk matrices and scenario planning (including raw-material price shocks and labour constraints) allow procurement and operations leaders to redesign supply contracts, inventory buffers and skills pipelines ahead of regulatory changes.
Snapshot of the macro picture
Our market sizing shows a clear recovery and steady growth path: after the disruption years, the market reached a new baseline in 2025 and, under the central forecast, expands materially through 2032. This expansion is broad‑based — reinforced by both equipment and service lines — but characterized by shifting margin pools as aftermarket services, digital monitoring and automation capture increasing value. The market concentration metrics signal a moderately consolidated landscape: the top three and top five players account for meaningful, but not overwhelming, shares — a structure that supports both strategic partnerships and acquisitive plays.
Diamond Core Drilling Market
What’s inside the full PW Consulting study (practical deliverables)
Our report is built for decision-makers who need executable intelligence, not just descriptive charts. Core deliverables include:
- Top‑down market model (2020–2032) with transparent assumptions and sensitivity levers for commodity price, CAPEX cycles and exploration intensity.
- Scenario playbooks (three scenarios) that translate macro variance into P&L and capital requirements for OEMs, contract drillers and large exploration customers.
- Supply‑chain and cost‑curve analysis identifying key margin levers (raw materials, logistics, aftermarket mix) and stress points under a tungsten‑carbide price shock.
- Competitive benchmarking with company scorecards covering product breadth, digital capability, service footprint and balance‑sheet resilience.
- Commercial playbooks for go‑to‑market moves: pricing, bundling (equipment + service), channel strategy, and risk mitigation contracts.
- Regulatory and ESG impact assessment: water‑use requirements, waste handling mandates and quality certification expectations (e.g., ISO 9001 trends).
- Actionable M&A screens and integration checklists tailored to buyers and minority investors.
- Ready‑to‑use executive dashboards and downloadable data annex for board briefings and investor conversations.
Note: the public preview intentionally omits detailed regional and application-level splits and the underlying transaction-level datasets; those proprietary tables and raw-data exports are available in the full PW Consulting report.
Competitive landscape — what the leading players are doing
The market comprises a mix of large diversified industrials, specialist drill manufacturers and regional contract drillers. Below we distill the strategic posture of the most influential names covered in our analysis and the decision implications for counterparties and investors.
- Boart Longyear (South Jordan, Utah) — A specialist with deep service capability and a legacy brand in core drilling. Their DNA is service‑heavy, with a strategic emphasis on full‑cycle delivery to miners. For clients, Boart Longyear represents an attractive partner where project scale and geological complexity demand integrated drilling services. Strategic implication: competitors should evaluate service bundling or niche partnerships rather than head‑on price competition.
- Epiroc (Atlas Copco, Stockholm) — A diversified equipment OEM with scale in electrified drilling platforms, automation and aftermarket parts. Epiroc’s advantage is systems integration — electrified rigs, telematics and a global service network. Strategic implication: smaller OEMs and drill contractors should consider technology partnerships or white‑label arrangements to remain competitive in automation‑intensive tenders.
- Sandvik (Stockholm) — Engineering focus on high‑performance drilling tools and digital enhancements. Sandvik’s go‑to‑market pairs product innovation with channel reach. Strategic implication: incumbents must prioritize R&D pipelines in bit design and predictive maintenance to protect margin.
- Multi Power Products (Kelowna) — A nimble player with localized manufacturing and strong aftermarket service orientation. Their competitive edge is responsiveness to regional project cycles. Strategic implication: large OEMs can learn from their localized service models to reduce lead times in specific geographies.
- CS Unitec (Trumbull) — Specialist in handheld and portable systems. Their portfolio aligns with smaller projects and niche applications where mobility and low footprint matter. Strategic implication: clients with mixed project sizes should maintain a multi‑tier supply strategy to optimize cost and flexibility.
- DUSS (Neubulach, Germany) — German engineering with strong custom and specialist rigs. DUSS is positioned to capture high‑value technical drilling work. Strategic implication: for complex geology projects, partner selection should weigh technical fit as heavily as price.
- Wuxi Geotec (Wuxi, China) — Cost‑competitive OEM with a strong regional footprint and aggressive aftermarket growth. Their presence pressures global OEM margins in price‑sensitive segments. Strategic implication: western OEMs should sharpen differentiation (durability, service, digital tools) or explore strategic JV/assembly partnerships in low‑cost regions.
- Refina (UK) — Specialist in high‑precision coring equipment and tooling. Strategic implication: opportunities exist to co‑develop high‑value tool sets with labs and exploration companies focused on critical minerals.
- Cascade Environmental (US) — Service firm focused on environmental drilling and sampling. Their growth reflects increasing demand for compliance‑centric projects. Strategic implication: environmental service capabilities are a value add in mixed tenders and can be a differentiator in heavily regulated markets.
- Godbe Drilling (US) — Regional contract driller with operational flexibility and project execution strengths. Strategic implication: clients seeking speed to first core should evaluate regional contract drillers with proven execution metrics.
The market’s CR3 and CR5 figures reflect a meaningful leadership bloc, but significant share remains accessible to regional specialists and innovative new entrants — creating attractive M&A and partnership corridors for ambition players.
Recent market signals — what to watch
- Mid‑2025 saw several notable drilling contracts and program commencements, signaling active ground programs among juniors and listed explorers.
- Industry associations continue to shape standards: the Canadian Diamond Drilling Association’s recent convention and the International Diamond Drilling Association’s updated standards (2023) have accelerated standardization on safety and quality.
- Raw‑material shocks — notably a spike in tungsten‑carbide pricing in 2026 — are already compressing bit‑level margins and forcing OEMs to reassess procurement strategies.
Regulatory, supply and labour headwinds
Four structural frictions deserve board attention in 2026:
- Standards & certification: ISO 9001 and sector norms are becoming de facto entry criteria, raising the bar for smaller contractors.
- Environmental mandates: water efficiency and waste‑management requirements are increasing operational cost and capex for drilling projects, particularly in sensitive jurisdictions.
- Raw‑material volatility: bit component price spikes can erode margins quickly unless firms hedge, diversify suppliers or redesign consumable mixes.
- Skilled labour shortage: an industry‑wide shortage of experienced operators is accelerating demand for automation and remote‑operated systems — a double‑edged sword that raises capital intensity while lowering unit operating risk over time.
How to use this preview in 2026 — an actionable checklist
- Immediate (0–6 months): Reassess supplier contracts for tungsten and carbide components; launch a skills audit and a pilot automation program in at least one high‑cost site.
- Medium term (6–18 months): Reprice bids to reflect increased compliance costs; consider bolt‑on targets with complementary service footprints in priority geographies.
- Scenario planning: Model P&L impacts under raw‑material shock and regulatory tightening scenarios provided in the report; set trigger thresholds for capex deferral or accelerated M&A activity.
- Risk monitoring: Implement the PW Consulting drilling market dashboard (included in the full report) to track lead indicators such as new drill program announcements, tender pipelines and key input prices.
Next step — where to get the full intelligence
This preview surfaces the strategic levers and risks shaping the diamond core drilling market in 2026. The full PW Consulting Diamond Core Drilling Market report contains the detailed regional and application breakdowns, proprietary company scorecards, pricing curves, and downloadable datasets required to operationalize the insights above. These detailed tables and the underlying transaction‑level data are purposefully restricted to the full report to preserve the competitive integrity of our primary research.
For boards, strategy teams and operational leaders preparing for 2026, this study is a practical decision tool: it combines defensible market forecasts, competitor playbooks, and direct implementation checklists to convert market intelligence into competitive advantage.
For detailed analysis of this topic, please visit the official page: Diamond Core Drilling Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Emulsion Explosive Sensitizer Market to Reach USD 293.7M by 2032 at 6.2% CAGR
By pmarketresearch, 2026-07-30
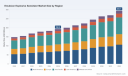
Emulsion Explosive Sensitizer Market — Strategic Briefing for 2026 Decision-Makers
Executive synopsis
As the global mining, quarrying and heavy civil construction sectors recalibrate for a lower-emissions, higher-safety operating environment, emulsion explosive sensitizers are transitioning from a niche input to a strategic component of supply chains and field operations. Our 2026-focused market study uses 2025 as the base year and delivers a forward-looking view through 2032. The market is projected to expand at a compound annual growth rate (CAGR) of 6.2% across the forecast horizon, with the overall market value rising from its 2025 baseline to a materially larger market by 2032. For executive teams planning capital allocation, procurement strategy or M&A activity in 2026, the report identifies where growth, consolidation and regulatory-driven substitution will have the biggest operational and financial impact.
Emulsion Explosive Sensitizer Market
Why this research matters in 2026
- Timing: 2026 is the inflection point for several dynamics (technology diffusion, regulatory tightening, and shifting input-cost structures) that will determine which players can scale safely and profitably.
- Decision leverage: The report translates market growth (guided by the stated CAGR) into board-level implications — from factory footprint decisions to the viability of on-site sensitizer integration for remote operations.
- Practicality: Beyond forecasting, our study equips commercial teams with executable playbooks — supplier scorecards, field-scaling templates, and scenario-driven purchasing triggers — that bridge strategy and implementation.
Market trajectory and what the headline numbers reveal
Using 2025 as the analytical base, the emulsion explosive sensitizer market shows a steady multi-year expansion driven by ongoing demand in resource extraction and infrastructure projects together with the progressive adoption of emulsified explosive systems over legacy formulations. The projected CAGR of 6.2% encapsulates both organic demand growth and the penetration of higher-value sensitizer packages as operators pursue safer, more controllable blasting outcomes. For strategic planning, the headline growth indicates a market that remains attractive for incumbents and selective new entrants — large enough to justify mid-sized capex and M&A, yet granular enough that operational excellence and distribution reach will decide winners.
Emulsion Explosive Sensitizer Market
What’s inside the full report (practical, implementation-focused)
- Market sizing and top-line forecasts (base year: 2025; forecast: 2026–2032) with scenario modeling for low, base and high-growth pathways.
- Supply-chain diagnostic — raw material volatility mapping, critical supplier dependency assessment, and actionable hedging/contracting playbooks tailored to procurement and operations teams.
- Regulatory impact matrix — regionally differentiated risk ratings, likely compliance cost trajectories, and mitigation strategies for contaminant and emitter controls.
- Commercial benchmarking — supplier scorecards, pricing architecture templates, and tender-design guidance for long-term offtake and on-site production partnerships.
- Operational toolkits — capex model for modular on-site emulsion plants, sensitizer integration checklists, and quality/QA protocols proven in remote-blasting environments.
- M&A and investment guidance — filters for target selection, integration risk assessment, and value-creation playbooks for bolt-on acquisitions in production and distribution segments.
- Data appendix and model workbook — downloadable forecast model with sensitivity levers, and a confidential dataset that includes the detailed segment splits intentionally withheld from this preview.
Competitive landscape — who shapes the market
The market exhibits moderate concentration: the three largest suppliers account for a significant share of market throughput and the top five players command an even broader presence. This concentration creates both barriers (scale economies, integrated service offerings) and opportunities (niche specialization, field-servicing differentiation) for challenger firms.
Emulsion Explosive Sensitizer Market
- Dyno Nobel — A technology-forward incumbent, Dyno Nobel combines branded bulk emulsion lines (TITAN® series) with a field strategy centered on portable modular emulsion plants. The ability to produce sensitizer-integrated emulsions on site gives them a tactical advantage in remote or high-logistics-cost operations. Recent safety-data updates have emphasized formulation stability and on-site integration, underlining their operational focus on compliance and asset availability.
- Orica Limited — Orica continues to lead in systems-level solutions, supplying advanced bulk emulsion systems and sensitizing chemistries optimized for both surface and underground operations. Their competitive moat rests on integrated service bundles and deep operational support to major miners that prioritize productivity and environmental performance.
- MAXAM — With a strong commercial explosives offering that includes emulsion-based products, MAXAM plays to customers seeking turnkey supply across mining and quarrying. Their strategy emphasizes product breadth and distribution reach in regions with steady capital project pipelines.
- Austin Powder Company — Austin Powder’s position is differentiated by its focus on integrated field services and tailored sensitizing technology for industrial projects. Their operational excellence in service delivery offers a pathway for premium pricing in safety- and availability-sensitive contracts.
- AEL Mining Services — Targeting African and South American markets, AEL’s integrated blasting solutions link regional expertise with emulsion technologies. Their role in markets with complex logistics informs best-practice approaches for inventory management and mobile production assets.
- Sasol Limited — As a producer of key sensitizing components and fuels used in emulsion formulations, Sasol occupies an upstream niche with strategic importance for feedstock security and cost. Their position affects margin structures across downstream producers.
Recent developments shaping 2026 strategic choices
- Safety and compliance: Major suppliers have issued updated safety documentation and patents that codify safer inhibited emulsion formulations and field practices. These developments reduce operational risk but also raise the bar for quality control and supplier selection.
- Production models: Portable modular emulsion plants are moving from pilot to commercial scale, enabling on-site sensitizer integration for remote projects. This lowers logistics exposure and creates a strategic choice between centralized production vs on-site manufacturing partnerships.
- Cost and input volatility: Raw-material and labor cost pressures have tightened production margins industry-wide. Procurement teams must prioritize strategic sourcing and contract structures that mitigate input-price shock — the report offers contract templates and scenario-based procurement triggers.
- Environmental and regulatory pressure: Peer-reviewed field studies and regulatory approvals in certain jurisdictions favor emulsion technologies over older formulations due to improved emission profiles and controllability. These shifts will influence procurement specifications and long-term supplier selection.
Strategic implications for corporates and investors
- Procurement leaders: Move from spot buying to strategic supplier partnerships that embed performance-based pricing and flexible on-site production options. Include environmental KPIs in RFPs to align with evolving regulatory preferences.
- Operations & safety managers: Evaluate the trade-off between centralized quality control and the operational resilience that on-site sensitizer integration provides. Adopt staged rollouts of modular plants with pilot KPIs tied to blasting performance and total cost of ownership.
- Investors and corporate development teams: Use concentration metrics to identify consolidation opportunities where scale or technical IP can generate immediate synergies. The report’s target-filter framework helps prioritize assets with defensible supply positions and repeatable service models.
- Regulators & community stakeholders: Expect more structured engagement requests from operators deploying emulsified systems — demonstrating emission reductions and safety improvements can accelerate permitting and reduce project delays.
How PW Consulting’s analysis helps you act in 2026
Our study is designed to be a decision accelerator. We combine a transparent top-line projection (anchored to 2025 base-year figures and extrapolated through 2032 at a 6.2% CAGR) with executable tools: a procurement playbook, capex templates for modular plants, a supplier due-diligence checklist, and regulatory impact scenarios. Critically, while this briefing surfaces the strategic signals, the full report contains the detailed segment-level intelligence, confidential datasets and downloadable model files that corporate teams use to finalize budgets, negotiate contracts and prioritize investments.
Next steps
For executives preparing 2026 budgets and resource plans, the immediate actions are: commission a targeted supplier-risk audit using our checklist, run a two-scenario capital test for on-site versus centralized production, and engage legal/commercial teams to reframe long-term supply contracts with environmental performance clauses. Access to the full report will provide the granular segment analytics and model workbooks needed to operationalize these recommendations.
PW Consulting’s Emulsion Explosive Sensitizer Market study balances strategic foresight with field-tested operational playbooks — providing the evidence base and tools that organizations need to convert a 6.2% market trajectory into defensible commercial advantage. For the complete dataset, segment splits and the downloadable decision-support models, please refer to the full report.
For detailed analysis of this topic, please visit the official page: Emulsion Explosive Sensitizer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Saccharin Market Poised for USD 456M by 2032 at 7.84% CAGR
By pmarketresearch, 2026-07-30
Saccharin Market — Strategic Outlook for 2026 (PW Consulting)
As companies set priorities for 2026, understanding the commercial dynamics of high-intensity sweeteners has become a board‑level imperative. PW Consulting’s latest Saccharin Market study (base year 2025; historical 2020–2025; forecast 2026–2032) synthesizes primary supplier intelligence, regulatory developments and scenario-driven demand modeling into an operationally focused playbook. The market stood at approximately USD 272 Million in 2025 and is projected to grow to roughly USD 456 Million by 2032, reflecting a compound annual growth rate of 7.84% across the forecast window. This introduction outlines why that trajectory matters, what strategic choices it forces on industry participants in 2026, and where the report adds immediate, actionable value — while intentionally withholding detailed segment-level figures to protect the report’s proprietary granularity and guide readers to the source for full access.
Saccharin Market
Why this report matters for 2026 decision-making
-
Timing: The sector is transitioning from steady replacement demand toward differentiated growth driven by product reformulation in food & beverage, expanded pharmaceutical use-cases and niche personal-care formulations. The growth profile through 2032 validates near-term capacity planning decisions.
Saccharin Market -
Margin pressure and cost arbitrage: Structural cost advantages in certain geographies are compressing global margins for commodity saccharin, while premiumisation (high‑purity grades, certified food‑grade and pharma‑grade streams) opens routes to margin recovery.
Saccharin Market -
Regulatory stability — with conditional caveats: Longstanding regulatory frameworks remain in force, but evolving compliance requirements (REACH, food additive authorizations and local import HS code enforcement) are shifting compliance cost lines for cross‑border supply chains.
-
Fragmented supply base: The market is not concentrated in a handful of dominant global incumbents; instead, a broad supplier ecosystem (from large-scale producers to specialty high‑purity houses) creates win paths for both scale and niche strategies.
What our full report delivers (practical, deal‑ready content)
-
Verified market sizing and growth scenarios: granular total addressable market modelling by demand tier with transparent assumptions (historical validation, consumption drivers and price elasticity ranges).
-
Demand-supply mapping: supplier capacity overlays, utilization scenarios and export flow analysis to identify potential bottlenecks and strategic sourcing locations.
-
Cost-to-serve and margin decomposition: unit cost modeling (raw materials, energy, logistics, compliance) and sensitivity runs to detect margin inflection points under alternative feedstock and freight scenarios.
-
Regulatory risk matrix and compliance playbook: impact assessments for major jurisdictions and a checklist for REACH, FDA and EFSA compliance pathways together with typical timelines and cost ranges for certification.
-
Commercial playbooks for buyers and sellers: contracting templates, quality acceptance protocols, dual-sourcing strategies and sample testing regimens designed for 2026 procurement cycles.
-
M&A and partnership pipeline: candidate screening criteria, valuation anchors for specialty vs commodity assets and integration risk checklists for private equity and strategic buyers.
-
Scenario planning suite: three vetted scenarios (baseline, accelerated adoption, regulatory tightening) with P&L and working capital impacts for immediate deployment in 2026 planning cycles.
Competitive landscape: profiles and strategic implications
The saccharin supply chain comprises multiple archetypes — large-volume commodity producers with backward integration, regional specialists focused on cost-efficient exports, and small, high‑purity producers serving regulated end‑markets. Our competitive analysis profiles each archetype and highlights near‑term strategic moves to watch in 2026.
-
Large-scale commodity producers (China and select EM manufacturers): These players leverage scale, integrated raw-material sourcing and cost advantages to serve global food and industrial channels. Their ISO and food‑safety certifications enable broad export footprints; market entrants and buyers should expect competitive pricing discipline and fast order fulfillment where logistics are optimized.
-
Back‑integrated Indian manufacturers: Some manufacturers combine in‑country raw material sourcing with sizable annual production capability. This reduces exposure to overseas feedstock shocks and supports competitive export pricing, particularly into regional pharma and feed markets.
-
High‑purity and specialty producers (Korea, select EU/US suppliers): These vendors focus on the upper end of the value chain — pharmaceutical and specialized food applications — and command pricing premia tied to traceability, certifications and production controls. For buyers requiring documented safety histories and formulation stability, these suppliers mitigate regulatory and reputational risk.
-
Laboratory and niche distributors: US-based and regional distributors provide just-in-time small-batch supplies and regulatory documentation for R&D and niche applications; their strategic value lies in enabling rapid product development without the overhead of direct supplier qualification.
Recent market developments reinforce these dynamics: in 2025, we tracked launches of new sodium saccharin formulations targeted at food and beverage reformulation and recognition awards for long-established high‑purity producers — signals of both product innovation and brand positioning that matter for premium channels.
Regulation, trade and supply‑chain realities shaping 2026
-
Regulatory foundations: The additive remains subject to long-established food‑additive frameworks in major markets; regulators continue periodic reassessment rather than wholesale bans, which supports continued commercial use but increases the importance of documented safety dossiers and supply‑chain traceability.
-
EU REACH and trade codes: Compliance requirements tied to import classifications and REACH obligations are materially affecting sourcing decisions for companies that sell into European markets — non‑compliance risks can translate into shipment delays and costly remediation.
-
Feedstock and regional cost bases: Readily available raw materials in certain countries underpin persistent cost advantages and have driven capacity expansion. Buyers should model supplier landed costs inclusive of tariffs, compliance spend and freight volatility to understand true unit economics.
Strategic choices for 2026 — recommended actions by stakeholder
-
Manufacturers: Prioritize a two‑track strategy — defend commodity volumes through scale and cost management while investing in a premium stream (pharma‑grade, certified food ingredients). Consider selective capex to improve flexibility (reactors, filtration, certification processes) and pursue backward integration where feedstock volatility is material.
-
Buyers (F&B, pharma, personal care): Implement dual‑sourcing and supplier maturity models; add contractual clauses for traceability and regulatory audit rights. For reformulation initiatives, partner early with high‑purity suppliers to de‑risk shelf‑life and organoleptic outcomes.
-
Investors: Seek platform targets that combine production scale with documented quality pathways. Value accretion is likely where buyers can consolidate fragmented regional capacity, upgrade quality systems and cross‑sell into pharma and specialty markets.
-
Policy and compliance teams: Build REACH readiness and import‑classification checks into 2026 procurement cycles; factor these into landed cost models and supplier selection criteria.
Risk and reward — an executive summary view
Upside drivers include continued reformulation in food and beverages, incremental clinical and OTC pharmaceutical demand and the ability for premium producers to capture value through certification and technical service. Downside risks are concentrated in regulatory shocks, feedstock/energy price volatility and logistics disruptions that could materially affect near‑term margins for commodity suppliers. The interplay between low-cost scale and premium differentiation will determine winners in 2026: companies with flexible supply chains and documented compliance programs will outcompete peers on both price and access to regulated markets.
Immediate takeaways for 2026 planning
-
Recalibrate procurement to reflect true landed costs, not only ex‑works prices; include compliance and logistics as line items in 2026 budgets.
-
For manufacturers, allocate capital to either expand flexible capacity or to up‑grade quality systems — both are defensible in the current growth scenario, but not simultaneously without clear returns.
-
Investors should prioritise targets offering a credible transition path from commodity to specialty segments, or assets that meaningfully consolidate regional supply chains.
-
All stakeholders should lock in vendor audits and certification timelines early; regulatory lead times are non-trivial and can bottleneck commercial plans.
Next steps — how to extract the full strategic value
The summary above highlights the commercial levers and regulatory contours that will shape decisions in 2026. PW Consulting’s full Saccharin Market report contains the granular segmentation, price curves, supplier scorecards, capacity maps and downloadable scenario models required to convert this strategic direction into executable plans (procurement RFP language, M&A diligence packs, capex justification templates). If you are leading procurement, manufacturing strategy or M&A evaluation in this sector, the full dataset and modelling workbench will save weeks of analysis and materially reduce execution risk.
Contact PW Consulting to arrange a briefing, obtain access to the complete report and explore tailored workshops that translate these findings into a 90‑day action plan for your organization.
For detailed analysis of this topic, please visit the official page: Saccharin Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Water Hardness Removal Market to Reach USD 14M by 2032 (5.47% CAGR)
By pmarketresearch, 2026-07-30
Water Hardness Removal Market — Strategic Imperatives for 2026
As PW Consulting’s lead industry analyst, I present an executive introduction to our new Water Hardness Removal Market study — a practical, decision‑grade analysis intended to inform corporate strategy, product roadmaps, and investment choices through 2026 and beyond. Grounded in a historical review (2020–2025) and a forward forecast window (2026–2032), the study synthesizes market sizing, competitive benchmarking, technology deep dives, and go‑to‑market playbooks to convert uncertainty around hard water treatment into strategic advantage.
Water Hardness Removal Market
Why this research matters in 2026
The global water hardness removal market has shown steady expansion over the past half‑decade, moving from the lower single‑digit millions in 2020 to an estimated market size in 2025 that establishes the base for near‑term plans. From that base, our forecast anticipates the market crossing a new threshold in 2026 and continuing to grow to the end of the forecast window in 2032, tracking at a compound annual growth rate (CAGR) of 5.47% for 2026–2032. For leaders deciding on plant investments, channel strategy, or M&A targets, these macro dynamics frame the timing and scale of opportunity.
Water Hardness Removal Market
Two structural takeaways emerge: first, demand growth is broad‑based — supported by residential replacement cycles, commercial retrofit activity, and industrial process needs — and second, market power is concentrated but not monopolistic: the top three suppliers account for roughly 40% of the market and the top five about 50%. That concentration creates both defensive barriers for incumbents and entry points for targeted challengers (service specialization, software‑enabled performance, or materials innovation).
Water Hardness Removal Market
Where growth is coming from — and what keeps it fragile
-
End‑market durability: Residential replacement cycles and increasing awareness of scale impacts continue to drive household purchases, while commercial and industrial buyers invest in preventative scale control to protect equipment and reduce downtime.
-
Technology evolution: Digital control systems, AI‑assisted regeneration, and improved analyzers are shifting value from the device alone to performance guarantees and software‑enabled operating cost reductions. Early movers that couple hardware with analytics capture higher lifecycle revenue.
-
Regulatory and environmental constraints: Certification standards and environmental programs influence permissible chemistries and system attributes. Compliance requirements create a baseline barrier to entry but also raise the value of certified suppliers.
-
Cost pressures: Resin quality, supply chain volatility for polymer feedstocks, and labour for maintenance/replacement remain meaningful components of total ownership cost. These inputs can compress margins unless manufacturers and service providers redesign business models toward consumable and service revenues.
Technology themes to prioritize
-
Ion‑exchange remains the workhorse. Salt‑based ion‑exchange systems continue to dominate installed base dynamics and aftermarket revenues due to proven performance and mature service ecosystems. However, salt‑free alternatives and hybrid concepts are gaining traction where regulatory or environmental concerns constrain salt discharge.
-
Measurement and diagnostics are increasingly strategic. The launch cadence for advanced hardness analyzers and digital titration kits underscores that better measurement reduces customer risk and unlocks premium service propositions (e.g., performance‑based contracts).
-
Smart regeneration and water‑efficient operation are value levers. Vendors integrating adaptive regeneration (including AI‑driven upflow brining and demand forecasting) materially reduce salt and water consumption — a tangible selling point in water‑sensitive regions and for utility contracts.
-
Materials and lifespan engineering matter. High‑quality ion‑exchange resins are the single largest determinant of long‑term system performance; sourcing strategies and resin lifecycle management should be treated as strategic supplier relationships, not commodity purchases.
Competitive landscape — profiles and strategic implications
Our competitive benchmarking centers on a mix of legacy equipment manufacturers, specialist treatment suppliers, and measurement companies. Below we summarize strategic positioning and recent moves that illustrate where incumbent advantage and disruption are concentrated.
-
Culligan (Illinois, United States) — A long‑standing manufacturer and service provider of water softening systems, Culligan combines hardware, installation, and subscription service models. Strengths include nationwide service networks and brand recognition; risks are legacy channel structures and the need to accelerate digital offerings. Recent: introduced a smart high‑efficiency water softener (Aqua Essential) with adaptive home‑needs adjustment, signaling a push to hybridize product and software value.
-
EcoWater Systems (United States) — Focused on advanced water softeners and smart regeneration controls, EcoWater is positioning around operational efficiency and resource reduction. Strengths are product innovation and efficiency claims; risks include differentiation in crowded consumer channels. Recent: emphasized AI‑powered upflow brining and smart regeneration to reduce salt and water use, an enabler for sustainability‑driven procurement.
-
Hach (United States) — A leader in analytical instrumentation, Hach supplies hardness analyzers and test kits that are increasingly integrated into treatment planning and performance verification. Strengths include laboratory reputation and reliable instrumentation; risks are margin pressure as handheld and low‑cost entrants proliferate. Recent: launched the HA‑DT digital titrator hardness test kit for precise measurement and treatment planning.
-
LaMotte Company (United States) — Specialist in field and laboratory testing strips and kits, LaMotte focuses on on‑site monitoring and system calibration. Strengths are market stickiness in test consumables; risks are commoditization and narrow product baskets. Recent: released Insta‑Test hardness test strips targeted to field users for quick calibration and monitoring.
-
Kinetico (Ohio, United States) — Known for non‑electric and advanced softening systems, Kinetico competes on reliability and design differentiation. Strengths include brand loyalty in certain channel segments and robust product engineering; risks include scaling service networks for broader reach.
-
Aquasana (United States) — A consumer‑focused filtration and softening provider that competes on convenience, bundle offerings, and direct channels. Strengths are D2C capabilities; risks are lower margins in marketplace channels.
-
GE Appliances (United States) — Integrates water softening into appliance ecosystems and benefits from OEM scale and distribution. Strengths include appliance channel access and brand trust; risks are coordination of R&D across larger corporate product portfolios.
Across these players, product launches and feature upgrades (smart regeneration, high‑precision analyzers, on‑site test strip improvements) indicate a market where differentiation is increasingly achieved through systems thinking — combining hardware, consumables, analytics, and service contracts.
Regulatory, input cost, and operational considerations
-
Certification standards matter. Water softeners and scale reduction devices are subject to NSF/ANSI 44 or IAPMO/ANSI Z601 during procurement and public tenders; non‑certified offerings face adoption barriers in institutional channels.
-
Environmental chemistry constraints. Programs such as EPA Safer Choice impose restrictions on certain chelating agents and surfactants, influencing formulation choices for softening adjuncts and scale inhibitors.
-
Raw material dependency. Premium ion‑exchange resins (styrene‑divinylbenzene based) determine longevity and performance; supply disruptions or quality downgrades directly affect lifecycle cost propositions.
-
Labour and maintenance costs. Resin replacement and routine maintenance constitute a non‑trivial share of ownership cost in residential and commercial deployments; service model redesigns (remote monitoring, predictive maintenance) are high ROI initiatives.
What the PW Consulting report delivers — pragmatic contents
This is not an academic exercise. Our report is built for operators, investors, and product leaders who must convert insights into action. Key practical outputs include:
-
Transparent market sizing and methodology (base year 2025; historical 2020–2025; forecast 2026–2032), including sensitivity scenarios around pricing and regulation.
-
Detailed TCO models for residential, commercial, and industrial solutions (assumptions exposed so clients can plug in their data).
-
Technology deep dives comparing ion‑exchange, salt‑free, and hybrid approaches, plus measurement technologies and software platforms.
-
Supplier benchmarking and scorecards (commercial readiness, technical capability, channel footprint, certification status).
-
Go‑to‑market playbooks for manufacturers, channel partners, and new entrants — including pricing strategies, warranty designs, and service contract templates.
-
M&A screening and value‑creation plans for private equity and strategic acquirers (synergy levers, integration risks, cultural fit diagnostics).
-
Regulatory compliance checklist and environmental risk matrix tied to procurement and product design choices.
To preserve the strategic edge of our subscribers, this introduction omits granular regional and application‑level split tables and other proprietary segment figures that are included in the full report. That segmentation — which drives prioritized market entry maps, channel economics, and target lists — is intentionally withheld here to encourage direct engagement with the full dataset.
How to use these insights in 2026 decision cycles
-
Product and R&D leaders should prioritize durability, analytics integration, and low‑resource regeneration features to win tenders where operational cost is evaluated over lifecycle.
-
Commercial teams must reframe value around measured outcomes (verified hardness reduction, water/salt savings) rather than device price alone — the measurement toolkit is now a sales enabler.
-
Procurement teams ought to require third‑party certification and demand transparent TCO analyses from suppliers to avoid lock‑in with sub‑optimal resin or control technologies.
-
Investors and M&A teams should focus on asset light service models and consumable annuities, while validating the target’s access to certified components and digital monitoring capabilities.
Conclusion — the strategic takeaways
Entering 2026, the water hardness removal market is a stable‑growth sector with clear pockets of premiumization. Companies that combine proven hardware with analytics‑driven operational economics and regulatory‑compliant chemistries will capture disproportionate value. The market’s mid‑level concentration creates both defensive moats for incumbents and tactical openings for focused challengers that can offer measurable, verifiable reductions in cost and environmental footprint.
For access to the full dataset, granular regional and application breakdowns, downloadable TCO models, and supplier scorecards that underpin these conclusions, please consult the complete PW Consulting Water Hardness Removal Market report. The full analysis contains the proprietary segment tables and playbooks necessary to operationalize the opportunities summarized above.
For detailed analysis of this topic, please visit the official page: Water Hardness Removal Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: White Cement Market Poised for 4.55% CAGR Through 2032
By pmarketresearch, 2026-07-30
White Cement Market 2026: Strategic Preview for Executive Decision-Making
As PW Consulting’s lead industry analyst, I present a high-resolution preview of our White Cement Market study — designed to equip C-suite leaders and investment committees with the strategic signposts needed for 2026 decision cycles. The global white cement market, measured at approximately USD 9,500 million in our 2025 base year, is set on a steady growth trajectory with a 2026–2032 CAGR of 4.55%, reaching roughly USD 12,930 million by 2032. This trajectory reflects resilient demand in architecture-led construction, selective industrial applications, and a structural rebalancing of supply chains driven by raw-material geography and sustainability regulation.
White Cement Market
Why this study matters for 2026 planning
-
Timing for capacity and capital allocation: Companies planning greenfield or grinding-capex in 2026 must align multi-year payback expectations with a mid-single-digit CAGR rather than high-growth assumptions; the market is growing but remains specialized and supply-constrained in key inputs.
White Cement Market -
Margin preservation under material scarcity: Ultra-low-iron limestone scarcity and TiO2 input price volatility create asymmetric downside to margins; firms that securitize feedstock or vertically integrate will materially de-risk earnings volatility.
White Cement Market -
Sustainability compliance is now a procurement filter: Updated Environmental Product Declarations (EPDs) and green-building specifications are shifting procurement to certified products. This is not a peripheral credential — it is increasingly table-stake for institutional buyers and large developers.
-
M&A and consolidation windows: With the market’s three- and five-firm concentration metrics indicating meaningful but incomplete consolidation (CR3 ~35%, CR5 ~45%), well-positioned acquirers can pursue bolt-on deals that deliver immediate technical synergies (e.g., grinding capacity, putty integration) without having to chase scarce clinker feedstocks.
Market dynamics shaping 2026 choices
-
Supply geology and feedstock economics: White cement’s technical requirement for ultra-low-iron limestone (Fe2O3 typically well below 0.5%) means feedstock availability is uneven and concentrated. Producers face recurring sourcing decisions — secure capex to develop captive pits, long-term offtakes, or premium purchases — each with distinct balance-sheet and margin trade-offs.
-
Color and process constraints limit fuel substitution: Many decarbonization levers applied across gray cement (alternative fuels, high SCM rates) are technically constrained in white cement production because color control and high kiln temperatures restrict substitution. This elevates the strategic value of focused sustainability investments (e.g., dedicated clinker lines, carbon capture retrofit feasibility studies) and explains why some players are allocating targeted sustainability budgets to white assets.
-
Regulatory and certification tailwinds: The expansion of EPD requirements for building certifications raises the premium for validated low-footprint products. Producers that can document life-cycle performance and secure EPDs will sustain access to large institutional buyers and new specification-driven segments.
-
Downstream product integration: Value capture via downstream formulations — notably putty and architectural finishes — is a demonstrable path to higher-margin exposure and customer lock-in. Recent transactions demonstrate strategic interest in integrated white cement–putty platforms.
Competitive landscape — who is shaping the arena
The white cement market is a mix of global groups, regional specialists, and family-owned niche players. Market concentration shows room for consolidation: the top three players account for roughly one-third of the market, and the top five under half, leaving opportunity for ambitious consolidators and specialist operators alike.
-
Industrial-scale incumbents expanding strategic depth: Players such as UltraTech Cement (Aditya Birla group) have pursued inorganic growth to secure downstream positions and grinding scale. Recent acquisitions and plant integrations indicate a playbook focused on synergies between white cement production and wall-putty manufacturing to capture value along the finishes chain.
-
Regional specialists with export reach: Producers like JK Cement (notably with North India grinding and putty integration) and Federal White Cement in North America demonstrate a hybrid model — regional production expertise combined with export-driven revenue. These firms leverage logistics competence and product formulations tailored to premium architectural specifications.
-
Middle East and Mediterranean players: Producers across the GCC and Mediterranean basins (including Ras Al Khaimah White Cement Company and multiple Egyptian and Omani firms) emphasize premium product positioning and compliance with international standards to serve regional construction and export corridors.
-
Emerging-market capacity additions and certification plays: Turkish and European producers are differentiating through sustainability credentials (EPDs), while select Chinese and ASEAN manufacturers compete on price and scale for commodity-style white cement flows.
Recent corporate moves exemplify these dynamics: significant capacity additions and acquisitions announced in 2025–2026 prioritized grinding scale, putty integration, and sustainability capex (including a multi-million-euro allocation to white cement sustainability projects). These actions are leading indicators for 2026 strategies — expect further defensive tie-ups between producers seeking feedstock security and downstream integration.
What our report delivers (practical, operational, decision-ready content)
PW Consulting’s white cement study is deliberately structured to convert strategic insight into executable actions. Highlights include:
-
Market sizing and forward scenarios: Modelled base-case, upside, and stress-case demand pathways across 2026–2032, financially stressed against feedstock-price shocks and sustainability capex scenarios.
-
Investment-readiness toolkit: Step-by-step templates for capex prioritization, NPV sensitivity analyses that embed raw-material concentration risk, and a pragmatic checklist for plant-commissioning phasing when grinding vs clinker vs downstream capacity is on the table.
-
Supply-chain risk maps: GIS-informed overlays of ultra-low-iron limestone deposits, kiln locations, and export terminals — enabling rapid scenario modelling for feedstock vulnerability and logistics optimisation.
-
Commercial playbooks: Go-to-market options for premium architectural segments, specification-led selling, and bundling strategies with wall-putty and finishing systems.
-
M&A screening and valuation heuristics: A shortlist of diligencable metrics and red flags for target screens, with example transaction structures (asset vs stock, earn-outs linked to EPD certification milestones) tailored to the sector’s realities.
-
Regulatory and sustainability roadmap: Practical guidance on achieving EPD compliance, retrofitting options, and quantifying the commercial upside from certified low-carbon product premiums.
Actionable recommendations for executives in 2026
-
Prioritize feedstock security: Negotiate long-term offtakes or invest selectively in captive low-iron limestone resources. The marginal value of feedstock assurance is rising faster than the cost of selective upstream capex.
-
Target downstream integration where economically viable: Wall-putty and finish systems are not merely ancillary products; they are profitable channels to secure specification loyalty. Evaluate bolt-on acquisitions or JV structures that shorten the route to market.
-
Invest in credentialing: Allocate project funding to secure EPDs and similar certifications. For institutional projects and certified green construction, EPDs can be a gatekeeper for specification — and a source of premium pricing.
-
Differentiate via product and service: For premium architectural demand, focus on whiteness consistency, batch traceability, and logistics reliability. Service layers (e.g., specification support, installer training) compound value and protect margins.
-
Design sustainability investments around thermal and color constraints: Since traditional alternative-fuel routes are limited, prioritize energy-efficiency retrofits, selective electrification feasibility studies, and partnerships for low-carbon clinker supply.
-
Use M&A to buy capability, not just volume: Given the current concentration profile, acquisition value is often realized through capability transfer (EPD-compliant processes, downstream formulations, export infrastructure) rather than pure capacity accumulation.
-
Embed price-risk hedging into commercial contracts: Given feedstock and TiO2 volatility, contractual terms that share input-cost movements or include periodic repricing clauses will protect operating margins.
Next steps — how to use this preview
This preview synthesizes the strategic implications we believe will drive successful 2026 outcomes. The full PW Consulting white cement study contains the granular datasets, regional and application segmentation, scenario-model files, company-level dashboards, and a downloadable supply-chain atlas that informed the summaries above. We intentionally reserve the detailed segment and country-level matrices for the full report to support confidential planning and M&A diligence.
For executive teams preparing capital budgets, M&A pipelines, or procurement strategies in 2026, our report is built as an operational playbook: not only diagnosing market direction but also supplying the tools to execute. Contact PW Consulting to access the complete dataset, model workbooks, and tailored advisory sessions that translate these insights into board-ready actions.
For detailed analysis of this topic, please visit the official page: White Cement Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com