

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Water Hardness Removal Market to Reach USD 14M by 2032 (5.47% CAGR)

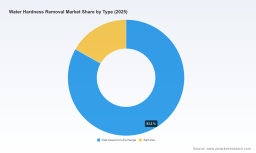
Water Hardness Removal Market — Strategic Imperatives for 2026
As PW Consulting’s lead industry analyst, I present an executive introduction to our new Water Hardness Removal Market study — a practical, decision‑grade analysis intended to inform corporate strategy, product roadmaps, and investment choices through 2026 and beyond. Grounded in a historical review (2020–2025) and a forward forecast window (2026–2032), the study synthesizes market sizing, competitive benchmarking, technology deep dives, and go‑to‑market playbooks to convert uncertainty around hard water treatment into strategic advantage.
Water Hardness Removal Market
Why this research matters in 2026
The global water hardness removal market has shown steady expansion over the past half‑decade, moving from the lower single‑digit millions in 2020 to an estimated market size in 2025 that establishes the base for near‑term plans. From that base, our forecast anticipates the market crossing a new threshold in 2026 and continuing to grow to the end of the forecast window in 2032, tracking at a compound annual growth rate (CAGR) of 5.47% for 2026–2032. For leaders deciding on plant investments, channel strategy, or M&A targets, these macro dynamics frame the timing and scale of opportunity.
Water Hardness Removal Market
Two structural takeaways emerge: first, demand growth is broad‑based — supported by residential replacement cycles, commercial retrofit activity, and industrial process needs — and second, market power is concentrated but not monopolistic: the top three suppliers account for roughly 40% of the market and the top five about 50%. That concentration creates both defensive barriers for incumbents and entry points for targeted challengers (service specialization, software‑enabled performance, or materials innovation).
Water Hardness Removal Market
Where growth is coming from — and what keeps it fragile
-
End‑market durability: Residential replacement cycles and increasing awareness of scale impacts continue to drive household purchases, while commercial and industrial buyers invest in preventative scale control to protect equipment and reduce downtime.
-
Technology evolution: Digital control systems, AI‑assisted regeneration, and improved analyzers are shifting value from the device alone to performance guarantees and software‑enabled operating cost reductions. Early movers that couple hardware with analytics capture higher lifecycle revenue.
-
Regulatory and environmental constraints: Certification standards and environmental programs influence permissible chemistries and system attributes. Compliance requirements create a baseline barrier to entry but also raise the value of certified suppliers.
-
Cost pressures: Resin quality, supply chain volatility for polymer feedstocks, and labour for maintenance/replacement remain meaningful components of total ownership cost. These inputs can compress margins unless manufacturers and service providers redesign business models toward consumable and service revenues.
Technology themes to prioritize
-
Ion‑exchange remains the workhorse. Salt‑based ion‑exchange systems continue to dominate installed base dynamics and aftermarket revenues due to proven performance and mature service ecosystems. However, salt‑free alternatives and hybrid concepts are gaining traction where regulatory or environmental concerns constrain salt discharge.
-
Measurement and diagnostics are increasingly strategic. The launch cadence for advanced hardness analyzers and digital titration kits underscores that better measurement reduces customer risk and unlocks premium service propositions (e.g., performance‑based contracts).
-
Smart regeneration and water‑efficient operation are value levers. Vendors integrating adaptive regeneration (including AI‑driven upflow brining and demand forecasting) materially reduce salt and water consumption — a tangible selling point in water‑sensitive regions and for utility contracts.
-
Materials and lifespan engineering matter. High‑quality ion‑exchange resins are the single largest determinant of long‑term system performance; sourcing strategies and resin lifecycle management should be treated as strategic supplier relationships, not commodity purchases.
Competitive landscape — profiles and strategic implications
Our competitive benchmarking centers on a mix of legacy equipment manufacturers, specialist treatment suppliers, and measurement companies. Below we summarize strategic positioning and recent moves that illustrate where incumbent advantage and disruption are concentrated.
-
Culligan (Illinois, United States) — A long‑standing manufacturer and service provider of water softening systems, Culligan combines hardware, installation, and subscription service models. Strengths include nationwide service networks and brand recognition; risks are legacy channel structures and the need to accelerate digital offerings. Recent: introduced a smart high‑efficiency water softener (Aqua Essential) with adaptive home‑needs adjustment, signaling a push to hybridize product and software value.
-
EcoWater Systems (United States) — Focused on advanced water softeners and smart regeneration controls, EcoWater is positioning around operational efficiency and resource reduction. Strengths are product innovation and efficiency claims; risks include differentiation in crowded consumer channels. Recent: emphasized AI‑powered upflow brining and smart regeneration to reduce salt and water use, an enabler for sustainability‑driven procurement.
-
Hach (United States) — A leader in analytical instrumentation, Hach supplies hardness analyzers and test kits that are increasingly integrated into treatment planning and performance verification. Strengths include laboratory reputation and reliable instrumentation; risks are margin pressure as handheld and low‑cost entrants proliferate. Recent: launched the HA‑DT digital titrator hardness test kit for precise measurement and treatment planning.
-
LaMotte Company (United States) — Specialist in field and laboratory testing strips and kits, LaMotte focuses on on‑site monitoring and system calibration. Strengths are market stickiness in test consumables; risks are commoditization and narrow product baskets. Recent: released Insta‑Test hardness test strips targeted to field users for quick calibration and monitoring.
-
Kinetico (Ohio, United States) — Known for non‑electric and advanced softening systems, Kinetico competes on reliability and design differentiation. Strengths include brand loyalty in certain channel segments and robust product engineering; risks include scaling service networks for broader reach.
-
Aquasana (United States) — A consumer‑focused filtration and softening provider that competes on convenience, bundle offerings, and direct channels. Strengths are D2C capabilities; risks are lower margins in marketplace channels.
-
GE Appliances (United States) — Integrates water softening into appliance ecosystems and benefits from OEM scale and distribution. Strengths include appliance channel access and brand trust; risks are coordination of R&D across larger corporate product portfolios.
Across these players, product launches and feature upgrades (smart regeneration, high‑precision analyzers, on‑site test strip improvements) indicate a market where differentiation is increasingly achieved through systems thinking — combining hardware, consumables, analytics, and service contracts.
Regulatory, input cost, and operational considerations
-
Certification standards matter. Water softeners and scale reduction devices are subject to NSF/ANSI 44 or IAPMO/ANSI Z601 during procurement and public tenders; non‑certified offerings face adoption barriers in institutional channels.
-
Environmental chemistry constraints. Programs such as EPA Safer Choice impose restrictions on certain chelating agents and surfactants, influencing formulation choices for softening adjuncts and scale inhibitors.
-
Raw material dependency. Premium ion‑exchange resins (styrene‑divinylbenzene based) determine longevity and performance; supply disruptions or quality downgrades directly affect lifecycle cost propositions.
-
Labour and maintenance costs. Resin replacement and routine maintenance constitute a non‑trivial share of ownership cost in residential and commercial deployments; service model redesigns (remote monitoring, predictive maintenance) are high ROI initiatives.
What the PW Consulting report delivers — pragmatic contents
This is not an academic exercise. Our report is built for operators, investors, and product leaders who must convert insights into action. Key practical outputs include:
-
Transparent market sizing and methodology (base year 2025; historical 2020–2025; forecast 2026–2032), including sensitivity scenarios around pricing and regulation.
-
Detailed TCO models for residential, commercial, and industrial solutions (assumptions exposed so clients can plug in their data).
-
Technology deep dives comparing ion‑exchange, salt‑free, and hybrid approaches, plus measurement technologies and software platforms.
-
Supplier benchmarking and scorecards (commercial readiness, technical capability, channel footprint, certification status).
-
Go‑to‑market playbooks for manufacturers, channel partners, and new entrants — including pricing strategies, warranty designs, and service contract templates.
-
M&A screening and value‑creation plans for private equity and strategic acquirers (synergy levers, integration risks, cultural fit diagnostics).
-
Regulatory compliance checklist and environmental risk matrix tied to procurement and product design choices.
To preserve the strategic edge of our subscribers, this introduction omits granular regional and application‑level split tables and other proprietary segment figures that are included in the full report. That segmentation — which drives prioritized market entry maps, channel economics, and target lists — is intentionally withheld here to encourage direct engagement with the full dataset.
How to use these insights in 2026 decision cycles
-
Product and R&D leaders should prioritize durability, analytics integration, and low‑resource regeneration features to win tenders where operational cost is evaluated over lifecycle.
-
Commercial teams must reframe value around measured outcomes (verified hardness reduction, water/salt savings) rather than device price alone — the measurement toolkit is now a sales enabler.
-
Procurement teams ought to require third‑party certification and demand transparent TCO analyses from suppliers to avoid lock‑in with sub‑optimal resin or control technologies.
-
Investors and M&A teams should focus on asset light service models and consumable annuities, while validating the target’s access to certified components and digital monitoring capabilities.
Conclusion — the strategic takeaways
Entering 2026, the water hardness removal market is a stable‑growth sector with clear pockets of premiumization. Companies that combine proven hardware with analytics‑driven operational economics and regulatory‑compliant chemistries will capture disproportionate value. The market’s mid‑level concentration creates both defensive moats for incumbents and tactical openings for focused challengers that can offer measurable, verifiable reductions in cost and environmental footprint.
For access to the full dataset, granular regional and application breakdowns, downloadable TCO models, and supplier scorecards that underpin these conclusions, please consult the complete PW Consulting Water Hardness Removal Market report. The full analysis contains the proprietary segment tables and playbooks necessary to operationalize the opportunities summarized above.
For detailed analysis of this topic, please visit the official page: Water Hardness Removal Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com