

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Diamond Core Drilling Market to Reach USD 335.98 Million by 2032, 6.6% CAGR

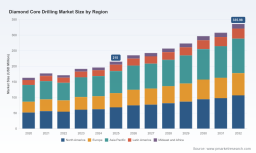
Diamond Core Drilling Market — Strategic Preview for 2026 Decision-Makers
Executive snapshot
Diamond core drilling sits at the intersection of exploration intensity, infrastructure ambition, and equipment innovation. Our PW Consulting Diamond Core Drilling Market study (base year 2025; historical window 2020–2025; forecast 2026–2032) finds the sector expanding at a mid-single-digit pace — a compound annual growth rate of 6.6% across the forecast horizon. After recovering from cyclical volatility during the early 2020s, the market reached a new inflection point in 2025. Under our central scenario, the market trajectory accelerates through 2032, underpinned by stronger exploration programs, selective infrastructure projects, and a rising attachment of automation and aftermarket services to core drilling packages.
Diamond Core Drilling Market
Why this matters for 2026 corporate strategy
For executives planning capex, procurement, M&A or product roadmaps in 2026, the study provides three tangible strategic values:
Diamond Core Drilling Market
- Demand-risk calibration: a validated top-line forecast sequence (2020–2025 historical series plus 2026–2032 projections) enables treasuries and strategy teams to stress-test budgets and financing under alternative recovery and commodity scenarios.
- Competitive positioning: a granular competitive framework (company archetypes, capability maps and aftermarket exposure) helps boardrooms decide whether to invest in organic R&D, pursue bolt‑on acquisitions, or partner for regional market access.
- Operational resilience: supplier risk matrices and scenario planning (including raw-material price shocks and labour constraints) allow procurement and operations leaders to redesign supply contracts, inventory buffers and skills pipelines ahead of regulatory changes.
Snapshot of the macro picture
Our market sizing shows a clear recovery and steady growth path: after the disruption years, the market reached a new baseline in 2025 and, under the central forecast, expands materially through 2032. This expansion is broad‑based — reinforced by both equipment and service lines — but characterized by shifting margin pools as aftermarket services, digital monitoring and automation capture increasing value. The market concentration metrics signal a moderately consolidated landscape: the top three and top five players account for meaningful, but not overwhelming, shares — a structure that supports both strategic partnerships and acquisitive plays.
Diamond Core Drilling Market
What’s inside the full PW Consulting study (practical deliverables)
Our report is built for decision-makers who need executable intelligence, not just descriptive charts. Core deliverables include:
- Top‑down market model (2020–2032) with transparent assumptions and sensitivity levers for commodity price, CAPEX cycles and exploration intensity.
- Scenario playbooks (three scenarios) that translate macro variance into P&L and capital requirements for OEMs, contract drillers and large exploration customers.
- Supply‑chain and cost‑curve analysis identifying key margin levers (raw materials, logistics, aftermarket mix) and stress points under a tungsten‑carbide price shock.
- Competitive benchmarking with company scorecards covering product breadth, digital capability, service footprint and balance‑sheet resilience.
- Commercial playbooks for go‑to‑market moves: pricing, bundling (equipment + service), channel strategy, and risk mitigation contracts.
- Regulatory and ESG impact assessment: water‑use requirements, waste handling mandates and quality certification expectations (e.g., ISO 9001 trends).
- Actionable M&A screens and integration checklists tailored to buyers and minority investors.
- Ready‑to‑use executive dashboards and downloadable data annex for board briefings and investor conversations.
Note: the public preview intentionally omits detailed regional and application-level splits and the underlying transaction-level datasets; those proprietary tables and raw-data exports are available in the full PW Consulting report.
Competitive landscape — what the leading players are doing
The market comprises a mix of large diversified industrials, specialist drill manufacturers and regional contract drillers. Below we distill the strategic posture of the most influential names covered in our analysis and the decision implications for counterparties and investors.
- Boart Longyear (South Jordan, Utah) — A specialist with deep service capability and a legacy brand in core drilling. Their DNA is service‑heavy, with a strategic emphasis on full‑cycle delivery to miners. For clients, Boart Longyear represents an attractive partner where project scale and geological complexity demand integrated drilling services. Strategic implication: competitors should evaluate service bundling or niche partnerships rather than head‑on price competition.
- Epiroc (Atlas Copco, Stockholm) — A diversified equipment OEM with scale in electrified drilling platforms, automation and aftermarket parts. Epiroc’s advantage is systems integration — electrified rigs, telematics and a global service network. Strategic implication: smaller OEMs and drill contractors should consider technology partnerships or white‑label arrangements to remain competitive in automation‑intensive tenders.
- Sandvik (Stockholm) — Engineering focus on high‑performance drilling tools and digital enhancements. Sandvik’s go‑to‑market pairs product innovation with channel reach. Strategic implication: incumbents must prioritize R&D pipelines in bit design and predictive maintenance to protect margin.
- Multi Power Products (Kelowna) — A nimble player with localized manufacturing and strong aftermarket service orientation. Their competitive edge is responsiveness to regional project cycles. Strategic implication: large OEMs can learn from their localized service models to reduce lead times in specific geographies.
- CS Unitec (Trumbull) — Specialist in handheld and portable systems. Their portfolio aligns with smaller projects and niche applications where mobility and low footprint matter. Strategic implication: clients with mixed project sizes should maintain a multi‑tier supply strategy to optimize cost and flexibility.
- DUSS (Neubulach, Germany) — German engineering with strong custom and specialist rigs. DUSS is positioned to capture high‑value technical drilling work. Strategic implication: for complex geology projects, partner selection should weigh technical fit as heavily as price.
- Wuxi Geotec (Wuxi, China) — Cost‑competitive OEM with a strong regional footprint and aggressive aftermarket growth. Their presence pressures global OEM margins in price‑sensitive segments. Strategic implication: western OEMs should sharpen differentiation (durability, service, digital tools) or explore strategic JV/assembly partnerships in low‑cost regions.
- Refina (UK) — Specialist in high‑precision coring equipment and tooling. Strategic implication: opportunities exist to co‑develop high‑value tool sets with labs and exploration companies focused on critical minerals.
- Cascade Environmental (US) — Service firm focused on environmental drilling and sampling. Their growth reflects increasing demand for compliance‑centric projects. Strategic implication: environmental service capabilities are a value add in mixed tenders and can be a differentiator in heavily regulated markets.
- Godbe Drilling (US) — Regional contract driller with operational flexibility and project execution strengths. Strategic implication: clients seeking speed to first core should evaluate regional contract drillers with proven execution metrics.
The market’s CR3 and CR5 figures reflect a meaningful leadership bloc, but significant share remains accessible to regional specialists and innovative new entrants — creating attractive M&A and partnership corridors for ambition players.
Recent market signals — what to watch
- Mid‑2025 saw several notable drilling contracts and program commencements, signaling active ground programs among juniors and listed explorers.
- Industry associations continue to shape standards: the Canadian Diamond Drilling Association’s recent convention and the International Diamond Drilling Association’s updated standards (2023) have accelerated standardization on safety and quality.
- Raw‑material shocks — notably a spike in tungsten‑carbide pricing in 2026 — are already compressing bit‑level margins and forcing OEMs to reassess procurement strategies.
Regulatory, supply and labour headwinds
Four structural frictions deserve board attention in 2026:
- Standards & certification: ISO 9001 and sector norms are becoming de facto entry criteria, raising the bar for smaller contractors.
- Environmental mandates: water efficiency and waste‑management requirements are increasing operational cost and capex for drilling projects, particularly in sensitive jurisdictions.
- Raw‑material volatility: bit component price spikes can erode margins quickly unless firms hedge, diversify suppliers or redesign consumable mixes.
- Skilled labour shortage: an industry‑wide shortage of experienced operators is accelerating demand for automation and remote‑operated systems — a double‑edged sword that raises capital intensity while lowering unit operating risk over time.
How to use this preview in 2026 — an actionable checklist
- Immediate (0–6 months): Reassess supplier contracts for tungsten and carbide components; launch a skills audit and a pilot automation program in at least one high‑cost site.
- Medium term (6–18 months): Reprice bids to reflect increased compliance costs; consider bolt‑on targets with complementary service footprints in priority geographies.
- Scenario planning: Model P&L impacts under raw‑material shock and regulatory tightening scenarios provided in the report; set trigger thresholds for capex deferral or accelerated M&A activity.
- Risk monitoring: Implement the PW Consulting drilling market dashboard (included in the full report) to track lead indicators such as new drill program announcements, tender pipelines and key input prices.
Next step — where to get the full intelligence
This preview surfaces the strategic levers and risks shaping the diamond core drilling market in 2026. The full PW Consulting Diamond Core Drilling Market report contains the detailed regional and application breakdowns, proprietary company scorecards, pricing curves, and downloadable datasets required to operationalize the insights above. These detailed tables and the underlying transaction‑level data are purposefully restricted to the full report to preserve the competitive integrity of our primary research.
For boards, strategy teams and operational leaders preparing for 2026, this study is a practical decision tool: it combines defensible market forecasts, competitor playbooks, and direct implementation checklists to convert market intelligence into competitive advantage.
For detailed analysis of this topic, please visit the official page: Diamond Core Drilling Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com