

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting: 8‑bit Automotive MCU Market at US$850 Million in 2025 — Asia Pacific Leads with US$425M; Poised to Reach US$1,010.38 Million by 2032 at 2.5% CAGR (Top 3 Hold 68.5%)
By pmarketresearch, 2026-08-18
PW Consulting: Strategic Brief — 8‑bit Automotive MCU Market Outlook to 2032
As automotive architectures continue to bifurcate between cost‑sensitive, highly integrated vehicle subsystems and compute‑intensive domain controllers, 8‑bit microcontrollers (MCUs) remain an indispensable element of the automotive electronics stack. PW Consulting’s new market research report — base year 2025, historical coverage 2020–2025, and forward projections through 2026–2032 — delivers the strategic intelligence executives will need to make high‑stakes product, sourcing, and M&A decisions in 2026. Built on an evidence base of supplier filings, tier‑1 OEM interviews, design‑win tracking, and production validation, the analysis highlights a measured but durable market expansion at a 2.5% CAGR.
Methylmalonic Acidemia Treatment Market
Why 2026 Is a Pivotal Year for Automotive MCU Strategy
-
Regulatory and safety expectations are converging toward a stricter certification posture: AEC‑Q100 Grade 0 qualification and ISO 26262 functional safety requirements (commonly up to ASIL B for many 8‑bit use cases) are now baseline expectations for new designs. This increases the qualification burden — and therefore the switching costs — for OEMs and Tier‑1s.
High Precision Inductors Market -
Supply‑chain normalization post‑2021 volatility has stabilized lead times for automotive‑grade devices, but geopolitical dynamics are accelerating regionalization pressures that favor onshore or nearshore sourcing in Asia for many OEM supply chains.
Meat Certification Market -
Technological choreography between 8‑bit MCUs and higher‑order controllers (16/32‑bit) is increasingly critical. Cost optimization, software continuity, and lifecycle support now shape not only component selection but also architecture roadmaps and procurement strategies.
Market Trajectory at a Glance
PW Consulting’s topline modelling shows a steady, resilient expansion of the 8‑bit automotive MCU market. In USD (Million), the market progressed from approximately 810 in 2023 to 830 in 2024 and 850 in 2025 (base year). Our forecast projects growth to about 871.25 in 2026 and continues to expand to roughly 1,010.38 by 2032, reflecting a compound annual growth rate of 2.5% for the forecast period.
What this trajectory signals for corporate decision‑makers is a mature market with incremental unit growth and sustained aftermarket relevance. Investment decisions should therefore be guided by margin preservation, long‑tail service economics, and the ability to sustain multi‑year qualification and production commitments rather than by chasing rapid volume gains.
What the Report Delivers — Operational, Decision‑Ready Insights
-
Actionable scenarios for procurement and dual‑sourcing to reduce supplier concentration risks while protecting cost targets.
-
Qualification and certification roadmaps that align engineering timelines with OEM launch calendars for AEC‑Q100 Grade 0 and ISO 26262 compliance.
-
Supply‑chain stress tests and contingency playbooks that quantify inventory exposure and outline tactical mitigation measures for localized disruptions.
-
Technology migration models that evaluate the commercial tradeoffs between retaining 8‑bit platforms and migrating to 16/32‑bit solutions across functional domains.
-
A vendor scorecard framework and an M&A playbook to prioritize targets and partnership structures that strengthen product portfolios or regional manufacturing footprints.
-
Lifecycle and obsolescence management protocols to preserve aftermarket revenues and minimize redesign costs over multi‑year programs.
In keeping with the “prequel” purpose of this release, the report contains detailed regional, application and type‑level splits and revenue overlays, which are intentionally not reproduced here so decision‑makers will consult the full deliverable for granular allocations and model assumptions.
Competitive Landscape — Key Players and Strategic Postures
The 8‑bit automotive MCU market is concentrated, with leading vendors commanding substantial installed bases and ecosystem depth. PW Consulting estimates that the top three vendors control a significant majority of market share, and top five concentration rises further — a structure that favors established suppliers that combine automotive qualification, long product lifecycles, and broad software/ecosystem support.
-
Microchip Technology (Chandler, AZ) — Microchip remains a dominant force in automotive‑grade 8‑bit MCUs, offering AEC‑Q100 Grade 0 qualified PIC and AVR families with CAN/CAN FD support and functional safety credentials up to ISO 26262 ASIL B. Their portfolio targets body, HMI, and sensor applications where thermal resilience and robust communication interfaces are critical.
-
STMicroelectronics (Geneva) — ST continues to actively support its STM8AF/STM8AL series, expanding packaging and ecosystem tools to sustain design wins in body and powertrain contexts. Recent portfolio updates through early 2026 underscore ST’s commitment to the automotive 8‑bit segment as part of a broader multi‑architecture automotive strategy.
-
NXP Semiconductors (Eindhoven) — NXP’s legacy S08 and HC‑series remain relevant in cost‑sensitive applications. Their advantage lies in long‑term automotive qualifications and depth across CAN‑based networked subsystems that remain common in production fleets.
-
Silicon Laboratories (Austin) — Silicon Labs brings high‑integration 8‑bit devices with features like integrated 12‑bit ADCs in compact packages, appealing to sensor and compact control applications that demand analog performance in constrained BOMs.
-
Renesas Electronics (Tokyo) — Renesas’ RL78 family (8/16‑bit hybrids) addresses low‑power, automotive‑qualified needs for body control and lighting domains, benefitting from Renesas’ deep relationships with OEMs and Tier‑1s.
-
Infineon Technologies (Neubiberg) — Infineon maintains legacy XC800 alternatives for demanding applications, with a focus on industrialization and high‑reliability deployments.
Recent product availability and portfolio refreshes from several of these vendors in early 2026 confirm that incumbents are prioritizing ecosystem continuity, extended temperature ranges (up to 150°C), CAN FD capabilities, and functional safety flows rather than radical architectural displacement.
Strategic Implications for OEMs, Tier‑1 Suppliers and Semiconductor Vendors
-
For OEMs: Lock in long‑lead qualification windows early. Because certification and production stability drive switching costs, early alignment on supplier roadmaps, common‑software strategies, and obsolescence clauses is essential to protect program economics.
-
For Tier‑1s: Prioritize supplier consolidation with contingency agreements. The market’s concentration creates both dependency and bargaining leverage. Use that leverage to negotiate stronger lifecycle support and cost pass‑through protections.
-
For Semiconductor Vendors: Differentiate through systems‑level support — expand dev‑tool chains, certify reference designs, and package safety and quality services to commoditize switching pain for OEMs. Consider regional capacity and service nodes to address geopolitical localization pressures in Asia.
-
Across the ecosystem: Adopt hybrid migration strategies. Preserve 8‑bit platforms where they make economic sense (lighting, simple body functions, sensors) while accelerating software portability and abstraction layers for functions that will ultimately migrate to 16/32‑bit domains.
Methodology, Validation and What We Withhold in This Brief
Our quantitative projections rely on historical shipment and revenue reconciliations from 2020–2025, validated against supplier disclosures, design‑win trackers, and OEM program roadmaps. Forecast scenarios blend bottom‑up module demand (per vehicle BOM modeling) with macroeconomic and vehicle production forecasts, and include sensitivity analysis for lead‑time disruptions and policy shifts.
To preserve the strategic utility of this brief while protecting proprietary analytics, we have intentionally withheld the granular regional, application, and product‑type revenue splits that appear in the full report. These withheld elements include modelled allocations that directly inform supplier selection and competitive pricing strategies; they are available only in the complete report package to ensure decision‑makers can act on fully attributable, auditable figures.
How to Use the Report for 2026 Decision‑Making — A Tactical Roadmap
-
Integrate the report’s qualification roadmap into your 2026 program cadence: map AEC‑Q100 and ISO 26262 gates to engineering milestones and procurement contracts.
-
Run the included supplier stress test against your inventory and production plan to quantify risk exposure and identify where buffer stocks or alternate sourcing are cost‑effective.
-
Apply the vendor scorecard to upcoming RFQs: weigh long‑term support and software ecosystem advantages more heavily than short‑term BOM savings for components with multi‑year production lives.
-
Pursue targeted partnerships or bolt‑on acquisitions if your strategy requires immediate expansion of automotive‑grade 8‑bit product lines or regional manufacturing presence.
Conclusion & Access
For organizations that must balance cost, reliability, and long‑term program stability, PW Consulting’s 8‑bit Automotive MCU Market report provides the disciplined, operational intelligence necessary to prioritize investments in 2026 and beyond. The market is growing steadily but not explosively — success will accrue to those who manage qualification timelines, supplier concentration, and technology migration with rigor.
To obtain the full report, including the detailed regional and application splits, vendor profiles with revenue estimates, and the complete suite of tactical templates and scenario models, please visit PW Consulting’s research portal or contact our client services team for enterprise licensing and bespoke advisory engagements.
For detailed analysis of this topic, please visit the official page: 8-bit Automotive Microcontrollers (MCU) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Fast Electric Rolling Door Market Poised for a 7.85% CAGR Through 2032
By pmarketresearch, 2026-08-18
Fast Electric Rolling Door Market: Strategic Imperatives for 2026 Decision‑Makers
As organizations recalibrate facility operations for energy efficiency, throughput, and resilience, fast electric rolling doors have moved from a niche operational purchase to a strategic asset. PW Consulting’s new Fast Electric Rolling Door Market report (base year 2025) synthesizes five years of historical tracking (2020–2025) with scenario‑based forecasts through 2032. The headline: the addressable market is entering a sustained growth phase in 2026, with a compound annual growth rate (CAGR) of approximately 7.85% over the forecast window. This briefing highlights the report’s strategic value for 2026 planning while intentionally preserving the granular segmentation intelligence that is available only in the full report.
High Purity SiC Parts Market
Why 2026 is a Pivotal Year
-
Policy and procurement cycles are aligning. Energy efficiency mandates (notably provisions under 10 CFR 433 in the U.S.) and incentive structures have accelerated procurement timelines for solutions that reduce air exchange and thermal loss—attributes inherent to high‑speed rolling door systems.
EV Harness Market -
Input‑cost volatility, particularly in steel and aluminum markets, has created both risk and opportunity. Manufacturers and procurement teams that act in 2026 with hedging, design substitution, or pass‑through pricing strategies will materially outperform peers on margin stability.
Marine Wire Rope Market -
Technology differentiation (controls, impact resilience, modular designs) is reshaping total cost of ownership. Buyers are increasingly valuing lifecycle performance and uptime rather than lowest first‑cost, changing vendor selection criteria.
Market Trajectory: The Numbers You Need to Know
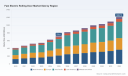
PW Consulting’s top‑level model shows a clear recovery and re‑acceleration in 2026 following steady growth in the prior half‑decade. The report’s base‑year analysis (2025) and forward projections through 2032 reflect a market expanding at roughly 7.85% CAGR—supporting strategic investment cases for manufacturers, integrators, and large end‑users contemplating fleet refreshes, retrofit programs, or new facility specifications.
Importantly, while headline growth is robust, the market is not uniform: material selection, door architecture (fabric vs. rigid constructions), and application context (logistics, cold chain, manufacturing) deliver distinct risk/reward profiles. PW Consulting’s full dataset provides the granular segmentation that procurement and product teams depend on; here we outline the implications without disclosing the proprietary splits.
Operational and Commercial Implications for 2026
-
Procurement strategy: Adopt a hybrid sourcing approach. Locking long‑lead material contracts where feasible mitigates exposure to steel price swings—historical analysis in the report shows price fluctuations can be large enough to erode margin or require price reset clauses in supplier contracts. Tactical use of multi‑year agreements with indexed adjustments is recommended for high‑volume programs.
-
Product planning: Prioritize modular control systems and retrofit‑friendly architectures. These features drive faster payback via reduced installation time and lower downtime costs—an increasingly critical purchase justification in logistics and cold‑storage environments.
-
Energy & sustainability: Align product roadmaps with energy efficiency standards and incentive windows. ENERGY STAR and other local programs have created near‑term financial incentives that change the ROI calculus for upgraded door systems; capital budgeting in 2026 should explicitly model these credits and the operational savings from reduced air exchange.
-
Pricing & margin management: Factor in input tariff risk. Recent tariff actions on steel and aluminum materially increased OEM cost bases; scenario planning with discrete tariff and price‑pass‑through assumptions should be mandatory in 2026 pricing reviews.
Competitive Landscape: Who Matters and Why
The fast electric rolling door market combines global engineering leaders, specialized regional fabricators, and an active aftermarket ecosystem. Competitive intensity varies by application: high‑throughput logistics and cold‑chain segments favor high‑performance, certified systems from established global suppliers, while localized security and hurricane‑zone applications remain the domain of regionally focused manufacturers.
-
Rytec Doors (Jackson, WI): Reputation for high‑performance commercial and industrial doors with deep installed base strength. Their recent product updates emphasize energy efficiency and impact resistance—key differentiators for warehouse operators prioritizing uptime and thermal control.
-
Albany Doors (Kenosha, WI): A leader in fabric and high‑speed roll‑up solutions. Albany’s product breadth and focus on logistics applications make them a go‑to for integrators specifying high‑duty‑cycle systems.
-
Hörmann (Steinhagen, Germany): A European heavyweight with advanced control platforms and a recent expansion into Southeast Asia, broadening local production and shortening supply chains for regional customers.
-
EFAFLEX (Bruckberg, Germany): Technology leader known for ultra‑fast spiral and vertical doors. Their recent Next‑Generation product family adds calibrated variants for premium, eco, and basic tiers—an explicit move to segment the value curve more finely.
-
Rite‑Hite (Milwaukee, WI): Known for robust fabric high‑speed doors and proprietary auto re‑feed mechanisms, appealing to high‑traffic dock operations seeking minimal downtime.
-
Cornell Iron Works , Cookson Door Products , Janus International , and Rolling Door Manufacturing : These firms illustrate the market’s regional depth—offering security‑grade, code‑compliant products (including hurricane‑zone solutions) and local installation/service networks that matter for many end users.
Market concentration is meaningful but not prohibitive: a combination of global champions and numerous niche players creates opportunities for both scale‑driven incumbents and agile specialists. M&A prospects often center on acquiring manufacturing scale in lower‑cost regions, adding controls/IP, or expanding service footprints—strategies reflected in recent transactions and product launches.
Recent Industry Moves and What They Signal
-
EFAFLEX’s November 2025 Next‑Gen rollout stratifies offerings into premium/eco/basic variants—indicating a shift toward configurable product platforms to win across different buyer personas.
-
Rytec’s 2025 line updates focusing on energy and impact resistance underscore the market premium for durability and lifecycle efficiency in warehouse environments.
-
Hörmann’s Southeast Asia acquisition (2025) demonstrates the growing importance of local production and shorter logistics for lead‑time‑sensitive projects.
-
New entrants and product launches in 2026 (e.g., ASTA America’s high‑speed rolling steel series) suggest continued innovation in speed and durability metrics—pressuring legacy platforms to modernize.
Risk Factors to Watch in 2026
-
Raw material volatility: Historical data points to material cost spikes that can distort annual P&L. The report includes sensitivity tables and procurement playbooks to stress‑test supplier exposure.
-
Regulatory shifts: Evolving energy codes and local standards (including tax credit expirations or renewals) can materially change adoption economics. Decision‑makers should align replacement cycles with policy windows.
-
Installation and aftermarket service: Field service networks are a competitive moat. Companies that underinvest in installation training and local service risk losing whole‑of‑life revenue streams.
What the PW Consulting Report Delivers (Practical Components)
-
Proprietary market sizing and 2026–2032 forecasting model (top‑level numbers highlighted here), with configurable scenario engines for material pricing and policy outcomes.
-
Supplier and technology matrix mapping product archetypes to application economics—designed to support fast vendor shortlists and RFP templates.
-
Procurement playbook including contract language samples, indexation strategies, and total cost of ownership calculators tailored to door architecture and duty cycle.
-
Go‑to‑market and channel strategies for manufacturers seeking to expand into new regions or verticals, plus M&A diligence checklists for strategic acquirers.
-
Service and aftermarket optimization guidance—how to structure SLA tiers, spare‑parts stocking policies, and digital monitoring to uplift recurring revenue.
Recommendations for 2026 Corporate Planning
-
For OEMs: Invest in modular control platforms and flexible manufacturing footprints now; the ability to deliver localized variants and rapid service will be a key differentiator.
-
For facility owners/operators: Prioritize lifecycle cost and energy impact in procurement decisions; model incentive capture (where available) and align rollouts with energy‑code timelines.
-
For investors and acquirers: Target bolt‑on plays that add service density, controls IP, or low‑cost regional manufacturing—these levers accelerate payback in a market growing at ~7.85% CAGR.
Next Steps
This briefing has highlighted the strategic contours for 2026 without revealing the segmented market intelligence that drives tactical decisions. PW Consulting’s full Fast Electric Rolling Door Market report contains the detailed regional/application splits, supplier share tables, and customizable financial models that procurement, product, and M&A teams require to act decisively this year. For organizations that need to convert the 2026 growth window into measurable advantage, the full report and accompanying Excel model are essential operational tools.
Contact PW Consulting to access the complete report package, tailored briefings, and scenario workshops that translate market projections into executable plans for 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Fast Electric Rolling Door Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Polylaurolactam Market to Expand at 5.6% CAGR — From USD 1,485.5 Million in 2025 to USD 2,175.32 Million by 2032
By pmarketresearch, 2026-08-18
Worldwide Polylaurolactam (PA12) Market — Strategic Briefing for 2026 Decision-Makers
PW Consulting’s latest Worldwide Polylaurolactam Market study (base year 2025, forecast 2026–2032) consolidates proprietary data, primary interviews, and supply-chain modeling to deliver an executive-grade roadmap for commercial, procurement, and R&D leadership. Our analysis shows the PA12 market entering its next phase of steady expansion, with the global revenue base near the mid‑point of the last decade and a compound annual growth rate (CAGR) of 5.6% built into our 2026–2032 projections. For organizations that rely on PA12 for high‑performance plastics—automotive, industrial and electronics OEMs, material suppliers, and compounders—this report is a practical instrument for calibrating 2026 budgets, capacity plans, and strategic partnerships.
Driver Training Management Software Market
Why PA12 Matters in 2026
Polylaurolactam (commercially known as PA12 or Nylon 12) occupies a premium position in polymer portfolios: it combines low water absorption, chemical resistance and dimensional stability with process flexibility across extrusion, injection molding, and powder/filament systems used in additive manufacturing. These material characteristics are driving sustained demand in segments where performance and regulatory compliance outweigh raw material cost pressures. Our market model traces the sector’s recovery from early‑decade volatility into a structurally healthier landscape as electrification, lightweighting and additive manufacturing adoption continue to unlock new mid‑cycle demand.
Vehicle-Mounted Ni-Mh Battery Market
Headline Market Dynamics
- Measured growth path: The global PA12 market is modeled to grow at a steady mid‑single digit CAGR through 2032 under our base case. That trajectory reflects a mix of incremental substitution in automotive systems, capacity additions in Asia, and scaling of specialty grades for 3D printing and medical applications.
- High supplier concentration: Market concentration is pronounced: the top three suppliers control a large majority of global shipments, while the top five extend that dominance substantially. This concentration shapes pricing power, contract terms, and the pace at which new grades reach commercial scale.
- Raw material volatility and supply risk: Laurolactam—the monomer feedstock for PA12—remains sensitive to upstream petrochemical dynamics. Our analysis shows recent softening in laurolactam prices in late 2025, and direct dependencies on butadiene-derived intermediates create ongoing exposure to feedstock cycles.
- Sustainability as a procurement vector: OEM targets for sustainable polymer content are elevating the strategic importance of bio‑based PA12. Automakers and industrial buyers increasingly require supply‑chain transparency and a credible roadmap to 20–30% sustainable polymer incorporation by 2030, creating both risk and opportunity for incumbent and emerging suppliers.
Competitive Landscape — What Matters to Buyers and Investors
The competitive map is defined by a handful of vertically integrated producers and specialty polymer houses. These players combine scale production, global logistics footprints, and grade portfolios spanning extrusion, injection molding, and powder systems for additive manufacturing. In practice, this yields three commercial realities for market participants in 2026:
Worldwide Outdoor LED Street Lighting Market
- Negotiation leverage is asymmetric: large, multi‑grade suppliers control continuity and premium grade availability, which matters when qualifying parts for safety‑critical applications.
- Regional capacity expansions—particularly in Asia—translate into pricing pressure for commodity grades while premium, performance‑differentiated formulations retain margin resiliency.
- Sustainability and traceability initiatives are becoming core competitive differentiators; companies that can certify bio‑content and demonstrate low‑carbon supply chains command premium buyer attention.
Among the companies we profile in detail, several represent archetypes buyers will want to benchmark: a global specialty polymer leader with world‑scale production; a chemical group that couples PA12 with bio‑based product lines; a European engineering polymer house focused on high‑performance compounds; a Japanese producer oriented to precision molding grades; and a large integrated Chinese producer rapidly scaling domestic capabilities. Recent market movements exemplify these dynamics—price adjustments by an Asian integrated player in early 2026 and public sustainability positioning by a leading European producer during 2025 have already shifted negotiation postures across the supply base.
Strategic Implications for 2026 Planning
- Procurement and contract strategy: Locking tiers of security and price protection for core PA12 grades should be prioritized for programs with long qualification cycles. Consider blended sourcing across a global leader and regionally advantaged producers to manage supply continuity versus cost.
- Sourcing for sustainability: Establish supplier scorecards that weight verified bio‑content, carbon footprint disclosures, and third‑party certification. Early partnerships with bio‑PA12 pilots can secure pathway advantage as OEM mandates crystallize.
- Product and process R&D: Invest selectively in compound development and additive manufacturing feedstock qualification. Materials that shorten cycle time, reduce scrap, or enable lightweighted assemblies will capture disproportionate value.
- M&A and JV playbook: For mid‑sized polymer converters and specialty chemical investors, bolt‑on acquisitions of capacity or technical compounding assets offer rapid access to growth. Our report includes scenario analysis for acquisitive strategies under varying price and demand assumptions.
- Risk management: Hedging laurolactam exposure and maintaining visibility on butadiene markets should be part of treasury and procurement roadmaps. We model stress scenarios that quantify margin impact from feedstock shocks across product lines.
What the Full Report Contains — Practical Tools Inside
PW Consulting’s study is designed as an operational playbook rather than a high‑level snapshot. Clients receive:
- Proprietary demand and supply models with editable assumptions for scenario planning (price, adoption, capacity additions).
- Supplier scorecards and a negotiation checklist tailored to PA12 grade families and supply risks.
- Technology deep dives comparing extrusion, injection and powder system economics for manufacturers and AM users.
- Regulatory and sustainability roadmaps mapping OEM targets to material pathways, plus recommended actions for procurement and product development teams.
- An M&A and investment appendix containing valuation sensitivities and integration risk factors for target archetypes across regions.
To preserve commercial value and follow the pre-release principle, the public briefing intentionally omits the detailed regional, grade and application split tables; those granular datasets and the interactive model are available to subscribers and licensed purchasers on the report portal.
Near‑Term Signals and Monitoring Dashboard
For 2026 execution, we recommend establishing a simple monitoring dashboard of five leading indicators that correlate closely with PA12 market condition and price direction:
- Spot and contract laurolactam price trends, particularly feedstock differentials tied to butadiene cycles.
- Capacity announcements and debottlenecking projects in major regional hubs.
- Orderbook and design wins in target end‑markets—especially high‑volume automotive programs and AM series production ramps.
- Supplier actions on sustainability: publication of bio‑PA12 supply commitments, trade‑off analysis between biobased content and lifecycle impacts.
- Major procurement actions and public price notices from vertically integrated producers as they adjust to feedstock shifts.
We continue to watch two high‑impact developments closely. First, upstream raw material behavior: the recent softening in laurolactam pricing observed in Q3–Q4 2025 reduced near‑term cost pressure, but the dependency on petrochemical intermediates leaves the market exposed to renewed volatility. Second, capacity and policy: China’s ongoing expansion of laurolactam and Nylon 12 production capacity is reshaping regional competitiveness and will influence feedstock flows and export dynamics over the next 24–36 months.
Final Recommendation for Decision‑Makers
As PA12 demand broadens across established and emerging applications, the strategic challenge for 2026 is balancing security of supply with margin preservation and sustainability compliance. Our core recommendation: adopt a dual approach—lock operational continuity for core grades through multi‑tiered agreements with leading global suppliers, while investing in targeted development of higher‑margin, sustainability‑aligned formulations and additive manufacturing feedstocks.
PW Consulting’s Worldwide Polylaurolactam Market report equips executives with the market intelligence, supplier benchmarking and executable playbooks needed to operationalize that approach. For access to the full dataset, regional and application splits, and the interactive forecast model, please visit the report portal where licensing options and tailored consulting engagements are available.
For detailed analysis of this topic, please visit the official page: Worldwide Polylaurolactam Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide FR4 Plates Market Forecast to Grow at 6.15% CAGR, Reaching USD 18,982.35 Million by 2032
By pmarketresearch, 2026-08-18
Worldwide FR4 Plates Market 2026: Strategic Imperatives from PW Consulting’s Latest Industry Brief
PW Consulting’s newly released market research brief on the Worldwide FR4 Plates Market provides a focused, decision-ready roadmap for executives preparing budgets, supply-chain strategies, and product roadmaps in 2026. Built on a multi-year historical series and a seven-year forecast horizon, the study synthesizes macroeconomic trends, raw-material dynamics, regulatory drivers, and a practical competitive playbook—while reserving the granular segmentation tables for subscribers who require the full dataset and modeling assumptions.
Polyurethane Intravenous Indwelling Needle Market
Market at a Glance: Growth Trajectory and What It Means for 2026 Decisions
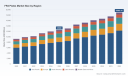
The FR4 plates market has demonstrated steady expansion over the past half-decade, with market value rising from the lower single-digit billions in 2020 to USD 12.5 billion in our base year of 2025. Our forecast work indicates robust, sustained growth through the projection window, with an embedded compound annual growth rate (CAGR) of 6.15% across the 2026–2032 period and a market size approaching USD 19.0 billion by 2032. For leadership teams, these aggregate metrics translate into three immediate imperatives for 2026 planning: (1) align capacity and product mix investments to a multi-year growth profile rather than one-off demand shocks; (2) incorporate volatile input-cost scenarios into capital allocation and pricing frameworks; and (3) prioritize regulatory compliance and product reformulation where required to preserve market access and margins.
Worldwide Microtube Storage Racks Market
Why This Report Matters to 2026 Strategy
- Actionable scenario modeling: The brief includes near-term and base-case scenarios that quantify revenue and margin sensitivities under alternative raw-material price paths and demand-shock scenarios—enabling CFOs and supply-chain leaders to stress-test 2026 P&L projections without building bespoke models.
- Supplier playbook and scorecards: We evaluate leading producers across technical capability, geographic footprint, capacity flexibility, and compliance preparedness—equipping procurement teams with negotiation levers and short-listed alternative suppliers for rapid sourcing decisions.
- Regulatory compliance matrix: A practical mapping of RoHS/REACH implications, plus reformulation pathways for halogen-free and lead-free variants, helps R&D and product teams prioritize reformulation investments to unlock or retain key market segments.
- Go-to-market and pricing tactics: Commercial teams receive tested approaches for passing through feedstock-driven cost increases while protecting share—ranging from indexed pricing agreements to value-based bundling for differentiated laminates.
Key Market Dynamics Shaping 2026 Outcomes
The 2026 competitive landscape for FR4 plates is being shaped by three converging vectors:
Feeding Nutrition Bag Market
- Feedstock price volatility: Input-cost pressures are material. For example, regional epoxy resin pricing shows divergent levels—industry data from March 2026 records roughly USD 2.13/kg in Northeast Asia versus approximately USD 4.63/kg in Europe—creating significant cross-regional cost differentials. Copper price swings and announced increases in fiberglass feedstock have already triggered price adjustments among laminate producers in 2025, and further volatility is baked into our scenarios for 2026.
- Regulatory-driven reformulation: RoHS and REACH remain binding constraints for global electronics applications. The combined effect of these regulations has accelerated demand for halogen-free and lead-free resin systems; companies that can demonstrate robust compliance and validated supply chains will secure a pricing premium and preferential access to OEM programs.
- Demand composition evolution: While traditional consumer-electronics demand remains a large end-market driver, the fastest-growing applications are tied to higher-specification use cases—those that require higher Tg materials, improved dielectric stability, or tighter reliability testing for automotive and industrial electronics. This favors suppliers that can offer differentiated formulations and proven reliability records.
Competitive Landscape: Profiles and Strategic Postures
The market exhibits a measured level of concentration, with leading groups holding a meaningful share of global capacity while a sizeable tail of regional and specialized producers competes on price, niche capability, or service. Our report’s competitive chapter builds operator profiles, recent strategic moves, and likely near-term playbooks. Highlights include:
- Isola Group (Chandler, AZ, USA): Global specialist in high-performance FR-4 epoxy laminates and prepregs. Recent product-documentation updates and reinforced RoHS declarations signal a push to shorten qualification cycles with OEMs and to support lead-free assembly programs—an advantage when bidding for multilayer PCB opportunities requiring validated materials.
- Ventec International Group (Taoyuan County, Taiwan): A broad product portfolio spanning standard and higher-spec laminates, with capabilities for halogen-free variants. Their geographic proximity to major EMS and PCB clusters supports rapid supply and qualification timelines—critical for customers seeking reduced lead times.
- Kingboard Laminates/Kingboard Chemical (Hong Kong/China): A vertically integrated producer that has demonstrated pricing agility; December 2025 pricing adjustments in response to copper and fiberglass feedstock costs underscore how upstream integration and feedstock sourcing strategies influence commercial position.
- Nan Ya Plastics Corporation (Taipei, Taiwan): Strong emphasis on environmental compliance and a broad Tg range suitable for consumer and automotive electronics, positioning them well as OEMs demand higher reliability and regulatory transparency.
- Regional and specialty players (U.S. and China-based manufacturers and distributors): Companies such as Current Inc., Hebei JingHong, Jiujiang Leadcomp, and distributors like Professional Plastics supply electrical-grade sheets, cut-to-size parts, and localized support. These players often win on lead times, custom cutting, and industrial/insulation applications outside mainstream PCB demand.
Our assessment shows a moderate top-tier concentration: combined shares for the three and five largest producers reflect an industry where scale confers advantages in feedstock access and qualification bandwidth, but where mid-tier and regional specialists retain meaningful niches—creating a dynamic M&A and partnership corridor for 2026.
Operational and Commercial Playbook for 2026
Executives should translate the report’s insights into three specific action streams for 2026:
- Supply resilience and input-cost hedging: Put in place raw-material procurement strategies that combine multi-sourcing, regional hedges, and indexed purchase agreements for epoxy and copper. Our scenario tables show that even modest variations in resin and glass prices materially shift gross margins—procurement should therefore be central in commercial planning.
- Product-mix and capex prioritization: Allocate R&D and capacity investments toward higher-Tg, halogen-free, and automotive-qualified FR4 variants. These subsegments are expected to outgrow the market-average rate, and early investment shortens time-to-qualification with OEMs—translating into premium pricing potential.
- Commercial and regulatory readiness: Adopt standardized, audit-ready RoHS/REACH declaration packages and establish faster sample-qualification processes. The report includes template contractual language and a supplier scorecard that helps procurement and legal teams accelerate supplier onboarding without sacrificing compliance.
What the Full Report Contains (and Why You’ll Want It)
PW Consulting’s full Worldwide FR4 Plates Market report delivers detailed modules designed for executive action:
- Comprehensive historical dataset (2020–2025) and forecast model (2026–2032) with sensitivity scenarios and margin impact analysis;
- Segmentation by product type, application, and region with demand drivers and demand-qualification pathways (note: granular segment figures are reserved for the complete report to preserve competitive confidentiality and to support client-specific modeling);
- Supplier scorecards, recent-developments timeline, and a shortlist of near-term M&A and JV candidates based on capacity, technology, and geographic fit;
- Practical annexes: contract templates for indexed pricing, a regulatory compliance checklist, and a unit-cost decomposition model linking resin, glass, and copper prices to laminate production economics;
- Primary research: interviews with procurement heads, plant managers, and OEM buyers, along with proprietary shipment-inventory reconciliations to validate end-market demand.
Closing: How to Use This Intelligence in 2026
For boards and executive teams, the path through 2026 is about converting structural market growth into durable margin improvement while managing volatility. PW Consulting’s brief equips leaders with the scenario language, supplier intelligence, and actionable checklists needed to make defensible choices on capital allocation, pricing architecture, and compliance-driven product strategy. The top-line growth trajectory—from roughly USD 12.5 billion in 2025 to nearly USD 19.0 billion by 2032 at a 6.15% CAGR—creates opportunities for both scale players and nimble specialists. The differentiator for winning companies will be their ability to pair technical product differentiation with disciplined feedstock management and accelerated regulatory qualification.
To access the full dataset, segmentation tables, supplier scorecards, and negotiation playbooks that operationalize these conclusions, visit the PW Consulting report landing page or contact our industry advisory desk for a tailored briefing. Our analysts stand ready to translate the market forecast into a prioritized 90-day action plan for procurement, product, and commercial teams.
For detailed analysis of this topic, please visit the official page: Worldwide FR4 Plates Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: Worldwide Phlegm Suction Tube Market to Rise from USD 650 Million in 2025 to USD 926.9 Million by 2032 at a 5.2% CAGR
By pmarketresearch, 2026-08-18
Worldwide Phlegm Suction Tube Market — Strategic Preview for 2026: PW Consulting’s New Market Intelligence
Executive Summary
PW Consulting today releases a forward-looking executive preview of our full market research report on the Worldwide Phlegm Suction Tube market. Built on an audited historical baseline (2020–2025) and a seven-year forecast (2026–2032), the study synthesizes clinical, commercial, regulatory, and operational intelligence that will directly inform buy-side, sell-side and policy-making decisions in 2026.
Offshore Wind Foundation Market
Key headline metrics: the global market expanded from approximately USD 510.5 million in 2020 to USD 650.0 million in 2025. Under the scenarios modeled in this research, the market reaches roughly USD 926.9 million by 2032, representing a 2026–2032 compound annual growth rate (CAGR) of about 5.2%. Market concentration is moderate: the top three players account for roughly 42.6% of market value and the top five for about 58.4% — a structure that supports both consolidation and continued opportunity for specialist innovators.
Worldwide Disc Grinder Market
Why this study matters for 2026 decision-makers
- Timing: 2026 is a strategic inflection point — suppliers that lock in supply-chain resilience, regulatory clarity, and differentiated clinical value now will secure preferred-provider status as procurement cycles accelerate.
- Margin preservation: Rising demand for disposable systems and biocompatible materials increases procurement complexity and cost pressure. Buyers and manufacturers need forward-looking price benchmarking and material-sourcing playbooks to protect margins.
- Regulatory and reimbursement alignment: Recent shifts in standards and coding make early alignment a competitive advantage. The report clarifies what compliance investments produce outsized commercial return in 2026 and beyond.
What PW Consulting’s full report delivers (practical, operational content)
This release is a strategic preview. The full report is designed as a hands-on toolkit for commercial leaders, procurement officers, R&D heads and M&A teams. Key deliverables include:
Power Plant Lightning Protection Market
- Market sizing and scenario-based forecasts (base year 2025; historical period 2020–2025; forecast 2026–2032) with sensitivity analyses and breakouts by product architecture, clinical setting, and geography (note: granular segment datapoints are available in the full report).
- Supply chain and cost stack mapping that identifies single-source risks, material cost drivers (PVC, silicone, specialty polymers), and tiered supplier scorecards for near-term sourcing decisions.
- Regulatory and reimbursement navigator: a practical matrix mapping ISO and FDA requirements, key HCPCS codes and payer triggers, plus a compliance-impact calculator to prioritize investments that unlock access to critical markets.
- Buyer’s playbook for procurement teams: contract language templates, inventory buffers calibrated to lead times, and a supplier qualification checklist focused on sterility assurance and radiation/irradiation process controls.
- Clinical adoption roadmaps for closed vs. open suction systems, with use-case analytics across hospital ICU, emergency, ambulatory, and home-care pathways — highlighting cost-per-procedure, infection-control trade-offs, and clinician adoption barriers.
- Commercial intelligence dossier on 12+ manufacturers including product portfolios, differentiators, manufacturing footprint, and go-to-market strategies — complemented by a near-term M&A heatmap and partnership scenarios.
- Price and margin benchmarks, product-level gross margin estimates, and suggested strategic pricing levers tailored to hospitals, GPOs, and home-care distributors.
Competitive Landscape — strategic reads on core players
The market combines global medical-disposables incumbents with nimble regional manufacturers. Our qualitative and quantitative benchmarking indicates four recurring strategic postures: scale players focusing on portfolio breadth and distribution; cost-leaders emphasizing high-volume disposable supply; specialized innovators introducing value-added design (e.g., closed-system features, directional valves); and contract manufacturers serving OEMs.
- Cardinal Health — leverages broad distribution and clinical relationships to position Argyle™ and Medi-Vac™ lines as procurement-safe, hospital-ready options. Strength: channel reach and integrated supply agreements. Watch: margin pressure in commoditized SKU lines.
- BD (Becton Dickinson) and Medline Industries — compete on clinical trust and product hygiene design; their emphasis on kit solutions and procedural convenience resonates with busy OR/ICU buyers. Strength: trust and product standardization. Risk: exposure to commoditization absent continuous product differentiation.
- Teleflex and Smiths Medical — position higher on critical-care specificity and sterile, performance-tested assemblies. Strategic strength in high-acuity settings where clinicians accept premium for reliability.
- Regional manufacturers (Angiplast, Suzhou Sunmed, Shanghai Teamstand, Dispowell, Luck Medical, Amsino, Sunset Healthcare Solutions) — deliver cost-competitive, high-volume products and increasingly pursue regulatory approval to enter western markets. Strategic play: targeted regulatory investments can unlock rapid share gains in export markets.
Recent credible events underscore dynamic competitive risks and opportunities. For example, a 510(k) clearance secured in mid-2025 illustrates how targeted regulatory wins accelerate access to procedure-grade applications in developed markets; conversely, a high-profile recall in early 2025 highlighted sterility-process risk for closed systems and the reputational damage such events can impose across a supplier’s portfolio. These developments shift procurement criteria: buyers prioritize demonstrable sterility assurance and supplier transparency as much as unit price.
Market dynamics: regulation, reimbursement, and material drivers
- Standards and device classification: Suction catheters are governed by ISO standards that set dimensions, flow performance and sleeve design; many tracheobronchial kits are Class II under FDA regulations with nuanced 510(k) requirements. Manufacturers that embed ISO and FDA expectations into early-stage design significantly reduce time-to-market risk.
- Reimbursement environment: Updated payer guidance (including recent Medicare coding clarifications) modifies the economics of device selection in post-acute and home-care channels. The report’s reimbursement model converts coding changes into facility-level P&L implications.
- Raw materials and manufacturing: Demand for biocompatible PVC and silicone, and the broader U.S. medical tubing market dynamics, are primary upstream cost drivers. The report quantifies elasticity points where polymer substitution, process automation, or strategic VMI (vendor-managed inventory) can improve margins.
Strategic implications and recommended 2026 actions
PW Consulting’s practical guidance for leadership teams entering 2026 centers on five priorities:
- Secure sterility assurance: Audit irradiation contracts and sterile-process validation now; the cost of remediation after a sterility event materially exceeds pre-emptive validation spend.
- Segment the go-to-market approach: Differentiate offerings between acute-care closed systems and high-volume open suction devices for ambulatory/home settings. Tailored contracting and clinical evidence packages increase win rates.
- Cost-to-serve optimization: Rebalance SKU portfolios to reduce low-turn SKUs, negotiate polymer supply contracts indexed to transparent indices, and pilot regionalized production to shorten lead times for major buying clusters.
- Regulatory arbitrage and market entry: Prioritize 510(k) and other market clearances for differentiated devices where premium pricing is viable — and use export-focused OEM partnerships to scale commodity SKUs.
- M&A and partnerships: Pursue tuck-ins for capability gaps (sterility analytics, polymer processing, closed-system valves) or strategic supplier agreements to secure critical polymer throughput.
How PW Consulting’s report supports execution
The full deliverable provides executable artifacts — supplier RFP templates, a regulatory-cost impact calculator, and a procurement negotiation playbook — enabling commercial teams to translate market intelligence into immediate operational moves. Financial-model annexes convert top-line forecasts into SKU-level revenue targets and margin scenarios under alternate raw-material and pricing assumptions.
Next steps & how to access the full intelligence
This preview intentionally surfaces the analysis framework and strategic conclusions while withholding granular segmentation datapoints that are included in the full report. Clients and decision-makers who require the underlying split-by-region, type, and application matrices, the detailed company scorecards and the downloadable tools should contact PW Consulting for access to the full Worldwide Phlegm Suction Tube Market report and supporting datasets.
In 2026, the players who win will not only understand the market’s steady mid-single-digit growth trajectory, but also operationalize sterility, supply-chain control, and targeted regulatory investments to capture disproportionate share. PW Consulting’s study is designed to be the operational blueprint for those choices.
For detailed analysis of this topic, please visit the official page: Worldwide Phlegm Suction Tube Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Phenolic Curing Agent Market Set for 5.12% CAGR — Key Growth Drivers and Regional Leaders Unveiled
By pmarketresearch, 2026-08-18
Worldwide Phenolic Curing Agent Market — Strategic Outlook for 2026: Why This Report Will Be a Boardroom Imperative
PW Consulting’s latest market study on the Worldwide Phenolic Curing Agent Market is published with a clear mandate: equip senior executives, commercial leaders and M&A teams with an executable intelligence set to make confident decisions in 2026. The market reached an estimated USD 861.3 Million in our 2025 base year and, under our central forecast, expands at a compound annual growth rate (CAGR) of 5.12% over 2026–2032 toward just over USD 1.22 Billion by 2032. Those headline numbers capture growth momentum — but the report’s strategic value lies in the operationally-focused tools and scenario framings that translate that momentum into concrete choices for procurement, product strategy, and inorganic growth.
Worldwide Traval Retail Cosmetic Market
Why boards and strategy teams will rely on this study
-
Actionable, not academic: beyond topline sizing, the report delivers supplier scorecards, margin-impact models and a commercial playbook that to-the-dollar estimates how raw-material moves and customer mix shifts will flow to your P&L.
Worldwide Tubing Connections Market -
Risk-to-return mapping: we quantify and stress-test the market under multiple raw-material and regulatory shock scenarios — enabling procurement and R&D leaders to prioritize hedging, reformulation, or vertical options.
Head Mirror Market -
Competitive clarity: a focused benchmarking of leading participants and capability gaps helps identify targets for bolt-on acquisitions, strategic partnerships, or joint development agreements.
Key themes shaping 2026 strategic choices
-
Price and margin pressure from raw-material volatility — Phenol and formaldehyde price swings are no longer episodic. Our monitoring through April 2026 registered substantial increases in key Asian and European phenol hubs and a material step-up in U.S. formaldehyde prices in late 2024. These cost moves are compressing gross margins for producers that cannot pass through rapidly or reformulate toward lower-cost chemistries.
-
Regulatory complexity is increasing — Recent regulatory activity (for example, reporting obligations introduced for certain phenolic derivatives under TSCA’s SNURs) imposes new compliance burdens and potential time-to-market friction for product introductions and reformulations in North America. This alters the calculus for product launches and for acquiring technology or plants that serve regulated uses.
-
Demand pockets remain durable but selectively evolving — End-use engines such as electronics encapsulation, industrial coatings systems, adhesives and advanced composites continue to anchor demand. Within these pockets, formulators are asking for higher-functionality resins, lower-VOC solutions and improved thermal/electrical performance — providing premium niches for suppliers that can invest in application-specific R&D.
-
Moderate market concentration creates maneuvering room — Market concentration metrics indicate a market where the top three vendors account for a meaningful share, and the top five for just over half of industry volume. That structure enables regional champions and specialty players to carve defensible positions while also leaving opportunities for M&A consolidation that meaningfully alters competitive dynamics.
Competitive landscape — what the leading suppliers signal for 2026 strategy
Our report profiles manufacturers and specialty suppliers across the value chain, from global resin platforms to toll processors and niche phenolic houses. Public and private participants — including established resin majors, integrated chemical producers, and specialty tollers — show differentiated plays:
-
Global resin majors bring scale and integrated upstream capabilities, enabling them to navigate raw-material cycles and support large industrial accounts with global supply footprints.
-
Specialty phenolic houses and toll manufacturers offer agility, formulation depth and the ability to service strict application requirements such as electronics and high-performance composites.
-
Some players emphasize coating-grade novolac and resole crosslinkers, while others focus on epoxy-curing compatibility for molding compounds — these strategic choices define customer segments, margin profiles and capital intensity.
To be concrete about names (and why they matter): major global suppliers, integrated chemical producers and specialized phenolic manufacturers are all active in the market. Their positioning ranges from broad aftermarket and OEM supply networks to focused toll-manufacturing and application-driven R&D. This mix means that commercial strategies in 2026 must be calibrated by supplier type — negotiating differently with a captive-volume global player versus a specialty toller capable of rapid reformulation support.
Operational playbook embedded in the report
For executives who need to move from insight to implementation, the study contains a practical set of tools and templates, including:
-
Supplier risk matrix: ranks counterparties by concentration exposure, price-transmission elasticity, and regulatory footprint to prioritize secure, cost-efficient sourcing.
-
Raw-material sensitivity models: quantify EBITDA impact across multiple phenol and formaldehyde price scenarios, enabling finance teams to model forward curves and set appropriate hedge ratios.
-
Reformulation decision tree: a roadmap that links performance targets to reformulation levers, R&D cost estimates, and expected time-to-market under current regulatory timelines.
-
M&A playbook: a prioritized target-screening framework emphasizing capability gaps, regional footprint, and near-term integration risks — and a valuation approach that captures price-cycle volatility inherent to chemical intermediates.
-
Commercial acceleration kit: win/loss frameworks and sample contract clauses (price adjustment language, force majeure drafting aligned with raw-material volatility) that legal and commercial teams can deploy immediately.
Scenario planning — three plausible market pathways for 2026–2028
-
Baseline (central) — Continuation of steady demand and partial pass-through of raw-material cost increases: the market grows in line with our 5.12% medium-term CAGR as formulators accommodate higher input costs through a mix of price adjustments and modest reformulation.
-
Up-cycle (price shock mitigated) — If phenol/formaldehyde supply tightness eases or feedstock prices retreat, producers with underutilized capacity could regain margin through volume recovery and reinvestment in higher-spec products, accelerating premium segment adoption.
-
Regulatory-constrained (cost of compliance rises) — Heightened regulatory actions or new reporting/registration requirements elevate compliance costs and time-to-market barriers, favoring larger integrated firms and creating acquisition windows for smaller players seeking liquidity.
What leadership teams should do in the next 12 months
-
Embed raw-material scenarios into quarterly planning: update price-pass-through triggers for customer contracts and revise capex prioritization to favor flexible, lower-capital intensity projects.
-
Fast-track supplier diversification and strategic inventory: secure multi-sourcing for critical phenolic intermediates and evaluate toll-manufacturing partnerships where capital deployment is undesirable.
-
Accelerate application-focused innovation: invest selectively in higher-margin niches — e.g., electronic-grade curing systems and specialty coating crosslinkers — that demonstrate insensitivity to small-volume cost shocks.
-
Use M&A opportunistically: target regional specialists and tollers whose integration can reduce sourcing risk, add formulation capability, and provide footholds in priority geographies.
Report contents — what you will find inside (high level)
-
Independent market sizing and method notes (historical 2020–2025; base year 2025) and scenario-based forecasts through 2032.
-
Cost and pricing analytics: forward-looking phenol and formaldehyde curves, plus margin impact models.
-
Segment and application demand narratives that identify durable demand pockets and emerging premium opportunities (note: detailed, proprietary subsegment tables and regional splits are available in full report access only).
-
Supplier profiles and competitive benchmarking against capability, capacity and regulatory coverage metrics.
-
Actionable annexes: sourcing playbooks, sample contract clauses, and an M&A target filter.
Closing strategic takeaway
For leadership teams preparing 2026 budgets and strategic roadmaps, the phenolic curing agent market presents both pressure and optionality. The near-term environment is defined by raw-material volatility and tighter regulatory scrutiny; yet, demand durability — backed by applications in electronics, coatings, adhesives and composites — supports disciplined investment in differentiation. PW Consulting’s report provides the analytical foundation and the executable toolset to convert market trajectories into defensible commercial and capital-allocation moves. We present the evidence you need to prioritize: whom to partner with, what to build, and where to acquire — while reserving the granular subsegment datasets that are central to deal and procurement execution for licensed access.
To access the full dataset, proprietary segment tables, and the interactive scenario toolset that management teams will use in 2026 planning cycles, visit the official report page or contact PW Consulting’s industry desk for a briefing and tailored advisory engagement.
For detailed analysis of this topic, please visit the official page: Worldwide Phenolic Curing Agent Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts Robust 12.5% CAGR for Worldwide Next‑Generation Data Storage Market Through 2032
By pmarketresearch, 2026-08-18
Worldwide Next-Generation Data Storage Market — Executive Strategic Briefing (PW Consulting)
Introduction
As enterprises finalize technology budgets and strategic roadmaps for 2026, PW Consulting’s new Worldwide Next-Generation Data Storage Market report delivers the market context and decision-grade tools needed to make high-stakes infrastructure choices with confidence. Built on a rigorous historical baseline (2020–2025) and a detailed forecast window (2026–2032), the study models the transition dynamics across traditional and emerging storage paradigms and quantifies the commercial runway for next-generation solutions. The market is sizable and accelerating: our base-year snapshot (2025) places the global market at USD 86,700 Million, rising to an estimated USD 102,547 Million in 2026 and projected to approach USD 197,736 Million by 2032—reflecting an aggregate forecast CAGR of 12.5% (USD, revenue unit: Million).
Disposable Morcellator Blade Market
Why this report matters for 2026 decision-makers
-
Timing and capacity planning — The combination of strong near-term growth and sustained mid-term expansion creates a narrow window for locking in the right balance of capacity, performance, and cost-efficiency. Procurement cycles started in H2 2025 will collide with vendor roadmaps and supply-chain rhythms in 2026; our report identifies optimal staging points for capacity refresh, expansion, and diversification.
Worldwide Utilities¡¯ Customer Information System (CIS) Software Market -
Technology bet sizing — Organizations must weigh incremental upgrades to flash and software-defined platforms against strategic pilots of MRAM, DNA storage, and other emerging persistent-memory technologies. The report’s readiness assessments and scenario modelling help quantify where pilot investment is justified versus where mainstream deployments will deliver ROI in the 2026–2028 window.
Standalone Photovoltaic Water Pump System Market -
Risk and resilience — With concentration metrics indicating meaningful market power among leading vendors (CR3: 38.5%; CR5: 56.4%), the report highlights supplier lock-in risks and contingency strategies for supply disruption, pricing pressure, and interoperability constraints—critical inputs for enterprise risk committees and CIOs.
-
Energy, sustainability and compliance — New KPIs and standards (ISO/IEC 30134 series, evolving IEEE work on AI environmental measurement, and tighter ISO 27001 expectations) are re-shaping procurement and operational requirements. The study offers actionable guidance on aligning storage choices with PUE/WUE/carbon benchmarks and information-security audit readiness.
What the report contains — practical, operational intelligence
-
Consolidated market sizing and growth modelling: a transparent methodology covering historical 2020–2025 data and detailed projections for 2026–2032 with sensitivity bands and scenario alternatives to support board-level investment decisions.
-
Technology readiness and adoption roadmaps: maturity matrices for core and emerging storage classes, including operational triggers for migrating to all-flash, hybrid architectures, software-defined storage, MRAM, and DNA-based archival systems.
-
Procurement playbook and TCO models: configurable CapEx/Opex templates, lifecycle cost illustrations, and vendor negotiation checklists that translate market-level trends into procurement-level actions for 2026 RFPs.
-
Vendor scorecards and partnership archetypes: synthesis of strategic positioning, product strengths, ecosystem fit, and go-to-market motions for leading vendors—designed to accelerate vendor shortlisting while flagging partnership and co-innovation opportunities.
-
Regulatory and infrastructure impact analysis: applied implications of ISO and IEEE standards, data-center utility constraints (including grid connection wait-time dynamics), and compliance controls that materially affect deployment timelines and TCO.
-
Executive decision frameworks: one-page decision matrices, prioritization rubrics, and a short list of “must-ask” vendor questions for 2026 procurement reviews.
Competitive landscape — strategic takeaways
The market is shaped by an interplay of legacy incumbents, flash and silicon specialists, and emergent platform innovators. Below are high-level strategic positions derived from company-level analysis; the report contains expanded vendor dossiers and a detailed assessment of partnership opportunities.
-
IBM Corporation — Positioned around enterprise-class systems and research-driven innovation, IBM couples advanced tape and archival capabilities with AI-optimized data-management platforms. IBM’s R&D footprint and enterprise services strength make it a default partner for large-scale, regulated archival initiatives.
-
Hewlett Packard Enterprise (HPE) — HPE’s emphasis on hybrid cloud, all-flash arrays, and software-defined architectures targets scalability for AI workloads. Expect HPE to compete on integrated solutions that blend on-prem performance with cloud-native management.
-
Dell Technologies — Dell’s portfolio, anchored by PowerStore and PowerMax families, is focused on high-performance, AI-driven, hybrid-cloud deployments. Dell remains a go-to for enterprises that need tightly integrated stack performance and broad channel coverage.
-
NetApp — Specializes in unified storage and hybrid cloud data services with a strong story for data mobility and tiering; strategically relevant for organizations prioritizing data lifecycle management across private and public clouds.
-
Pure Storage — A pure-play all-flash vendor with a sustainability and Evergreen subscription ethos; attractive for rapid performance refreshes and operational simplicity.
-
Micron, Samsung, Western Digital, Seagate — These suppliers drive the component-level roadmap (NAND, DRAM, HDD, HAMR, SSD). Their product roadmaps and capacity commitments are the critical upstream levers that influence vendor time-to-market and pricing dynamics.
-
Everspin Technologies — MRAM specialist with practical validation for high-reliability applications; relevant to edge and high-end transactional use cases where endurance and persistence matter.
-
Twist Bioscience, Atlas Data Storage — Pioneers in DNA-based archival storage: their roadmaps and commercialisation advances (including Atlas Eon 100) mark the beginning of a new long-term archival option. These players are best suited for early-adopter pilots focused on ultra-dense, ultra-long-retention use cases.
-
Hitachi Vantara, Huawei — Enterprise-focused platforms with strong data-management capabilities and regionally differentiated market approaches; important to consider in multi-cloud, multinational deployments from a geopolitical and compliance lens.
Recent market developments and practical implications
-
Atlas Data Storage’s partnerships and commercial platform launches (late 2025 into 2026) reduce a portion of the execution risk for DNA archival pilots—making 2026 a viable year for controlled production experiments with clear archival use-cases.
-
Patent activity and product innovations (e.g., TEAMGROUP’s patents, PROMISE Technology’s AI-optimized RAID systems, Everspin’s MRAM validation) indicate an acceleration of both performance and security features; these developments should shorten vendor evaluation cycles for proof-of-concept projects.
-
On the standards and compliance front, ISO/IEC 30134 and updates to ISO 27001—together with IEEE efforts to measure AI’s environmental footprint—are creating new procurement specs. Enterprises that bake these into RFPs today will avoid rework and compliance risk in 2026–2027 deployments.
-
Infrastructure constraints—specifically extended grid connection lead times in key data-center markets—are materially shaping deployment architecture decisions: more buyers are factoring behind-the-meter generation and colocated battery solutions into storage rollouts. The report models the cost and timeline impact of these alternatives.
Actionable 60–90 day playbook for CIOs and procurement leads
-
Reassess capacity forecasts against updated market growth curves and vendor roadmap timelines; prioritize modular purchases that preserve optionality for 2027–2028.
-
Launch targeted pilots for one emerging technology where the business case is clear (e.g., MRAM for endurance-critical workloads or DNA for long-term archival), coupled with measurable KPIs tied to cost-per-TB-equivalent and durability.
-
Embed sustainability and security KPIs (aligned to ISO/IEC 30134 and ISO 27001 expectations) into RFP evaluation matrices to avoid retrofitting solutions post-deployment.
-
Stress-test vendor supply commitments against upstream component constraints and include clear contractual remedies for delayed delivery or quality variances.
-
Update disaster recovery and data-mobility strategies to reflect multi-tier storage economics—ensure that archival tiers are decoupled operationally from hot AI/transactional tiers.
Next steps and how to access the full intelligence
This briefing highlights the strategic contours of the next-generation storage landscape and the near-term choices that will determine competitive advantage in 2026 and beyond. For procurement-ready figures, regional and application splits, detailed vendor scorecards, customizable TCO models, and RFP templates, access the full PW Consulting Worldwide Next-Generation Data Storage Market report. The report is designed to be operational: download the complete dataset and playbooks to accelerate 2026 execution, or contact our advisory team to commission a tailored vendor shortlisting and procurement strategy workshop.
For detailed analysis of this topic, please visit the official page: Worldwide Next-Generation Data Storage Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts Worldwide Modified Polyurethane Dispersion Market to Reach USD 2,646.81 Million by 2032, Driven by a 6.98% CAGR
By pmarketresearch, 2026-08-18
PW Consulting Releases Strategic Preview: Worldwide Modified Polyurethane Dispersion Market — Essential Guidance for 2026 Decision-Makers
PW Consulting today publishes a strategic preview of our forthcoming Worldwide Modified Polyurethane Dispersion (PUD) Market report, providing a targeted briefing for executive teams preparing 2026 budgets, procurement strategies, and growth initiatives. Built on a transparent methodology and actionable intelligence, the report synthesizes historical performance (2020–2025), establishes 2025 as the analytical base year, and delivers a scenario-based forecast for 2026–2032. The market is projected to grow at a compound annual growth rate (CAGR) of 6.98% over the forecast period, expanding from a 2025 base to reach a materially larger market by 2032 — a trajectory that demands concrete operational responses from manufacturers, formulators, and buyers alike.
Worldwide LIMS Software Market
Why this report matters for 2026 strategy
-
Timing: 2026 is a pivot year. After several years of raw-material volatility, capacity additions, and regulatory tightening, the market is moving from stabilization into differentiated growth. The report pinpoints tactical windows for commercial action during this transition.
Worldwide Automatic Voltage Regulator (AVR) Market -
Cost and margin pressure: Upstream cost shocks — notably recent isocyanate pricing movements and supplier price adjustments — are forcing manufacturers and OEMs to revisit pricing, sourcing, and formula optimization. Our analysis links MDI/TDI cost signals to downstream margin sensitivity and highlights pass-through mechanics that are practical for procurement teams.
Residential Concierge Software Market -
Regulatory acceleration: Stricter VOC standards and evolving paint/coatings regulations in major markets continue to accelerate adoption of waterborne, modified PUD systems. The report maps regulatory thresholds to product development requirements and compliance pathways, crucial for 2026 product roadmaps.
Key macro view — market trajectory you can act on
Our model shows a clear recovery and steady expansion after 2025: following multi-year growth from 2020 through 2025, the global modified PUD market is forecast to grow at c.7% CAGR during 2026–2032. This macro momentum is driven by a combination of regulatory substitution away from solvent systems, accelerated demand in selected end-use categories, and targeted capacity investments by major chemical producers. PW Consulting’s scenario set translates this macro trajectory into three operational pathways — base, upside, and downside — each tied to concrete triggers such as raw-material pricing normalization, regulatory rollouts, and adoption rates for next-generation chemistries.
What the report contains — practical, decision-ready analysis
We designed the report to serve as an execution toolkit for senior leaders. Highlights include:
-
Actionable market sizing and forecast models (global and by major markets) with sensitivity levers that procurement, commercial, and strategy teams can plug into their internal planning tools.
-
Cost-to-serve and pass-through playbooks that translate upstream price moves into distributor and OEM margin outcomes under multiple contractual models.
-
Technology and product roadmaps comparing modified chemistries (acrylic, silicone, epoxy and other modification approaches) on performance, unit cost, and regulatory fit for prioritized applications.
-
Regulatory matrix and compliance checklists for key jurisdictions, including pragmatic timelines and certification requirements to support go-to-market plans.
-
Supplier scorecards and fit-for-purpose procurement strategies (dual-sourcing templates, tolling vs. finished goods economics, and regional inventory playbooks).
-
M&A & partnership playbook: transaction priorities, integration risks, and valuation benchmarks tailored to players in waterborne resin value chains.
-
Executive dashboards and raw data appendices for in-house analysis — we intentionally withhold detailed segment-level data from public previews to preserve client value, while providing straight-path access for licensed users.
Competitive landscape — how market leaders are positioning
The modified PUD space displays moderate concentration, with the top three and top five suppliers collectively commanding meaningful shares, a dynamic reflected in our concentration metrics. This structure creates an industry where scale and integrated supply advantages coexist with pockets of premium differentiation — especially around low-VOC, shear-stable, and bio-renewable formulations.
-
Covestro AG — Covestro’s waterborne polyurethane portfolio and Baybond line target fiber sizing, coatings, and high-performance use cases with an emphasis on low-VOC and shear-stable chemistries. Their positioning is suited to customers prioritizing application performance and regulatory compliance.
-
BASF SE — A vertically integrated player, BASF is actively tuning its dispersion capacity footprint and pricing strategy in response to upstream cost pressures. Recent site expansions to better serve architectural and construction demand signal a deliberate push into low-CO2, low-VOC dispersions — an important consideration for partners locking long-term supply arrangements.
-
The Lubrizol Corporation — Lubrizol’s emphasis on high-performance and bio-based oil-modified grades positions it well for sustainable wood coatings and abrasion-resistant applications; their technical sales model supports premium placement in value-chain segments.
-
Wanhua Chemical Group — Large-scale capacity additions in recent years increase Wanhua’s influence in waterborne resins. For global buyers, this translates to an alternative source for aliphatic-modified PUDs that balances cost and performance.
-
Specialized and regional players — Firms such as Alberdingk Boley, UBE, Mitsui’s Anderson Development, Incorez, Perstorp, Hauthaway, Essential Polymers, Stahl, and NANPAO each bring differentiated technical capabilities, regional customer relationships, or niche formulations that matter when technical fit and service levels outweigh commodity pricing. Our supplier heatmaps rank these providers across capability, capacity, and commercial flexibility.
Recent industry movements — including upstream price adjustments by major suppliers and targeted capacity builds — are shaping commercial leverage for 2026. PW Consulting’s report decodes these events into near-term tactical steps and medium-term strategic moves.
Market dynamics and a 2026 playbook
-
Procurement & supply continuity: Implement layered sourcing with a primary supplier capable of scale, a secondary specialized supplier for high-performance grades, and a tactical tolling or contract-manufacture partner to manage spot volatility. Where contracts permit, build raw-material indexation clauses to cushion margin erosion.
-
Product strategy: Prioritize low-VOC and mass-balance enabled offerings with clear substitution narratives for solvent systems. Invest in application-centric R&D (e.g., mar and scratch resistance, adhesion to new substrates) to capture premium spread.
-
CapEx & manufacturing footprint: Reassess planned investments against the backdrop of announced capacity expansions in waterborne resins. For mid-size players, consider co-location, contract production, or asset-light partnerships rather than greenfield builds in high-cost regions.
-
Pricing and commercial models: Use differentiated pricing tiers aligned to formulation complexity, certification, and service. Embrace value-based selling for high-performance grades while protecting commodity margins through optimized logistics and formulation cost-outs.
-
M&A & alliances: Sophisticated investors will find opportunities in vertical strengthening (building downstream formulation capabilities) and bolt-on tech plays (bio-based modifiers, additive packages). Our report provides deal screening criteria and target shortlists mapped to strategic objectives.
Data, methodology, and next steps
PW Consulting’s analysis uses 2025 as the base year, with a historical window covering 2020–2025 and a forecast horizon of 2026–2032. All values are reported in USD (Million) and the central forecast CAGR for the period is 6.98%. Concentration metrics and supplier analyses are included to help users judge competitive intensity and negotiation posture. The full report contains granular models, downloadable data tables, and customizable dashboards; this preview preserves the high-level implications while directing practitioners to the source for the complete dataset and segment-level numbers.
To access the full dataset, company scorecards, and the downloadable decision-support workbook — or to schedule a tailored executive briefing that translates these insights into a 90-day implementation plan — please visit the PW Consulting report page or contact our industry practice.
PW Consulting: we turn market signals into operational advantage.
For detailed analysis of this topic, please visit the official page: Worldwide Modified Polyurethane Dispersion Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com