

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Polylaurolactam Market to Expand at 5.6% CAGR — From USD 1,485.5 Million in 2025 to USD 2,175.32 Million by 2032

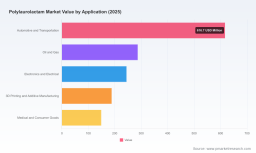
Worldwide Polylaurolactam (PA12) Market — Strategic Briefing for 2026 Decision-Makers
PW Consulting’s latest Worldwide Polylaurolactam Market study (base year 2025, forecast 2026–2032) consolidates proprietary data, primary interviews, and supply-chain modeling to deliver an executive-grade roadmap for commercial, procurement, and R&D leadership. Our analysis shows the PA12 market entering its next phase of steady expansion, with the global revenue base near the mid‑point of the last decade and a compound annual growth rate (CAGR) of 5.6% built into our 2026–2032 projections. For organizations that rely on PA12 for high‑performance plastics—automotive, industrial and electronics OEMs, material suppliers, and compounders—this report is a practical instrument for calibrating 2026 budgets, capacity plans, and strategic partnerships.
Driver Training Management Software Market
Why PA12 Matters in 2026
Polylaurolactam (commercially known as PA12 or Nylon 12) occupies a premium position in polymer portfolios: it combines low water absorption, chemical resistance and dimensional stability with process flexibility across extrusion, injection molding, and powder/filament systems used in additive manufacturing. These material characteristics are driving sustained demand in segments where performance and regulatory compliance outweigh raw material cost pressures. Our market model traces the sector’s recovery from early‑decade volatility into a structurally healthier landscape as electrification, lightweighting and additive manufacturing adoption continue to unlock new mid‑cycle demand.
Vehicle-Mounted Ni-Mh Battery Market
Headline Market Dynamics
- Measured growth path: The global PA12 market is modeled to grow at a steady mid‑single digit CAGR through 2032 under our base case. That trajectory reflects a mix of incremental substitution in automotive systems, capacity additions in Asia, and scaling of specialty grades for 3D printing and medical applications.
- High supplier concentration: Market concentration is pronounced: the top three suppliers control a large majority of global shipments, while the top five extend that dominance substantially. This concentration shapes pricing power, contract terms, and the pace at which new grades reach commercial scale.
- Raw material volatility and supply risk: Laurolactam—the monomer feedstock for PA12—remains sensitive to upstream petrochemical dynamics. Our analysis shows recent softening in laurolactam prices in late 2025, and direct dependencies on butadiene-derived intermediates create ongoing exposure to feedstock cycles.
- Sustainability as a procurement vector: OEM targets for sustainable polymer content are elevating the strategic importance of bio‑based PA12. Automakers and industrial buyers increasingly require supply‑chain transparency and a credible roadmap to 20–30% sustainable polymer incorporation by 2030, creating both risk and opportunity for incumbent and emerging suppliers.
Competitive Landscape — What Matters to Buyers and Investors
The competitive map is defined by a handful of vertically integrated producers and specialty polymer houses. These players combine scale production, global logistics footprints, and grade portfolios spanning extrusion, injection molding, and powder systems for additive manufacturing. In practice, this yields three commercial realities for market participants in 2026:
Worldwide Outdoor LED Street Lighting Market
- Negotiation leverage is asymmetric: large, multi‑grade suppliers control continuity and premium grade availability, which matters when qualifying parts for safety‑critical applications.
- Regional capacity expansions—particularly in Asia—translate into pricing pressure for commodity grades while premium, performance‑differentiated formulations retain margin resiliency.
- Sustainability and traceability initiatives are becoming core competitive differentiators; companies that can certify bio‑content and demonstrate low‑carbon supply chains command premium buyer attention.
Among the companies we profile in detail, several represent archetypes buyers will want to benchmark: a global specialty polymer leader with world‑scale production; a chemical group that couples PA12 with bio‑based product lines; a European engineering polymer house focused on high‑performance compounds; a Japanese producer oriented to precision molding grades; and a large integrated Chinese producer rapidly scaling domestic capabilities. Recent market movements exemplify these dynamics—price adjustments by an Asian integrated player in early 2026 and public sustainability positioning by a leading European producer during 2025 have already shifted negotiation postures across the supply base.
Strategic Implications for 2026 Planning
- Procurement and contract strategy: Locking tiers of security and price protection for core PA12 grades should be prioritized for programs with long qualification cycles. Consider blended sourcing across a global leader and regionally advantaged producers to manage supply continuity versus cost.
- Sourcing for sustainability: Establish supplier scorecards that weight verified bio‑content, carbon footprint disclosures, and third‑party certification. Early partnerships with bio‑PA12 pilots can secure pathway advantage as OEM mandates crystallize.
- Product and process R&D: Invest selectively in compound development and additive manufacturing feedstock qualification. Materials that shorten cycle time, reduce scrap, or enable lightweighted assemblies will capture disproportionate value.
- M&A and JV playbook: For mid‑sized polymer converters and specialty chemical investors, bolt‑on acquisitions of capacity or technical compounding assets offer rapid access to growth. Our report includes scenario analysis for acquisitive strategies under varying price and demand assumptions.
- Risk management: Hedging laurolactam exposure and maintaining visibility on butadiene markets should be part of treasury and procurement roadmaps. We model stress scenarios that quantify margin impact from feedstock shocks across product lines.
What the Full Report Contains — Practical Tools Inside
PW Consulting’s study is designed as an operational playbook rather than a high‑level snapshot. Clients receive:
- Proprietary demand and supply models with editable assumptions for scenario planning (price, adoption, capacity additions).
- Supplier scorecards and a negotiation checklist tailored to PA12 grade families and supply risks.
- Technology deep dives comparing extrusion, injection and powder system economics for manufacturers and AM users.
- Regulatory and sustainability roadmaps mapping OEM targets to material pathways, plus recommended actions for procurement and product development teams.
- An M&A and investment appendix containing valuation sensitivities and integration risk factors for target archetypes across regions.
To preserve commercial value and follow the pre-release principle, the public briefing intentionally omits the detailed regional, grade and application split tables; those granular datasets and the interactive model are available to subscribers and licensed purchasers on the report portal.
Near‑Term Signals and Monitoring Dashboard
For 2026 execution, we recommend establishing a simple monitoring dashboard of five leading indicators that correlate closely with PA12 market condition and price direction:
- Spot and contract laurolactam price trends, particularly feedstock differentials tied to butadiene cycles.
- Capacity announcements and debottlenecking projects in major regional hubs.
- Orderbook and design wins in target end‑markets—especially high‑volume automotive programs and AM series production ramps.
- Supplier actions on sustainability: publication of bio‑PA12 supply commitments, trade‑off analysis between biobased content and lifecycle impacts.
- Major procurement actions and public price notices from vertically integrated producers as they adjust to feedstock shifts.
We continue to watch two high‑impact developments closely. First, upstream raw material behavior: the recent softening in laurolactam pricing observed in Q3–Q4 2025 reduced near‑term cost pressure, but the dependency on petrochemical intermediates leaves the market exposed to renewed volatility. Second, capacity and policy: China’s ongoing expansion of laurolactam and Nylon 12 production capacity is reshaping regional competitiveness and will influence feedstock flows and export dynamics over the next 24–36 months.
Final Recommendation for Decision‑Makers
As PA12 demand broadens across established and emerging applications, the strategic challenge for 2026 is balancing security of supply with margin preservation and sustainability compliance. Our core recommendation: adopt a dual approach—lock operational continuity for core grades through multi‑tiered agreements with leading global suppliers, while investing in targeted development of higher‑margin, sustainability‑aligned formulations and additive manufacturing feedstocks.
PW Consulting’s Worldwide Polylaurolactam Market report equips executives with the market intelligence, supplier benchmarking and executable playbooks needed to operationalize that approach. For access to the full dataset, regional and application splits, and the interactive forecast model, please visit the report portal where licensing options and tailored consulting engagements are available.
For detailed analysis of this topic, please visit the official page: Worldwide Polylaurolactam Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com