

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: 8‑bit Automotive MCU Market at US$850 Million in 2025 — Asia Pacific Leads with US$425M; Poised to Reach US$1,010.38 Million by 2032 at 2.5% CAGR (Top 3 Hold 68.5%)

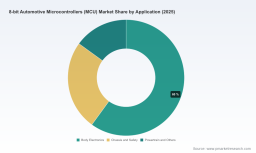
PW Consulting: Strategic Brief — 8‑bit Automotive MCU Market Outlook to 2032
As automotive architectures continue to bifurcate between cost‑sensitive, highly integrated vehicle subsystems and compute‑intensive domain controllers, 8‑bit microcontrollers (MCUs) remain an indispensable element of the automotive electronics stack. PW Consulting’s new market research report — base year 2025, historical coverage 2020–2025, and forward projections through 2026–2032 — delivers the strategic intelligence executives will need to make high‑stakes product, sourcing, and M&A decisions in 2026. Built on an evidence base of supplier filings, tier‑1 OEM interviews, design‑win tracking, and production validation, the analysis highlights a measured but durable market expansion at a 2.5% CAGR.
Methylmalonic Acidemia Treatment Market
Why 2026 Is a Pivotal Year for Automotive MCU Strategy
-
Regulatory and safety expectations are converging toward a stricter certification posture: AEC‑Q100 Grade 0 qualification and ISO 26262 functional safety requirements (commonly up to ASIL B for many 8‑bit use cases) are now baseline expectations for new designs. This increases the qualification burden — and therefore the switching costs — for OEMs and Tier‑1s.
High Precision Inductors Market -
Supply‑chain normalization post‑2021 volatility has stabilized lead times for automotive‑grade devices, but geopolitical dynamics are accelerating regionalization pressures that favor onshore or nearshore sourcing in Asia for many OEM supply chains.
Meat Certification Market -
Technological choreography between 8‑bit MCUs and higher‑order controllers (16/32‑bit) is increasingly critical. Cost optimization, software continuity, and lifecycle support now shape not only component selection but also architecture roadmaps and procurement strategies.
Market Trajectory at a Glance
PW Consulting’s topline modelling shows a steady, resilient expansion of the 8‑bit automotive MCU market. In USD (Million), the market progressed from approximately 810 in 2023 to 830 in 2024 and 850 in 2025 (base year). Our forecast projects growth to about 871.25 in 2026 and continues to expand to roughly 1,010.38 by 2032, reflecting a compound annual growth rate of 2.5% for the forecast period.
What this trajectory signals for corporate decision‑makers is a mature market with incremental unit growth and sustained aftermarket relevance. Investment decisions should therefore be guided by margin preservation, long‑tail service economics, and the ability to sustain multi‑year qualification and production commitments rather than by chasing rapid volume gains.
What the Report Delivers — Operational, Decision‑Ready Insights
-
Actionable scenarios for procurement and dual‑sourcing to reduce supplier concentration risks while protecting cost targets.
-
Qualification and certification roadmaps that align engineering timelines with OEM launch calendars for AEC‑Q100 Grade 0 and ISO 26262 compliance.
-
Supply‑chain stress tests and contingency playbooks that quantify inventory exposure and outline tactical mitigation measures for localized disruptions.
-
Technology migration models that evaluate the commercial tradeoffs between retaining 8‑bit platforms and migrating to 16/32‑bit solutions across functional domains.
-
A vendor scorecard framework and an M&A playbook to prioritize targets and partnership structures that strengthen product portfolios or regional manufacturing footprints.
-
Lifecycle and obsolescence management protocols to preserve aftermarket revenues and minimize redesign costs over multi‑year programs.
In keeping with the “prequel” purpose of this release, the report contains detailed regional, application and type‑level splits and revenue overlays, which are intentionally not reproduced here so decision‑makers will consult the full deliverable for granular allocations and model assumptions.
Competitive Landscape — Key Players and Strategic Postures
The 8‑bit automotive MCU market is concentrated, with leading vendors commanding substantial installed bases and ecosystem depth. PW Consulting estimates that the top three vendors control a significant majority of market share, and top five concentration rises further — a structure that favors established suppliers that combine automotive qualification, long product lifecycles, and broad software/ecosystem support.
-
Microchip Technology (Chandler, AZ) — Microchip remains a dominant force in automotive‑grade 8‑bit MCUs, offering AEC‑Q100 Grade 0 qualified PIC and AVR families with CAN/CAN FD support and functional safety credentials up to ISO 26262 ASIL B. Their portfolio targets body, HMI, and sensor applications where thermal resilience and robust communication interfaces are critical.
-
STMicroelectronics (Geneva) — ST continues to actively support its STM8AF/STM8AL series, expanding packaging and ecosystem tools to sustain design wins in body and powertrain contexts. Recent portfolio updates through early 2026 underscore ST’s commitment to the automotive 8‑bit segment as part of a broader multi‑architecture automotive strategy.
-
NXP Semiconductors (Eindhoven) — NXP’s legacy S08 and HC‑series remain relevant in cost‑sensitive applications. Their advantage lies in long‑term automotive qualifications and depth across CAN‑based networked subsystems that remain common in production fleets.
-
Silicon Laboratories (Austin) — Silicon Labs brings high‑integration 8‑bit devices with features like integrated 12‑bit ADCs in compact packages, appealing to sensor and compact control applications that demand analog performance in constrained BOMs.
-
Renesas Electronics (Tokyo) — Renesas’ RL78 family (8/16‑bit hybrids) addresses low‑power, automotive‑qualified needs for body control and lighting domains, benefitting from Renesas’ deep relationships with OEMs and Tier‑1s.
-
Infineon Technologies (Neubiberg) — Infineon maintains legacy XC800 alternatives for demanding applications, with a focus on industrialization and high‑reliability deployments.
Recent product availability and portfolio refreshes from several of these vendors in early 2026 confirm that incumbents are prioritizing ecosystem continuity, extended temperature ranges (up to 150°C), CAN FD capabilities, and functional safety flows rather than radical architectural displacement.
Strategic Implications for OEMs, Tier‑1 Suppliers and Semiconductor Vendors
-
For OEMs: Lock in long‑lead qualification windows early. Because certification and production stability drive switching costs, early alignment on supplier roadmaps, common‑software strategies, and obsolescence clauses is essential to protect program economics.
-
For Tier‑1s: Prioritize supplier consolidation with contingency agreements. The market’s concentration creates both dependency and bargaining leverage. Use that leverage to negotiate stronger lifecycle support and cost pass‑through protections.
-
For Semiconductor Vendors: Differentiate through systems‑level support — expand dev‑tool chains, certify reference designs, and package safety and quality services to commoditize switching pain for OEMs. Consider regional capacity and service nodes to address geopolitical localization pressures in Asia.
-
Across the ecosystem: Adopt hybrid migration strategies. Preserve 8‑bit platforms where they make economic sense (lighting, simple body functions, sensors) while accelerating software portability and abstraction layers for functions that will ultimately migrate to 16/32‑bit domains.
Methodology, Validation and What We Withhold in This Brief
Our quantitative projections rely on historical shipment and revenue reconciliations from 2020–2025, validated against supplier disclosures, design‑win trackers, and OEM program roadmaps. Forecast scenarios blend bottom‑up module demand (per vehicle BOM modeling) with macroeconomic and vehicle production forecasts, and include sensitivity analysis for lead‑time disruptions and policy shifts.
To preserve the strategic utility of this brief while protecting proprietary analytics, we have intentionally withheld the granular regional, application, and product‑type revenue splits that appear in the full report. These withheld elements include modelled allocations that directly inform supplier selection and competitive pricing strategies; they are available only in the complete report package to ensure decision‑makers can act on fully attributable, auditable figures.
How to Use the Report for 2026 Decision‑Making — A Tactical Roadmap
-
Integrate the report’s qualification roadmap into your 2026 program cadence: map AEC‑Q100 and ISO 26262 gates to engineering milestones and procurement contracts.
-
Run the included supplier stress test against your inventory and production plan to quantify risk exposure and identify where buffer stocks or alternate sourcing are cost‑effective.
-
Apply the vendor scorecard to upcoming RFQs: weigh long‑term support and software ecosystem advantages more heavily than short‑term BOM savings for components with multi‑year production lives.
-
Pursue targeted partnerships or bolt‑on acquisitions if your strategy requires immediate expansion of automotive‑grade 8‑bit product lines or regional manufacturing presence.
Conclusion & Access
For organizations that must balance cost, reliability, and long‑term program stability, PW Consulting’s 8‑bit Automotive MCU Market report provides the disciplined, operational intelligence necessary to prioritize investments in 2026 and beyond. The market is growing steadily but not explosively — success will accrue to those who manage qualification timelines, supplier concentration, and technology migration with rigor.
To obtain the full report, including the detailed regional and application splits, vendor profiles with revenue estimates, and the complete suite of tactical templates and scenario models, please visit PW Consulting’s research portal or contact our client services team for enterprise licensing and bespoke advisory engagements.
For detailed analysis of this topic, please visit the official page: 8-bit Automotive Microcontrollers (MCU) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com