

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting: Follow‑Me Autonomous Tech Propels Worldwide Hands‑Free Caddie Market to USD 587.14 Million by 2032 at 10.45% CAGR
By pmarketresearch, 2026-08-18
Worldwide Hands‑Free Caddie Market: Strategic Preview for 2026 — Insights from PW Consulting
PW Consulting’s latest market intelligence on the worldwide hands‑free caddie market provides a focused, decision‑ready briefing for executives planning investments, product launches, channel plays, or operational pilots in 2026. This executive summary teases the analytical depth of the full report — including validated market-sizing, forward forecasts, go‑to‑market frameworks, supplier scorecards and risk matrices — while preserving the proprietary sub‑segment detail reserved for the full dossier.
Worldwide General Medicine Education Publishing Market
Why 2026 Is a Pivotal Year
- Market momentum: After an aggressive recovery and expansion phase through the early 2020s, the market reached an estimated USD 292.8 Million (base year 2025). Our forecast shows sustained expansion over 2026–2032, with the market more than doubling from the 2025 base by the end of the forecast window.
- Structural acceleration: A measured but steady compound annual growth rate (CAGR) of 10.45% underpins this trajectory, reflecting both unit adoption and premiumization driven by autonomy, sensor integration, and service models.
- Decision timing: 2026 represents an inflection point where product maturity, regulatory attention, and buyer readiness align — making it the year to convert strategy into pilots, partnerships, and scaled deployments.
Key Market Dynamics Shaping Strategy
- Technology convergence: Hands‑free systems are converging around multi‑sensor stacks (visual AI, LiDAR/TOF, UWB/ultrasound, RF and Bluetooth) plus advanced control software. That convergence is creating a “feature battleground” in obstacle avoidance, slope management and power efficiency — areas that determine user satisfaction and course acceptance.
- Safety and standards pressure: Product safety design is no longer peripheral. Automatic downhill braking and stability systems are becoming mandatory features in leading models, and course operators now expect proof points on fail‑safe behaviors. This raises engineering costs but reduces operational risk for lessees and courses.
- Commercialization models: Leasing and fleet models for clubs and rental operators are becoming the dominant adoption path for institutional buyers, while retail and hybrid ownership remain important for individual golfers. Course operators evaluating hands‑free caddies are increasingly focused on lifecycle costs, uptime SLAs, and training/maintenance requirements.
- Consolidation and concentration: Market concentration indicates room for scale plays. Leading firms together command a meaningful share of market revenue, with the top three and top five vendors accounting for substantial portions of market revenue — a dynamic that favors well‑capitalized incumbents and disciplined consolidators.
Strategic Implications — What Leading Executives Should Do in 2026
Executives who treat 2026 as a trial‑and‑scale year will capture share and shape standards. Practical priorities include:
Worldwide Automatic Tolling Systems Market
- Prioritize partner pilots that validate safety and terrain performance. Shortlist vendors that can demonstrate robust downhill braking, obstacle avoidance and slope handling in club‑grade conditions, then run week‑long pilots across representative holes rather than single‑day demos.
- Design commercial models around total cost of ownership (TCO) and uptime. For clubs and rental fleets, make maintenance, training and spare‑parts logistics core to commercial negotiations. For consumer channels, emphasize warranty, drop‑in accessory ecosystems and trade‑in paths.
- Upgrade procurement RFPs to include standardized performance tests. Include pass/fail criteria for sensor redundancy, battery life under load, and recovery behaviors after communication loss. Use those tests in supplier scorecards to reduce post‑deployment surprises.
- Invest in a modular product roadmap. Given the rapid pace of sensor and AI improvements, companies should decouple hardware platforms from perception and autonomy stacks to accelerate feature upgrades while protecting hardware investments.
- Monitor regulatory developments and build compliance playbooks. From safety device requirements to worker‑classification implications in key markets, regulatory shifts will influence operating models, insurance and leasing structures.
Competitive Landscape — Who Matters and Why
The competitive field spans global incumbents, specialized innovators, and established outdoor/automotive OEMs pivoting into golf mobility. Below are the strategic positions of key players covered in our research and what to watch from each in 2026.
Worldwide Property & Casualty Policy Administration Systems Software Market
- MGI Golf — Australia HQ with significant US operations. MGI has pushed the envelope on productization with intelligent navigation series and a visible presence at trade events. Its January 2026 PGA Show introductions — including a LiDAR‑enabled follow/avoidance system and a lightweight on‑demand motorized pushcart — underline its dual focus on AI navigation and consumer convenience. For partners, MGI is notable for rapid market activation and strong channel execution in key markets.
- Stewart Golf — British engineering heritage. Stewart’s premium “follow” platforms emphasize mechanical stability and pace‑of‑play benefits on hilly courses. Its design and material choices support premium placements within club‑owned fleets and affluent consumer segments interested in engineered durability.
- CaddyTrek (FTR Systems) — US‑based robotic specialist. CaddyTrek’s product family includes ultrasound/RF and AI‑vision variants, offering multiple modes and proven terrain capability. Their product breadth makes them an attractive supplier for operators wanting flexible deployment options across varied course topographies.
- Robera — Product‑led innovator. Robera’s offerings prioritize gesture control and AI visual guidance with obstacle‑avoidance stacks that include iTOF/UWB. Their emphasis on robust sensor fusion positions them well where precision following and pedestrian safety are priority evaluation criteria.
- Kangaroo Golf — US‑based mass market and ergonomics focus. Kangaroo balances remote control simplicity with practical design — quick‑fold mechanisms and reliable autobrake systems — making it suitable for consumer retail channels and rental fleets seeking value and easy serviceability.
- Motocaddy, PowaKaddy, Alphard Golf, QOD Golf USA, Club Car (Ingersoll Rand) — Range of approaches from GPS‑integrated remote control to OEM‑scale deployments. These firms represent the trade‑off set between legacy electric trolley expertise and new autonomy features; some keep legacy products relevant via incremental autonomy integrations and OEM partnerships.
Regulation, Standards and Operational Risk
- Product safety requirements — including downhill braking and stability systems — are material for certification and course acceptance. Buyers should request third‑party test evidence and include safety clauses in contracts.
- Standards for follow technologies are not uniform: vendors use RF/ultrasound, visual AI, LiDAR/TOF and UWB in different combinations. Procurement teams should specify minimum sensing redundancy and obstacle‑avoidance performance rather than a single technology preference.
- Labor and insurance considerations can affect deployment models. In some jurisdictions, human caddies are subject to specific worker‑classification rules and compensation frameworks that can influence the cost calculus of shifting to autonomous fleets.
What the PW Consulting Report Includes (Practical, Actionable Deliverables)
The full report is designed as an operational toolkit for executives, including:
- Validated market sizing (historical 2020–2025 and forward 2026–2032 forecasts) and scenario analyses to stress‑test assumptions under different adoption curves.
- Go‑to‑market playbooks for three buyer archetypes: course operators (fleet/lease), consumer retail (direct and dealer), and hybrid rental marketplaces.
- Supplier diligence templates and a bespoke procurement RFP checklist that embeds performance pass/fail criteria for safety, terrain handling and maintenance economics.
- Commercial models comparing lease vs. purchase vs. managed‑service economics for club fleets, including sensitivity analyses for battery replacement, sensor upgrades and downtime penalties.
- Competitive scorecards and partnership matrices identifying best‑fit vendors by buyer need, integration complexity and scale readiness.
- Risk and compliance playbooks with recommended contract language, insurance considerations and pilot validation scripts to de‑risk rollouts.
How to Use These Insights in 90, 180 and 365 Days
- 90 days: Run a closed‑loop pilot with a single vendor across a small set of holes. Use our RFP checklist and pilot protocol to validate downhill braking, obstacle handling and service logistics.
- 180 days: Negotiate a scalable lease or managed‑service that includes spare‑parts provisioning, training and defined uptime SLAs. Use TCO models to compare vendor proposals.
- 365 days: Transition successful pilots into fleet rollouts or retail launches with staged feature upgrades. Lock in sensor‑stack modularity to preserve upgrade paths while amortizing hardware.
Next Steps and Where to Get the Full Dataset
This public briefing is a strategic preview that highlights why 2026 is a decisive year for market entry, scaling and consolidation decisions. For access to the full dataset — including the detailed segmentation tables, vendor scorecards, downloadable RFP templates, and the granular forecast model — visit PW Consulting’s report page for the Worldwide Hands‑Free Caddie Market. The full report contains the proprietary sub‑segment figures and channel‑level breakouts that underpin the recommendations summarized here.
PW Consulting’s global industry team remains available to support tailored procurement design, vendor selection facilitation, and pilot governance for organizations preparing to act in 2026. Contact us to book a briefing or to commission a custom variant of the market model aligned to your strategic objectives.
For detailed analysis of this topic, please visit the official page: Worldwide Hands-Free Caddie Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Chemical Injection Metering Pumps & Valves Market Poised to Reach USD 4,700 Million by 2025
By pmarketresearch, 2026-08-18
Chemical Injection Metering Pumps & Valves Market: Strategic Imperatives for 2026
As upstream activity recalibrates after successive cycles of oil price volatility, and water- and process-intensive industries accelerate digital and sustainability investments, chemical injection metering pumps and valves remain a mission‑critical element of operational integrity. PW Consulting’s latest market study—covering 2020–2025 historical performance and offering a 2026–2032 forecast—translates these dynamics into an actionable decision framework for executive teams planning capital allocation, supplier strategy, and technology adoption in 2026.
Air & Water Rinsing Machines Market
Market trajectory at a glance
Our analysis shows the global market expanding from the low billions in 2020 to an estimated USD 4.7 billion in 2025, with a projected upward trend to roughly USD 6.12 billion by 2032. The forecast period (2026–2032) is characterized by a compound annual growth rate (CAGR) of 3.85%. This mid-single-digit growth masks important inflection points: pockets of accelerated demand tied to deepwater and offshore chemical injection requirements, and episodic investment driven by water‑treatment and industrial process modernization programs.
Precious Metal Accounts Market
Importantly, the market is concentrated: the top three suppliers capture a meaningful share, and the top five command more than half of market revenues. That concentration has strategic implications for procurement leverage, qualification timelines, and M&A playbooks in 2026 and beyond.
Worldwide Coin-operated Commercial Laundry Market
Why 2026 is a pivotal year for decisions
- CapEx timing vs. operating risk: Many operators will face the classic CAPEX-versus-OPEX decision—invest today in higher‑specification, digitally enabled metering systems that reduce leak risk and maintenance burden, or continue with lower‑cost units and accept higher operational surveillance costs. Our scenarios quantify break‑even horizons for each approach under plausible oil price and service‑cost trajectories.
- Supplier selection under consolidation: With CR3 and CR5 indicating a moderately concentrated landscape, 2026 procurement strategies must weigh supplier stability, aftermarket coverage, and integration of engineered packages versus component‑level sourcing to preserve negotiating flexibility.
- Standards and compliance: API 675 remains the definitive specification for reciprocating positive‑displacement metering pumps in petroleum and petrochemical services. Tender and specification teams that align procurement language with API 675—and understand where bespoke engineering is justified—reduce specification risk and life‑cycle costs.
- Raw material volatility: Fluctuations in stainless steel and specialty alloys will affect margins and lead times. Hedging, multi‑sourcing, or strategic inventory moves are nontrivial decisions for 2026 procurement calendars.
What the PW Consulting report delivers—practical, decision‑grade content
This study is designed to be operationally useful, not just descriptive. Key deliverables include:
- Top‑level market sizing and seven‑year forecast with scenario bands that reflect differentiated demand drivers (offshore deepwater activity, water treatment modernization, chemical processing expansions).
- Vendor benchmarking that goes beyond product specs to assess API compliance, field reliability, aftermarket footprint, digital connectivity, and skid integration capability.
- Procurement playbooks with tender language templates, qualification checklists, and a risk‑weighted supplier short‑list methodology that procurement and engineering teams can use immediately.
- Technology and product roadmaps highlighting where diaphragm, piston, peristaltic and hybrid solutions are most appropriate—paired with OPEX modeling and lifecycle cost calculators.
- Supply‑chain stress tests and mitigation options to manage raw‑material and lead‑time volatility, including alternative materials, modular designs, and local assembly strategies.
- M&A and partnership screeners that identify acquisition targets and strategic alliance opportunities for component manufacturers, skid integrators, and valve specialists.
Competitive landscape—who matters and why
The vendor environment blends legacy pump specialists, engineered‑package integrators, and niche valve innovators. Our competitive analysis synthesizes company‑level strengths relevant to 2026 decisions:
- LEWA GmbH — Renowned for hermetically sealed diaphragm pumps and API‑compliant chemical injection packages. Strong in high‑pressure, critical applications where leak containment and reliability are non‑negotiable.
- IDEX Corporation (Pulsafeeder, Milton Roy, LMI) — A diversified portfolio across hydraulic diaphragm, solenoid‑driven, and mechanical metering technologies. Valuable where organizations prioritize breadth of solution and global aftermarket coverage.
- SPX Flow (Bran+Luebbe) — Excels in custom chemical injection systems for offshore applications, including double‑diaphragm designs that target high accuracy under cyclic loads.
- ProMinent GmbH — Notable for rapid product innovation and digital connectivity. Its recent beta/X launch signals the industry’s move toward lower‑footprint, connected diaphragm pumps with expanded control features.
- SkoFlo Industries — A specialist in pressure‑independent chemical injection metering valves for surface and subsea use—an increasingly important capability as field architectures consolidate pumps and distribute dosing points.
- Sidewinder, CheckPoint, Bruin Pumps — These suppliers are differentiated by ruggedized designs, solar and pneumatic offerings, and operational focus on oilfield chemicals such as methanol and corrosion inhibitors.
- Neptune (PSG) and Iwaki America — Strong positions in water treatment and industrial dosing, where precision at micro‑to‑mid flows and serviceability are priority purchase drivers.
Recent product introductions—from hydraulic API‑675 hydraulic diaphragm models to next‑generation solenoid and electronic drives—underscore supplier efforts to combine accuracy, reliability and connectivity. Our report maps these introductions to likely adoption pathways and total cost implications for field operators.
Regulation, materials, and deployment dynamics
Three external forces will shape vendor and buyer behavior in 2026:
- Standards enforcement: API 675 continues to set the bar for critical hydrocarbon applications. Tender committees that conflate “API‑style” features with true API 675 compliance expose projects to specification and warranty risk.
- Materials and cost volatility: Stainless steel and specialty alloy price swings require procurement to embed price adjustment mechanisms or design flexibilities into long‑lead contracts.
- Field architectures: Increasing deployment of pressure‑independent valves and multi‑point injection strategies will influence the balance between centralized high‑pressure pumps and distributed pumping concepts—affecting OPEX profiles and control complexity.
Actionable recommendations for C‑suite and procurement leaders in 2026
- Prioritize total‑cost‑of‑ownership analysis when approving CapEx: quantify leak‑risk, maintenance intervals, and digital monitoring ROI rather than defaulting to lowest initial cost.
- Implement a two‑track supplier strategy: maintain relationships with tier‑one API‑compliant vendors for critical duty, while qualifying regional specialists and valve innovators for lower‑risk or distributed injection points.
- Embed material‑price escalation clauses and dual‑sourcing for long‑lead components to blunt the impacts of alloy price swings.
- Accelerate pilot programs for connected metering assets that feed predictive‑maintenance outputs into existing asset‑management systems; validate expected OPEX reductions before fleet‑wide rollouts.
- Use the market concentration profile to time negotiations and partnerships—early 2026 may present a window to secure aftermarket commitments and favorable lead times before anticipated capacity investments among leading vendors.
Why PW Consulting’s study is the tactical tool your team needs
Beyond headline numbers, the report provides the blueprints procurement and engineering teams can use immediately: editable tender text, supplier‑scoring matrices, lifecycle cost models, and scenario playbooks that map supplier choice to field outcomes. We intentionally withhold granular segment tables from this press release to preserve the utility of the primary deliverable: a compact, executable intelligence product that guides supplier selection, risk mitigation and investment timing for 2026.
Next steps
Executives and technical leaders preparing budgets and supplier strategies for 2026 should review the full report to access the detailed segmentation, supplier scorecards, and downloadable procurement tools. PW Consulting also offers tailored briefings and live workshops to translate report findings into a 90‑day action plan for procurement, reliability engineering, and business development teams.
To obtain the complete study and arrange a strategy session, please visit the PW Consulting report page for Chemical Injection Metering Pumps & Valves Market. The full report contains the proprietary segment detail, company scorecards, and scenario models referenced here—essential inputs for any organization seeking to convert 2026 decisions into measurable performance gains.
For detailed analysis of this topic, please visit the official page: Chemical Injection Metering Pumps & Valves Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: Worldwide 3D-Printed Prosthetic Hands Market to Reach USD 371.66 Million by 2032, Growing at a 15.12% CAGR
By pmarketresearch, 2026-08-18
Worldwide 3D Printed Prosthetic Hands Market — Strategic Imperatives for 2026
PW Consulting’s latest market intelligence on the Worldwide 3D Printed Prosthetic Hands Market frames 2026 as a decision-rich year for manufacturers, payers, clinical providers, and technology partners. Our analysis shows the market at USD 138.7 Million in the 2025 base year, and, under current dynamics, on a trajectory to expand at a 15.12% CAGR through the 2026–2032 forecast window, approaching roughly USD 372 Million by 2032. This growth is being driven by simultaneous advances in additive manufacturing, clearer reimbursement signals, and stronger clinical evidence — creating both immediate opportunities and execution risks for firms that must choose where to compete, how to scale, and whom to partner with.
Worldwide Workplace Innovation Platforms Market
Why 2026 Is an Inflection Point
-
Reimbursement alignment: The September 2025 DME MACs and PDAC joint guidance recognizing additive manufacturing as an acceptable, reimbursable fabrication method for custom prosthetic devices removes a key commercial barrier. For suppliers and hospital systems, this shifts conversations from “will payers pay?” to “on what terms and for which use cases?”
Worldwide Big Data Analytics Software Market -
Commercial scale-up of digital manufacturing: Market actors are moving rapidly from prototyping to production-grade additive manufacturing. Notably, a major supplier has announced Medicare coverage while expanding in‑house 3D printing capacity fivefold using desktop resin systems, signalling that cost per unit and time-to-delivery are now management levers rather than immutable constraints.
Worldwide Asphalt Anti Strip Agent Market -
Regulatory and clinical convergence: FDA’s maturity in 3D printing guidance and a growing body of clinical literature demonstrating improved dexterity and satisfaction in upper‑limb prosthesis users make clinical adoption more defensible — but also raise the bar on quality systems, traceability, and post-market surveillance.
Market Structure and Competitive Dynamics — What Executives Need to Know
The market remains fragmented: CR3 sits below 20% and CR5 below 25%, underscoring that no single incumbent dominates the space. This fragmentation is fertile ground for focused entrants, rapid innovators and payer‑aligned partners — but it also demands disciplined portfolio choices.
-
Specialists focused on myoelectric, multi‑grip solutions are demonstrating how clinical approvals and insurance reimbursement unlock premium channels (pediatric care, orthotic‑prosthetic clinics, and major health systems).
-
Lean makers of body‑powered and partial‑hand devices are carving an adjacent low‑cost, high‑utility niche by leveraging robust additive nylon technologies and simplified mechanical designs to restore specific activities of daily living.
-
Nonprofit and humanitarian players emphasize localized printing and training models that change unit economics in low‑resource settings, influencing procurement practices and partner expectations in emerging markets.
Profiles and Strategic Implications of Core Competitors
-
Open Bionics — Clinically oriented bionics with insurance pathways and a strong product family strategy (multi‑grip hands, waterproof models, breathable sockets). Strategic implication: demonstrating the commercial value of clinically validated aesthetic and functional devices; a model to emulate for firms seeking payer coverage and pediatric focus.
-
PSYONIC — Lightweight, touch‑sensing Ability Hand leveraging 3D printed resins and now covered by Medicare, while materially scaling in‑house additive capacity. Strategic implication: combining product differentiation (haptic feedback) with scalable digital manufacturing creates a defendable cost/feature advantage — a competitive playbook for incumbents and fast followers.
-
Naked Prosthetics — Focus on durable, 3D printed body‑powered and partial‑hand devices using nylon additive technologies. Strategic implication: there is a sizable, under‑served segment where mechanical simplicity and material performance trump electronic complexity.
-
Unlimited Tomorrow — Verticalized model integrating 3D scanning, sockets, and hands to reduce cost while delivering realistic aesthetics. Strategic implication: vertical integration can compress lead times and margin leakage across the supply chain — a template for vertically minded companies or consolidators.
-
Limbitless Solutions — Innovation-led, donation-driven EMG devices that strengthen clinical trial pipelines and community goodwill. Strategic implication: philanthropic and trial activity can accelerate technology acceptance and provide low‑risk paths to evidence generation.
-
Victoria Hand Project — Low‑cost, localized printing and training solutions tailored to underserved regions. Strategic implication: humanitarian and local-manufacture models will increasingly influence pricing expectations and distribution strategies in international markets.
Operational Priorities — From Materials to Manufacturing
-
Materials and processes: Nylon and PA11 printed via SLS/MJF are the workhorses for durable, patient‑facing components; resin systems are enabling rapid iteration and embedded sensor housings. Procurement strategies should prioritize long‑term supply agreements for bio‑compatible grades and secondary certification pathways for sterilization and traceability.
-
Quality and regulatory architecture: FDA 510(k) pathways remain the most common route for externally applied prosthetics; additive manufacturing introduces process‑centric validation requirements. Firms must invest in process validation, device histories, and software change control now, not as a later add‑on.
-
Manufacturing footprint: Firms must choose between centralizing to capture scale‑economies and decentralizing to shorten clinical lead times and enable localized customization. Business models that hybridize (centralized critical components with localized final fitting) are emerging as pragmatic compromises.
Commercial and Reimbursement Playbook for 2026
-
Engage payers with evidence packages aligned to HCPCS descriptors and PDAC guidance; early alignment with DME MACs will materially reduce authorization friction for new prosthetic fabrication workflows.
-
Differentiate through service: bundled offerings combining scanning, socket customization, device fitment and follow‑up rehab services command premium positioning versus pure hardware sales.
-
Leverage clinical champions and real‑world evidence: multi‑center outcomes data demonstrating improved function and satisfaction shorten sales cycles with hospital systems and enhance payer negotiations.
-
Channel strategy: sustainable routes-to-market will include hospitals and clinics, rehab centers, direct-to-user models, and NGO partnerships — each requires different pricing, warranty and logistics planning.
Where PW Consulting’s Report Adds Tactical Value
Our full report is written for leaders making capital allocation, M&A, manufacturing, and go‑to‑market decisions in 2026. The publisher’s deliverables are purpose-built to be actionable:
-
Scenario‑based financial models that stress test manufacturing strategies, reimbursement outcomes, and pricing strategies.
-
Reimbursement playbook that walks through HCPCS alignment, PDAC submission considerations, and payer engagement timing following the 2025 guidance.
-
Supplier and technology matrix comparing SLS/MJF, resin systems, post‑processing, and material choices (with vendor benchmarking and unit‑cost sensitivities).
-
Go‑to‑market blueprints tailored to direct sales, clinical partnerships, NGO distribution, and hybrid service models, with contract templates and pilot KPIs.
-
Competitive playbooks with strategic counter‑moves for the firms profiled above, and an M&A screening tool to identify consolidation and capability‑acquisition targets.
Note: To preserve the strategic value of this briefing and to respect client confidentiality requirements, this public summary highlights aggregate market size and growth rates but does not disclose detailed regional, product, or end‑user share tables. The full report contains granular segmentation, regional revenue schedules, and unit‑level pricing models that are available only through PW Consulting’s report access channels.
Immediate Decisions for 2026
-
Prioritize quick wins in reimbursement: finalize PDAC coding strategies and pilot Medicare billing pathways now to realize revenue lift in 2026.
-
Decide on manufacturing posture: conduct a rapid make‑vs‑buy analysis that incorporates 3D printing CAPEX, capacity lead times, and labor upskilling needs.
-
Invest in outcomes data: fund at least one multi‑site real‑world outcomes study to support payer negotiations and differentiate in procurement bids.
-
Map strategic partnerships: identify clinical, technology and NGO partners that complement your chosen route-to-market and can accelerate adoption with minimal capital outlay.
PW Consulting’s Worldwide 3D Printed Prosthetic Hands Market report is designed as an operational playbook for 2026 decision‑makers who must transform regulatory and manufacturing momentum into sustainable commercial advantage. For access to the full dataset, regional and subsegment schedules, and bespoke advisory engagements, please visit our report page or contact PW Consulting directly for an executive briefing.
For detailed analysis of this topic, please visit the official page: Worldwide 3D Printed Prosthetic Hands Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide RNA Cleanup Market at USD 525.0 Million in 2025, Forecast to Reach USD 950.5 Million by 2032 at 8.85% CAGR
By pmarketresearch, 2026-08-18
Worldwide RNA Cleanup Market: Strategic Imperatives for 2026 — PW Consulting Market Brief
Executive snapshot
Between 2020 and 2025 the worldwide RNA cleanup market expanded from approximately USD 345.5 million to USD 525.0 million, driven by accelerating throughput in next‑generation sequencing (NGS), expanded in vitro transcription (IVT) workflows for mRNA modalities, and growing adoption of automation across life‑science laboratories. Our base‑case forecast projects the market to reach roughly USD 574.4 million in 2026 and to approach USD 950.5 million by 2032, corresponding to a compound annual growth rate of 8.85% over the 2026–2032 forecast window. For executive teams planning investments, partnerships or portfolio pivots in 2026, these macro dynamics create a narrow window to lock in supply, validate next‑generation offerings, and shape commercial positioning ahead of sustained growth.
Worldwide HTAP-Enabling In-Memory Computing Technologies Market
Why this report matters for 2026 decision cycles
Strategic choices made in 2026 will determine whether organizations capture disproportionate share of the expansion that follows. The market is maturing: demand is less about single‑use commodity sales and more about integrated workflows, regulatory alignment for therapeutic applications, and supply resilience. Our report synthesizes quantitative forecasting with executable commercial playbooks — enabling leaders to prioritize R&D allocation, procurement safeguards, and channel strategies without getting lost in tactical minutiae.
Worldwide 5G Network Equipment on Top of Antennas Market
Key trends shaping strategy
- Therapeutics and diagnostics are raising the bar. Regulatory guidance from major authorities emphasizes rigorous characterization of RNA integrity and purity for therapeutic use, moving cleanup from a “laboratory convenience” into a documented critical control point. This drives demand for GMP‑grade inputs, validated protocols, and supplier traceability.
- Automation and throughput are non‑linear drivers. Automation investments—spurred by high‑throughput sequencing centers, spatial transcriptomics, and contract testing laboratories—are accelerating adoption of bead‑based and automated cartridge solutions that simplify hands‑on time and reduce variability.
- Raw‑material and supply chain constraints. Critical components such as silica membranes and magnetic beads are regionally concentrated and experienced multi‑week delivery delays in prior cycles. GMP‑compliant chemistries and plastics face capacity constraints that can bottleneck scale‑up for therapeutics.
- Cost and material policy pressures. Episodic reagent price spikes during demand surges have been observed historically, and regulatory measures (for example, directives on single‑use plastics) are extending product development timelines as vendors redesign components for recyclability or alternative polymers.
- Competitive consolidation alongside specialist insurgency. The market displays a measurable degree of concentration: a handful of large, diversified life‑science suppliers dominate core workflows, while nimble specialists and platform partners push innovation in bead chemistry, miniaturization, and high‑recovery formats.
Practical contents of the PW Consulting report
Clients can expect an operationally focused deliverable that bridges strategic foresight and implementation. The report contains:
Short Drama Promotion Authorization Platform Market
- A transparent market model with historical (2020–2025) actuals and scenario‑based forecasts to 2032, enabling sensitivity testing against price shocks, adoption curves, and capacity constraints.
- Supply‑chain risk mapping: supplier concentration, critical raw‑material sourcing, lead‑time stress tests, and mitigation playbooks for dual‑sourcing and inventory strategy.
- Technology and product taxonomy: evaluation of silica‑based, magnetic bead, and alternative chemistries; automation readiness scoring; and technology migration timelines aligned to therapeutic and diagnostic requirements.
- Regulatory pathway dossiers: implications of FDA/EMA guidance on analytical characterization and GMP sourcing, plus compliance checklists for developers entering therapeutic markets.
- Commercial playbooks and price‑elasticity analysis: GTM segmentation, channel configuration guidance, and recommended pricing approaches under volatile reagent cost scenarios.
- Competitive landscaping and vendor scorecards: capability matrices, strategic strengths and vulnerabilities, and prioritized partnership targets for M&A or co‑development.
- Actionable 90‑ to 360‑day implementation plans tailored to incumbent vendors, emerging suppliers, and end‑user laboratories.
Competitive landscape: how incumbent and specialist strategies diverge
The vendor field is a mix of global life‑science titans and focused innovators. Leading multinational suppliers leverage broad portfolios, global distribution, and integrated automation platforms to offer end‑to‑end workflows that appeal to large sequencing centers and clinical labs. Specialists and medium‑sized players compensate with rapid product iterations, niche chemistry advances, and targeted channel partnerships.
- Large OEMs and platform players. Companies with extensive automation and reagent portfolios are positioned to bundle cleanup solutions into higher‑value offerings for clinical and high‑throughput segments. Their scale enables global regulatory support and integration with instrument systems, making them preferred partners for translational and clinical customers.
- Mid‑market innovators. Specialized firms compete on recovery rates, low‑volume concentration performance, and ease of automation. Their agility is reflected in targeted launches and collaborations that extend into spatial transcriptomics and IVT workflows.
- Startups and service providers. Small entrants find footholds in niche use cases—single‑cell prep, small RNA cleanup, or high‑throughput bead‑based plates—often becoming acquisition targets for larger players seeking rapid capability build‑out.
Notable market moves and tactical implications
- Product launches expanding magnetic bead automation have shortened throughput timelines for RNA purification, enabling vendors and labs to advertise same‑day IVT‑to‑sequencing workflows. Organizations should evaluate pilot integrations now to be deployment‑ready in 2026.
- Collaborations between purification specialists and sequencing platform companies are emerging, particularly around spatial transcriptomics. These partnerships accelerate adoption cycles by delivering validated, end‑to‑end solutions favored by translational researchers.
- Planned discontinuations and portfolio rationalizations—paired with suppliers transitioning to new chemistries or disposable designs—require customers to assess migration paths and re‑qualify processes to avoid downstream disruption.
- Regulatory expectations and GMP constraints are driving up the cost and time required to certify materials at scale; firms that pre‑qualify suppliers and invest in secured manufacturing capacity will gain first‑mover advantage for therapeutic supply contracts.
Strategic recommendations for 2026 decision‑makers
- Lock in dual sourcing for critical inputs. Given historical multi‑week lead‑time volatility for beads and membranes, buyers should establish validated secondary suppliers and safety stock policies to prevent program delays.
- Prioritize automation‑ready R&D. Invest in bead‑based and cartridge formats designed for robotics and high‑throughput platforms. Early pilots with key sequencing or automation partners accelerate commercial uptake.
- Accelerate regulatory alignment. For firms targeting therapeutic markets, commence analytical validation and GMP supplier qualification now—regulatory guidance has elevated cleanup to a measurable quality attribute.
- Mitigate material‑policy risk. Re‑engineer single‑use designs in anticipation of plastics‑policy changes to avoid late‑stage development delays and ensure continuity in European markets.
- Use pricing hedges and cost‑transparency clauses. Protect margins against episodic reagent price spikes via indexed contracts, advance purchase agreements, and pass‑through mechanisms where appropriate.
- Consider bolt‑on acquisitions or partnerships. For companies seeking rapid access to high‑recovery chemistries, automation compatibility, or validated clinical supply chains, targeted M&A or licensing can compress time‑to‑market significantly.
How PW Consulting positions clients for execution
Our approach moves beyond forecasting to executable plans. We provide clients with vendor‑level scorecards, procurement negotiation templates, a validated supplier shortlist for GMP inputs, and a 12‑month operational roadmap that aligns R&D milestones with regulatory submission timelines and commercial launch windows. For commercial teams, we model go‑to‑market permutations (direct, distributor, instrument bundling), and quantify revenue and margin impacts under multiple demand and price‑shock scenarios.
Closing perspective
As the RNA cleanup market scales toward therapeutics and high‑throughput applications, competitive advantage will accrue not to the company that claims the best chemistry, but to the organization that couples technical excellence with supply resilience, regulatory credibility and seamless automation support. 2026 is a pivotal planning year: choices about supplier strategy, product architecture, and partner ecosystems will determine who captures the disproportionate returns of the next growth phase.
Next steps
This brief outlines the strategic stakes and immediate implications. For access to the full dataset, vendor scorecards, confidential M&A targets, and the step‑by‑step 90‑ to 360‑day implementation playbooks referenced here, please consult the complete PW Consulting Worldwide RNA Cleanup Market report and supporting models on our client portal.
For detailed analysis of this topic, please visit the official page: Worldwide RNA Cleanup Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Predicts Worldwide Naval Vessel MRO Market to Reach USD 89,260 Million by 2032
By pmarketresearch, 2026-08-18
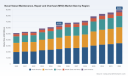
Worldwide Naval Vessel Maintenance, Repair and Overhaul (MRO) Market: Strategic Imperatives for 2026 Decisions
PW Consulting’s newest Worldwide Naval Vessel MRO Market study synthesizes five years of historical performance and a forward-looking forecast to 2032, delivering a rigorous, decision-grade resource for defense planners, shipyard executives, OEMs, and private equity investors preparing for 2026. The market reached approximately USD 64,120 Million in 2025 and is projected to expand to roughly USD 68,315 Million in 2026, with a modeled trajectory that reaches near USD 89,260 Million by 2032 — a 4.84% compound annual growth rate across the 2026–2032 forecast window. This release explains why 2026 is a turning point for strategic investments and operational choices in naval sustainment, and which levers will determine who captures the long-term value.
Worldwide Industrial Arc Furnaces Market
Why 2026 is a Pivotal Year
-
Geopolitics and the shifting maintenance footprint: Recent awards and partnerships, particularly in the Indo‑Pacific, have accelerated allied MRO capacity outside traditional Western hubs. Several South Korean yards have secured high-profile U.S. Navy logistics vessel contracts, underscoring a more distributed approach to fleet sustainment that will affect basing, supply chains, and contingency planning in 2026.
Turntable Slip Rings Market -
Regulatory guardrails that reshape choices: Statutory constraints such as U.S. domestic repair requirements for homeported Navy vessels continue to create a bifurcated market for domestic vs. allied MRO activity. At the same time, defense budget allocation patterns indicate a heavy emphasis on propulsion and dry‑dock workstreams — engine and dry‑dock activities now exceed 55% of reported maintenance spending in several analyses — focusing attention on specialized capability nodes.
Worldwide Impairment Goggles Market -
Cost drivers and operational risk: Raw material and labor dynamics are increasing unit costs for shipyards and sustainment providers. For example, naval‑grade steel prices in Northeast Asia rose to roughly USD 1.81/kg in early 2026, while U.S. shipyard labor income levels remain high and workforce shortages persist, intensifying upward pressure on MRO margins and creating a premium for productivity improvements.
What the Report Delivers — Practical, Executable Intelligence (keeps the granular splits secure)
-
Robust market sizing and trend analysis: A verified historical dataset covering 2020–2025 and a transparent forecasting engine for 2026–2032 that isolates demand drivers by vessel lifecycle stage, service type, and macroeconomic scenarios. The headline market totals and CAGR are published to guide portfolio sizing; granular segment tables and regional detail are included in the full report.
-
Actionable decision frameworks: Bid/no‑bid thresholds for large‑scale depot contracts, investment case templates for greenfield/expansion capex, and contract structuring checklists to minimize revenue volatility from lifecycle peaks.
-
Supply‑chain stress tests and scenario planning: Quantified scenarios modeling commodity spikes, labor constraints, and base‑relocation events, each mapped to P&L impacts and capex timing recommendations.
-
Competitive playbooks and M&A scouting: Empirically grounded profiles of incumbent and emerging MRO players, capability gap maps, and an M&A prioritization matrix that balances strategic fit, regulatory exposure, and integration risk.
-
Operational modernization roadmaps: Step‑by‑step guidance on digital MRO adoption, remote diagnostics, predictive maintenance deployment, and workforce reskilling to lift throughput while protecting quality and compliance.
Competitive Landscape — Who Matters and Why
The global MRO ecosystem remains concentrated around diversified prime integrators and specialty engineering houses. Market concentration metrics show that the top three players hold a meaningful share of industry revenues and that the top five firms capture a clear majority of identifiable market turnover — a structure that favors scale, integrated logistics, and strategic relationships with navies and defense ministries.
-
Huntington Ingalls Industries (Newport News, VA): A dominant US‑flag platform for high‑complexity sustainment — notably nuclear carrier refueling and submarine overhauls — HII’s recent supply‑chain and capacity expansions are explicitly geared to cement lead positions in long‑cycle naval programmes.
-
General Dynamics (Reston, VA): Through its NASSCO and Electric Boat units, General Dynamics provides a geographically diversified sustainment footprint across auxiliary and submarine fleets. Its portfolio emphasizes depot capabilities and multi‑port support lanes.
-
BAE Systems and Babcock (UK): These firms combine dry‑dock heft with systems‑level upgrade and combat‑system sustainment, serving both domestic fleets and export customers via through‑life support contracts.
-
Naval Group, Fincantieri, Navantia, and ThyssenKrupp: European primes that integrate design, newbuild, and refit expertise — their through‑life support offers remain significant for allied and export customers seeking one‑stop sustainment partners.
-
OEM and systems specialists (Rolls‑Royce, Thales, Kongsberg, Lockheed Martin): These companies increasingly capture higher‑margin MRO work around propulsion, sensors, combat systems, and prime electronics through long‑term support contracts and spare‑parts agreements.
-
Regional and niche players (Austal, HD Hyundai, Larsen & Toubro, Damen): These yards compete on rapid turnaround, specialized hull materials (e.g., aluminium), and regional proximity — factors that matter for littoral fleets and logistics ship sustainment.
Recent developments underscore competitive dynamics that will shape 2026 strategic choices: HD Hyundai’s contract wins for logistics‑class vessel overhauls and the entry of Korean yards into U.S. Navy logistics work signal a more competitive global market for auxiliary sustainment; Huntington Ingalls’ acquisitions to strengthen submarine MRO supply chains indicate continued consolidation at the high‑complexity end of the market.
Operational Levers for 2026 Decision‑Making
-
Prioritize capability adjacency over scale alone: Investment in propulsion overhaul capabilities, dry‑dock availability, and nuclear/complex systems know‑how yields premium revenue access. For firms without those capabilities, partnerships or minority stakes in specialists provide faster access than full greenfield builds.
-
Design contracts around predictability: Shift fixed‑price elements to indexed or milestone‑based structures that account for material price swings and labor availability. Hedging strategies for naval‑grade steel and long‑lead components materially reduce margin erosion.
-
Localize selectively to manage regulatory exposure: Understand where domestic repair statutes or basing patterns create protected workstreams versus where allied ports are viable for auxiliary classes. For U.S. Navy homeported assets, domestic compliance remains non‑negotiable; allied hubs can serve logistics and ancillary flows.
-
Invest in digital MRO and workforce productivity: With labor representing a substantial share of ship costs and with skills shortages persistent, adoption of predictive maintenance, augmented reality for diagnostics, and modular tasking models delivers outsized returns on throughput.
-
Adopt a portfolio approach to risk: Balance legacy, high‑complexity work (steady, long‑duration margins) with faster‑turnaround, lower‑duration contracts that smooth revenue and utilize spare capacity between major availabilities.
Implications for Capital Allocation and M&A in 2026
Capital discipline will separate winners. The market’s structural growth (mid‑single digit CAGR across the forecast window) justifies selective capacity expansion, but investments must be prioritized where barriers to entry are highest — nuclear/complex propulsion, integrated combat systems MRO, and strategic dry‑dock assets. M&A targets that offer regulatory advantage, unique technical capabilities, or a foothold in allied basing networks should command premium valuations. Our report provides a prioritized watch list and valuation bands calibrated to 2026 contracting cycles and policy timelines.
How PW Consulting Can Help
-
Customized scenario modeling calibrated to your asset base and contract profile (including commodity and labor stress tests).
-
Bid/no‑bid decision support and contract optimization templates tailored to naval sustainment procurement rules and local content constraints.
-
M&A diligence playbooks and integration roadmaps for acquiring technical specialists or expanding regional repair networks.
Next Steps — Secure the Full Intelligence Package
This bulletin outlines the strategic contours and executive implications of our full Worldwide Naval Vessel MRO Market study. The comprehensive report contains the granular segmentation tables, regional breakdowns, and supplier‑level financial models that underpin the actionable recommendations summarized here. For a copy of the complete report, the M&A watch list, and a tailored briefing on what the 2026 contracting environment means for your organization, please visit PW Consulting’s report page or contact our naval sustainment practice. The full dataset and scenario models are available to subscribers and clients who require decision‑grade detail.
For detailed analysis of this topic, please visit the official page: Worldwide Naval Vessel Maintenance, Repair and Overhaul (MRO) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Pyrogenicity Testing Services Market Poised to Nearly Double — From USD 1,150 Million in 2025 to USD 2,003 Million by 2032 at an 8.25% CAGR
By pmarketresearch, 2026-08-18
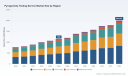
Pyrogenicity Testing Service Market — 2026 Strategic Preview
Executive teaser
PW Consulting’s new market study on Pyrogenicity Testing Services positions industry leaders and decision-makers to act with clarity in 2026. The market has moved from a modest, specialist domain into a growth corridor driven by regulatory inflection points, method substitution, and expanding biologics and device pipelines. This briefing summarizes the strategic implications you need now — enough to inform executive priorities and budgets — while reserving detailed segment-level datasets for the full report to which this release directs interested stakeholders.
Buried Obstruction Survey Market
Market snapshot: macro trajectory
Using 2025 as the base year, our model traces a sustained expansion of the pyrogenicity testing services market through the 2026–2032 forecast window. The market rose steadily in the 2020–2025 period and is projected to continue at a compounded annual growth rate (CAGR) of approximately 8.25% over the forecast horizon. Under the scenarios we modeled, the overall market value roughly doubles over the full forecast period, reflecting both volume growth and a structural shift in the mix of testing approaches and service delivery models. Market concentration is moderate: the three largest providers account for a meaningful share of supply, and the top five approach half of industry capacity, creating an environment where scale and validated method portfolios matter.
1.5µm Fiber Laser Module Market
Why this matters for 2026 decision-making
- Regulatory momentum is converting method preference into commercial opportunity. Organizations that adopt validated non-animal methods early can secure first-mover advantage for regulatory submissions and customer contracts.
- Service differentiation is increasingly technical rather than geographic. Proprietary platforms, validated MAT workflows, and end-to-end regulatory support are now decisive procurement criteria for sponsors.
- Capital allocation choices hinge on capability bets. Investing in in vitro platforms, automation, and MAT validation yields faster pathway alignment with key markets and reduces long-term reliance on legacy animal testing.
- Outsourcing strategies must be rethought. Sponsors will weigh in-house MAT capability versus specialist CRO partnerships based on speed-to-compliance and cost per validated claim.
Regulatory inflection points reshaping the market
- European Pharmacopoeia policy changes implemented in 2025 that advance replacement of the Rabbit Pyrogen Test with validated non-animal alternatives are a pivot point for European market dynamics and have ripple effects globally.
- Regulatory dialogue has accelerated: a recent validation strategy published in late 2025 broadens the circumstances under which MAT is acceptable to U.S. and other regulators, increasing sponsor willingness to adopt MAT for pivotal dossiers.
- Forums such as the early-2026 EDQM-EPAA symposium have codified expectations for pyrogen testing “2.0,” emphasizing harmonization and evidence packages that combine technical performance with human-relevant readouts.
- Standards and guidance documents — including ISO technical references and FDA device guidance — continue to require product-specific limits and test justification, so method substitution is seldom automatic; it requires documented validation and regulatory engagement.
Competitive landscape: what incumbents and challengers are doing
Leading global laboratory networks and product providers are executing distinct, but complementary, strategies to capture growth:
Worldwide Electronic Grade Microsilica Market
- Charles River Laboratories leverages a global footprint with comprehensive service lines — MAT, RPT, and LAL — positioning itself as the partner of choice for biologics and device sponsors seeking end-to-end testing plus regulatory consulting.
- Eurofins BioPharma Product Testing is accelerating its transition to non-animal approaches, combining MAT services with endotoxin detection (LAL and recombinant factor C variants) and regulatory support to enable sponsor migration strategies.
- NAMSA remains a key specialist for medical device pyrogenicity, emphasizing material-mediated testing per ISO and USP frameworks and advising device manufacturers on design and submission strategy tied to pyrogen risk.
- Lonza is advancing the equipment and reagent layer through PyroCell and related MAT systems, enabling both internal lab adoption and the commercialization of standardized MAT platforms for third-party labs.
- SGS integrates pyrogen testing into a broader pharmaceutical and device laboratory network, giving it utility in geographic markets where customers prefer bundled laboratory services.
- Associates of Cape Cod (ACC) focuses on LAL-based technologies and remains relevant where endotoxin-specific workflows are dominant or where legacy LAL testing will continue in the near term.
Recent industry updates — published validation strategies, standards adoption, and symposia — have accelerated competitive positioning. Some providers emphasize laboratory-scale MAT validation and external accreditation, others invest in platform licensing and reagents, and still others consolidate device-focused competencies. The result is a market in which partnerships, platform plays, and accreditation credentials are key differentiators.
Strategic implications and recommended actions for 2026
Below are pragmatic, prioritized steps for each stakeholder group to convert market momentum into measurable advantage this year.
- Pharmaceutical & biotechnology sponsors: Initiate or accelerate MAT validation plans for relevant product classes; develop regulatory engagement playbooks that include cross-reference literature and bridging studies; selectively outsource to MAT-capable CROs during an initial adoption phase to de-risk submission timelines.
- Medical device manufacturers: Review device classification and contact pathways in light of ISO/TR 21582 and FDA expectations; build material-mediated pyrogen testing into design controls; partner early with specialist labs to establish test acceptance for international markets.
- Contract testing laboratories and CROs: Prioritize investment in MAT systems, staff training, and quality controls; create bundled service packages (e.g., endotoxin screening + MAT + regulatory dossier support) to capture higher share of sponsor spend and shorten sales cycles.
- Platform and reagent providers: Consider SaaS-enabled data packages for MAT validation, licensing models for reagent supply, and co-marketing with CROs to embed platforms in the testing workflow.
- Investors and M&A teams: Focus on assets that combine validated MAT capability with regulatory consulting, or that provide scalable MAT equipment and consumables; the market’s mid-level concentration suggests consolidation opportunities among regional providers.
- Regulators and standards bodies: Prioritize clarity on validation expectations for MAT and other non-animal methods to reduce sponsor uncertainty and speed harmonized adoption across jurisdictions.
Operational playbook: 0–90 day roadmap
- Days 0–30: Conduct an internal gap analysis — map current testing methods against regulatory expectations and identify immediate capability shortfalls. Begin vendor short-listing focusing on MAT validation experience and accreditation.
- Days 30–60: Initiate pilot engagements with one or two labs to validate workflows for representative product types; assemble a submission-ready validation dossier template informed by recent regulatory guidance and industry symposia outcomes.
- Days 60–90: Decide on scale strategy (in-house vs. outsourced), lock in supplier agreements for critical consumables or platform licensing, and update product development timelines and budget forecasts to reflect pyrogen testing pathway changes.
What the PW Consulting report contains (teaser)
The full Pyrogenicity Testing Service Market report includes:
- A validated market model (historical 2020–2025; forecast 2026–2032) with scenario analysis and sensitivity to regulatory adoption rates.
- Vendor benchmarking and capability scorecards that evaluate technical portfolio, validated MAT capacity, geographic reach, accreditation, and commercial positioning.
- Regulatory timeline and playbooks tailored to biologics, combination products, and medical devices, including dossier checklists and evidence packages aligned to recent guidance.
- Price and margin assessment for testing service lines, go-to-market strategies for labs, and commercial impact estimates for accelerated MAT adoption.
- Risk heatmaps and mitigation strategies covering supply chain of reagents, accreditation hurdles, and regional acceptance differences.
- Actionable M&A and partnership frameworks to guide investor screening and integration planning.
In keeping with our “trailer” approach, we intentionally reserve the granular segmentation tables, supplier-level revenue splits, and region/application-specific percentage shares for the full report and the supporting online data pack.
Concluding perspective for 2026
The pyrogenicity testing market is no longer a niche laboratory service; it is a strategic enabler for product approvals and market access. Growth is robust and method substitution is reshaping where value accrues — to those who control validated MAT workflows, scalable platforms, and regulatory expertise. For corporate leaders, the decisions made in 2026 around validation investments, supplier selection, and capability footprints will determine not only compliance but competitive positioning for years to come.
Next step
PW Consulting’s full report provides the datasets, vendor scorecards, and decision tools required to operationalize the recommendations above. For access to the complete analysis, methodology, and the withheld segmentation details that inform our revenue and demand models, visit our report landing page or contact our advisory team for a briefing tailored to your organization’s needs.
For detailed analysis of this topic, please visit the official page: Pyrogenicity Testing Service Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide In‑Car Infotainment Market Set to Expand at a 10.21% CAGR Through 2032, New Report Finds
By pmarketresearch, 2026-08-18
Worldwide In‑Car Infotainment Market: Strategic Imperatives for 2026 — A PW Consulting Preview
Executive snapshot
PW Consulting’s new market study on the Worldwide In‑Car Infotainment Market sets the strategic frame for decisions that will define supplier positions, OEM roadmaps, and investor value creation through the rest of this decade. The in‑car infotainment market has accelerated from an early‑decade base to exceed USD 33.6 billion in our 2025 base year and is projected to roughly double by the end of the 2026–2032 forecast window, tracking a compound annual growth rate of approximately 10.21%. That momentum — underpinned by rapid software migration, 5G-enabled experiences, and growing services monetization — creates both urgent opportunities and material risks for market participants planning 2026 investments.
Worldwide Subscription Analytics Software Market
Why 2026 is the strategic inflection point
-
Technology convergence is changing the value equation. The shift to software‑defined vehicle (SDV) architectures, combined with the mainstreaming of Android Automotive and partnerships between chipset and cloud providers, is compressing time‑to‑market for advanced cockpit capabilities. Recent industry moves — including expanded Qualcomm–Google collaboration and OEM supply agreements announced in early 2026 — make platform selection and long‑term supplier commitments high‑stakes decisions this year.
Worldwide 5-Fluorouracil Market -
Regulatory and privacy dynamics are tightening monetization levers. In 2026, new enforcement actions and state‑level privacy rules are reshaping how vehicle data can be collected, shared, and commercialized. Suppliers and OEMs can no longer assume consumer data will remain a free, unrestricted source of value; consent architectures and transparent data governance must be operationalized before new subscription models are launched.
Worldwide Gas Gravitometers Market -
Cost and supply considerations are crystallizing hardware‑software trade‑offs. The industry is balancing the incremental value of 5G and AI features against module, TCU and roadside infrastructure costs. Hardware choices made in 2026 will lock in cost bases and upgrade paths for multiple model cycles — influencing margins and upgrade economics through 2032.
Market dynamics shaping strategic choices
-
Software first, hardware second: Infotainment is migrating from a hardware‑driven product to a software and services platform. Feature differentiation increasingly comes from user experience, AI services, cloud connectivity and OTA update capabilities rather than raw display or audio specs. This accelerates the importance of middleware, lifecycle support, and recurring revenue models.
-
Connectivity and edge compute: 5G and edge services enable new media, safety, and location experiences — but they also introduce new distribution costs. The emergence of retrofitable AI extension platforms and long‑term chipset supply agreements reported in early 2026 demonstrates how the ecosystem is moving to decouple new capabilities from wholesale hardware redesigns.
-
Regulatory and privacy pressure: In 2026 regulators have intensified scrutiny of vehicle data use. Enforcement actions and new consent requirements mean commercial pilots and subscription rollouts must embed privacy‑by‑design and auditable consent flows. Failure to do so risks not just fines, but loss of consumer trust and blocked business models.
-
Consolidation and collaboration: The competitive landscape shows both vertical integration by large Tier‑1s and strategic alliances among chipset vendors, cloud providers and OEMs. This hybrid model strengthens incumbents with platform capabilities while creating white‑space for specialized suppliers that can demonstrate unique services or integration speed.
Competitive landscape — who matters and why
The market is populated by a mix of global Tier‑1s, OEM captive suppliers, consumer electronics entrants, and specialized aftermarket players. Critical firms to watch include established infotainment and cockpit platform providers, audio and head‑unit specialists, and those advancing SDV enablement:
-
Harman International (Samsung) — premium connected infotainment systems, digital cockpit platforms and Android Automotive solutions embedded in many global OEM programs.
-
Robert Bosch GmbH — integrated infotainment and AI cockpit solutions with a growing focus on retrofitable software extensions demonstrated at CES 2026.
-
Continental AG — smart vehicle architectures and biometric features that bridge infotainment with ADAS and domain control strategies.
-
Denso Corporation — deep OEM relationships, telematics expertise, and user‑experience focused solutions aligned with major manufacturing programs.
-
Panasonic (Automotive Systems), Pioneer, Visteon, Aptiv, Alpine/ALPS ALPINE, JVCKENWOOD (Clarion), LG Vehicle Component Solutions, Mitsubishi Electric, Garmin, Hyundai Mobis and FORVIA (Faurecia) — each plays distinct roles across head units, displays, HMI, platform software and integration services.
These companies are simultaneously competitors and partners. Strategic alliances — for example, OEMs locking in chipset roadmaps with large silicon vendors or partnering with cloud/OS providers — will determine who captures platform economics versus who earns integration premiums.
Recent developments with immediate strategic implications
-
Bosch’s January 2026 announcement of an AI extension platform illustrates a practical pathway to retrofit AI capabilities into existing cockpits without full hardware replacement — an attractive option for OEMs seeking feature acceleration while deferring capital‑intensive redesigns.
-
Qualcomm’s expanded collaboration with Google and the Volkswagen Group’s supply intent for Snapdragon Digital Chassis solutions signal that long‑term chipset‑to‑software alliances are central to SDV success. Firms must evaluate supplier roadmaps, update cadences and service layers when negotiating 2026 supply contracts.
-
Toyota’s integration of carrier 5G connectivity in refreshed models shows how OEMs are embedding operator relationships into product offers, a trend that will shape financing and subscription bundles.
-
Regulatory moves — including recent FTC action and accelerated state privacy rules — require companies to reconcile product roadmaps with consent mechanics, data localization and audit trails; these requirements influence not just compliance costs but the feasibility of certain data‑driven services.
What the PW Consulting report delivers (practical, decision‑ready contents)
-
Forward‑looking market model with annualized revenue forecasts across 2026–2032, stress‑test scenarios for alternate technology and regulatory outcomes, and sensitivity analyses tied to hardware cost trajectories and subscription uptake.
-
Strategic supplier heatmaps and capability matrices that map technology ownership, service readiness, and integration risk — enabling procurement teams to prioritize partners by program risk and margin impact.
-
Commercial playbooks for monetization, including subscription rollout sequencing, bundling strategies with connectivity providers, and privacy‑aligned consent frameworks that meet emergent regulatory expectations.
-
Technology roadmaps and scenario planning for 5G, edge compute, AI‑enhanced UX, and OTA architectures — calibrated with component cost inputs and infrastructure considerations to quantify TCO and upgrade economics.
-
M&A and partnership target shortlists based on capability gaps, go‑to‑market acceleration potential, and platform fit — accompanied by valuation sensitivities and integration playbooks.
Actionable recommendations for leaders planning 2026 investments
-
Prioritize platform modularity and OTA lifecycle management. Whether you are an OEM or Tier‑1 integrator, designing for continuous software delivery and decoupled hardware refresh cycles preserves optionality and reduces stranded investment risk.
-
Embed privacy and consent into product architecture today. New enforcement trends mean that subscription and data monetization pilots must include auditable consent flows and data minimization by default — retrofitting these mechanisms later is costly and brand‑damaging.
-
Structure supplier agreements for shared roadmap visibility. Long‑term chipset and cloud relationships are now strategic assets; contracts should include update cadences, security SLAs and co‑development clauses to avoid platform lock‑in or capability gaps.
-
Run parallel hardware‑light and hardware‑heavy scenarios. Bosch’s AI extension approach and similar retrofit strategies offer a lower‑capex path to deliver advanced features; concurrently maintain options for integrated hardware redesigns where OEM differentiation justifies the spend.
-
Quantify infrastructure and lifecycle costs for connectivity. Decision models must include 5G module pricing, TCU economics and potential roadside unit investments when evaluating total cost of ownership and service margins.
How PW Consulting’s insights convert to board‑room decisions
This report is designed to convert market intelligence into executable plans: it aligns financial forecasts with procurement choices, maps competitive moves to partnership opportunities, and ties regulatory scenarios to product and legal risk. For boards and C‑suites preparing budgets and strategic plans in 2026, our analysis clarifies where to allocate incremental capital, which partnerships accelerate time‑to‑market, and how to defensibly price subscription services within tightening privacy regimes.
Next steps
The preview above highlights high‑level conclusions and actionable recommendations drawn from PW Consulting’s full Worldwide In‑Car Infotainment Market report. To preserve the utility of our proprietary segment models and supplier scorecards, we intentionally limit publication of granular splits in this release. The full report includes detailed regional and component-level modeling, supplier concentration analysis, and playbooks tailored to OEMs, Tier‑1s, aftermarket players and financial sponsors.
For access to the comprehensive dataset, scenario models, and executive briefing packages that support 2026 decision cycles, please visit PW Consulting’s report page or contact our research team to schedule a tailored executive briefing.
For detailed analysis of this topic, please visit the official page: Worldwide In-Car Infotainment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Automotive Connectivity Control Unit (CCU) Platform Market Set to Surge to USD 11,186.13 Million by 2032 on a 15.62% CAGR
By pmarketresearch, 2026-08-18
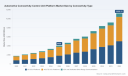
Worldwide Automotive Connectivity Control Unit (CCU) Platform Market — Strategic Preview for 2026 Decision-Makers
PW Consulting today releases a strategic preview of our forthcoming Worldwide Automotive Connectivity Control Unit Platform Market report. As vehicle architectures pivot toward centralized compute, software-defined functions and multi-modal connectivity, CCU platforms have become a mission-critical node for monetization, safety and fleet operations. Our research projects a robust medium-term expansion — underpinned by a compounded annual growth rate (CAGR) of 15.62% — that turns connectivity hardware decisions made in 2026 into value-creation or value-eroding choices across 2026–2032.
Worldwide Synthetic Lace Front Wigs Market
Why this report matters for 2026
-
Timing: 2026 is the inflection year when early production programs incorporating 5G, satellite-assisted telemetry and consolidated central compute move from pilot to scale. OEMs and Tier-1 suppliers deciding platform architectures this year will lock in technology, supply chain and partner obligations that influence product roadmaps for the next decade.
Worldwide MySQL Training Service Market -
Scale: Our topline market model shows a multi-billion-dollar market expanding substantially through the forecast period, driven by rapid adoption of high-bandwidth telematics, OTA orchestration, and new vehicle-to-cloud business models.
Worldwide Lithium Battery Anode Materials Market -
Concentration and competitive dynamics: The market is partially concentrated among a small set of established Tier-1s and technology players. This creates both consolidation risk and partnership opportunity — a critical input for M&A and procurement strategy.
Report utility — what executives and strategy teams will get
-
Board-grade market sizing and forecast: A rigorous base-year assessment and detailed scenario projections through 2032 that quantify upside under accelerated 5G/NTN adoption and downside under semiconductor constraints.
-
Decision-ready segmentation and architecture analysis: Comparative evaluations of centralized versus zonal approaches, dedicated CCUs versus integrated domain controllers, and the trade-offs in cost, weight, cybersecurity surface, and upgradeability.
-
Supply chain stress tests: Vendor concentration mapping, single-source risk flags, and mitigation playbooks that translate semiconductor shortage or supplier disruption into quantified operational risk metrics.
-
Vendor benchmarking and engagement frameworks: A performance matrix that rates functional capability (e.g., multi-modal connectivity, OTA maturity, edge compute capacity), commercial posture, and integration complexity — enabling rapid shortlisting for design-in and partnership pilots.
-
Commercial models and revenue levers: Paths to capture subscription, data monetization and fleet management revenue, and the implications of software lifecycle economics (e.g., OTA cadence, security updates) on TCO and residual value.
-
Regulatory & standards playbook: Mapping of emerging global standards (digital key, V2X) and a compliance roadmap to minimize time-to-market friction across major jurisdictions.
-
M&A and investment signals: Identification of strategic gaps where bolt-on acquisitions or minority investments unlock capabilities (satellite comms, cybersecurity, OTA cloud orchestration, edge AI) more quickly than in-house builds.
Competitive landscape — what the major players are positioning
-
Robert Bosch GmbH: Continuing to position CCUs as a central connectivity hub, Bosch emphasizes hardware robustness and integration with vehicle-to-cloud services — attractive for OEMs prioritizing deep systems integration and proven automotive-grade supply chains.
-
Continental AG: Focused on telematics control units that align with software-defined vehicle architectures, Continental’s offerings are tailored for OEMs seeking modularity and lifecycle OTA governance.
-
HARMAN International: Notably active on the multimodal front, HARMAN couples telematics units with infotainment ecosystems and has accelerated satellite-native connectivity capabilities through recent partnerships.
-
Aptiv PLC: Aptiv’s emphasis is on high-speed electrical architectures and holistic vehicle compute platforms, which suit programs aiming to minimize wiring complexity while maximizing data throughput.
-
Denso Corporation: Denso continues to be a key player for communications devices and telematics modules, leveraging longstanding OEM relationships in Asia and beyond.
-
LG Electronics: Recent product unveilings highlight LG’s push into 5G telematics with AI-enabled features — positioning for premium segments and next-gen connected services.
-
Visteon Corporation: Visteon’s cockpit and connectivity domain controllers appeal to OEMs pursuing zonal or centralized cockpits that integrate CCU functions for seamless user experiences.
-
AutoCore (China): Emerging platform specialist offering integrated CCU/ZCU solutions and software stacks — a candidate for partnerships or supply diversification on programs prioritizing local sourcing or cost leadership.
Our qualitative and quantitative benchmarking highlights that while legacy Tier-1s bring automotive-grade reliability and deep OEM relationships, newer entrants and semiconductor-aligned players are rapidly closing capability gaps — especially in areas like satellite-native telematics, secure enclave architectures, and integrated modem-software stacks.
Recent market signals that must inform 2026 choices
-
Standards and industry coordination: Initiatives such as the Car Connectivity Consortium’s recent assemblies are accelerating harmonized approaches to digital keys, V2X and fleet management — reducing fragmentation risk but also compressing windows for standards-driven product updates.
-
Technology inflection: The industry shift toward “One Board / One Chip” central compute architectures materially changes CCU design trade-offs — shrinking size and weight but increasing integration complexity and thermal management requirements.
-
Supply-side fragility: Semiconductor interruptions in late 2025 exposed fragilities that continue to affect choice of silicon partners, dual-sourcing strategies and inventory policies. Our supply-chain modules quantify the cost of single-source dependencies and scenario-test buffer strategies.
-
Multi-modal connectivity: The emergence of satellite-enabled telematics and native NTN support elevates resilience and reach for fleet and remote operations — with new partnerships forming between wireless chipset vendors, platform integrators, and telematics specialists.
Implications by stakeholder — practical guidance for the 2026 playbook
-
OEMs and system architects: Prioritize platform decisions that preserve headroom for OTA-driven feature enrichment and ensure modularity to accommodate semiconductor substitution. Evaluate centralized compute not as a cost-saver alone but as a strategic anchor for lifecycle monetization.
-
Tier-1 suppliers: Balance long-term R&D investment in software and cloud orchestration with selective partnerships for radio and satellite front-ends. Use the report’s vendor matrix to structure win-win roadmaps with lead OEM customers.
-
Telecom and cloud providers: Position offerings around managed connectivity bundles, edge-cloud orchestration and security subscriptions rather than raw connectivity, as OEMs seek simplified integration and predictable TCO.
-
Investors and corporate development: Use our M&A heatmaps to identify targets that complement existing stacks — especially those that accelerate access to satellite, secure trust anchors, or OTA platforms without protracted integration timelines.
How to operationalize the insights in 90–180 days
-
Day 0–30: Run a rapid “architecture safety audit” using our checklist to flag single-source risks, thermal constraints and OTA readiness for active programs.
-
Day 30–90: Shortlist a small set of CCU platform partners using our benchmarking matrix and initiate integration pilots that exercise OTA flows, satellite fallbacks and cybersecurity incident response.
-
Day 90–180: Finalize sourcing and partnership contracts with staged delivery milestones tied to interoperability tests, semiconductor resilience clauses and clear IP governance for data monetization.
What we intentionally withhold in this preview
Consistent with the report’s role as a boardroom-grade commercial instrument, this preview intentionally avoids granular disclosure of segment-level revenue splits, regional allocation percentages, and confidential vendor share estimates. Those high-resolution data and the underlying modelling assumptions are core deliverables of the full report and are provided to clients and subscribers to preserve commercial integrity and enable defensible negotiations.
Closing — the strategic value for 2026
Decisions made in 2026 on CCU platforms will have cascading effects across product cost, cybersecurity posture, customer experience and recurring revenue potential. PW Consulting’s report synthesizes market sizing, competitive strategy, supply-chain contingencies and practical execution roadmaps to turn that complexity into executable strategy. With a market trajectory growing at a 15.62% CAGR and clear consolidation pressure among leading suppliers, the choice is not whether to act — it is how to act with precision.
For an executive summary, vendor scorecards and access to the full report and modelling workbooks, visit our Worldwide Automotive Connectivity Control Unit Platform Market page or contact PW Consulting’s Automotive Practice to schedule a briefing.
For detailed analysis of this topic, please visit the official page: Worldwide Automotive Connectivity Control Unit Platform Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com